Sovereignty Strengthens AI Revenue Opportunity for Telcos, but Obstacles Threaten to Slow Value Capture

Sovereignty is strengthening the new revenue opportunity for communication service providers (CSPs) stemming from AI, but sizeable obstacles are slowing their ability to capture value. One of the most significant emerging challenges facing telcos is the cost of AI. AI investment decisions are increasingly evaluated like other major capital and operating expenditures, with heightened focus on measurable returns, governance and cost discipline.

In the on-demand webinar below, Principal Analyst Chris Antlitz gives an update on the telecom AI market, including:

  • Why telcos are placing greater scrutiny on the ROI and economic sustainability of AI
  • How and why the sovereignty trend is expected to drive new revenue for telcos from AI
  • What the telco AI revenue opportunity looks like from a regional and country-level perspective


This TBR Insights Live session is available on demand on our YouTube channel. Visit this link to download the presentation’s slide deck.
 
If you’d like to further explore the data mentioned in this TBR Insights Live session, sign up for a free trial of TBR Insight Center™ today.
 
TBR Insights Live sessions are held typically on Thursdays at 1 p.m. ET and include a 15-minute Q&A session following the main presentation. Previous sessions can be viewed anytime on TBR’s Webinar Portal.

Convergence Takes Center Stage as U.S. Telecom Operators Pursue the Next Phase of Growth

The U.S. telecom market is entering a new phase in which convergence, broadband scale, and higher-value connectivity services such as AI infrastructure connectivity are becoming increasingly important competitive differentiators.
 
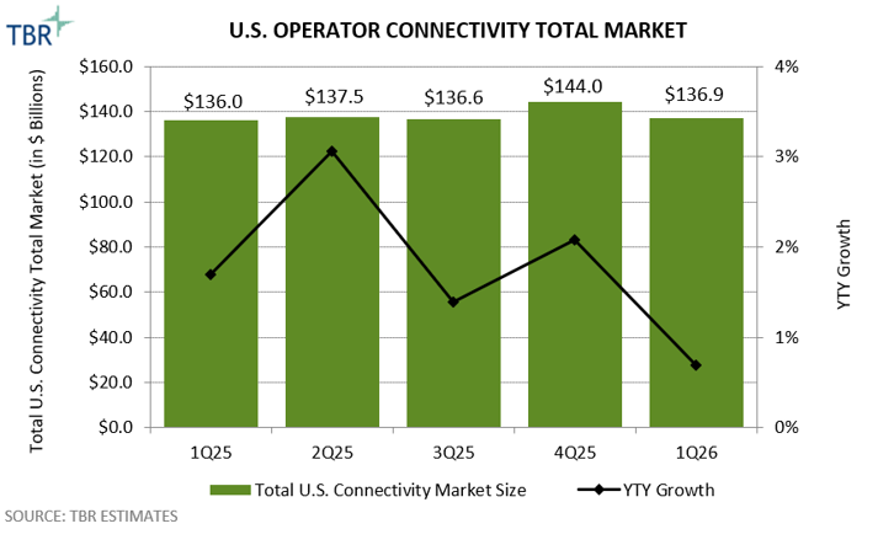
TBR’s latest U.S. Mobile and Broadband Operator Benchmark estimates U.S. operator connectivity revenue increased 0.7% year-to-year to $136.9 billion in 1Q26 as wireless service, equipment and broadband growth offset continued declines in legacy wireline and video services.
 
Revenue expansion slowed from 1.7% in 1Q25 as wireless service growth moderated and broadband competition intensified, increasing the importance of broadband scale, mobile-broadband cross-sell, and higher-value connectivity services as sources of incremental growth.
 

U.S. Operator Connectivity Total Market (Source: TBR Estimates)

M&A accelerates the convergence race

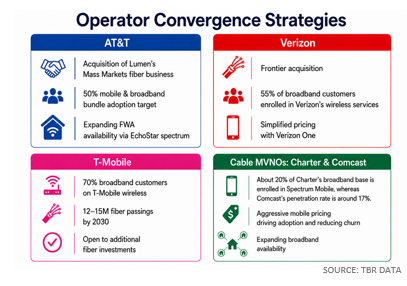
M&A is reshaping operator portfolios around converged connectivity and broader ownership of both wireless and broadband assets. Verizon’s Frontier acquisition and AT&T’s purchase of Lumen’s Mass Markets fiber business deepen their fiber portfolios, while T-Mobile’s fiber joint ventures involving Metronet and Lumos expand its reach beyond a primarily wireless and FWA model.
 
The pending Charter-Cox merger similarly increases cable scale across broadband and mobile. Collectively, these moves give operators greater control of both wireless and broadband infrastructure and position them to pursue integrated mobile-broadband strategies over the long term.
 

Operator Convergence Strategies (Source: TBR Data)

Fiber and FWA intensify the battle for broadband share

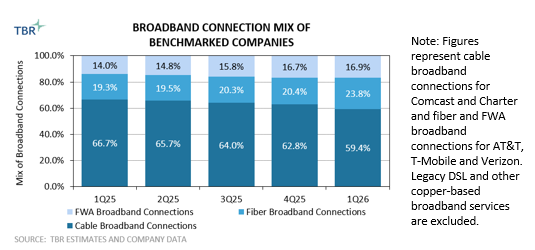
Broadband competition is increasingly shifting toward fiber and FWA as telcos expand coverage, and cable operators face continued subscriber pressure. FWA remains a key source of organic broadband growth, while fiber expansion and acquisitions are giving AT&T, Verizon and T-Mobile greater scale to compete for broadband households and support converged mobile-broadband strategies.
 
As fiber and FWA capture a larger share of broadband growth, Comcast and Charter are responding with aggressive mobile pricing to strengthen customer retention and defend their broadband subscriber bases.
 

Broadband Connection Mix of Benchmarked Companies (Source: TBR Estimates and Company Data)

Wireline growth pivots toward next-generation connectivity

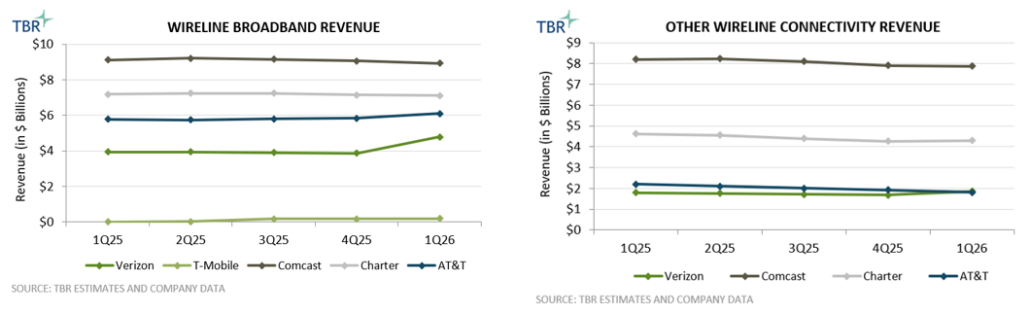
Wireline broadband revenue continues to expand for AT&T and Verizon as fiber connection growth more than offsets decreases in legacy broadband services such as DSL. T-Mobile is positioning for wireline broadband revenue growth through M&A and fiber expansion, broadening its presence beyond fixed wireless. In contrast, broadband revenue is declining at Comcast and Charter amid subscriber losses and intense competition from fiber and FWA. Other wireline connectivity revenue continues to decrease, driven by declines in mature services such as fixed voice, video and legacy data connectivity.
 
Over time, newer B2B solutions and advanced connectivity services will become increasingly important growth drivers. TBR sees AI infrastructure connectivity as one of the largest long-term wireline opportunities, driving demand for fiber, optical transport, data center interconnection, cloud on-ramps and edge computing. Cybersecurity, SD-WAN/SASE, managed networking and private cellular networks provide additional growth vectors.
 

Wireline Broadband Revenue and Other Wireline Connectivity Revenue (Source: TBR Estimates and Company Data)

Conclusion

The next phase of U.S. telecom growth will increasingly depend on how effectively operators combine wireless and broadband assets to deepen customer relationships and capture new revenue opportunities. M&A and fiber expansion are accelerating this shift, giving AT&T, Verizon, and T-Mobile greater broadband scale while prompting Comcast and Charter to compete more aggressively through mobile.
 
As legacy wireline services decline, operators will also need to expand into higher-value connectivity segments, including AI infrastructure connectivity, advanced enterprise networking and managed services. Ultimately, broader connectivity portfolios will only create value if operators can translate them into higher mobile-broadband penetration, lower churn and sustainable revenue growth.

A Winning Strategy in IT Services and Consulting

We have voluminous data at TBR, 30-plus years of data and analysis on the largest and leading companies across the technology stack, from McKinsey & Co. to Wipro, from Amazon Web Services to Verizon. Because we publish data and analysis quarterly, looking back one year and forward two to five years, we don’t often take the longitudinal view. Looking at our research since October 2021 (18 months after the start of the pandemic) to today, what can we say about the strategies, business models and investments that have separated leaders from laggards, particularly in the IT services and consulting space?
 
The short answer is talent and training; technology partnerships; and platforms, reusable IP and automation. If you’ve been reading our reports, you already knew that.
 
Longer answer: The companies that grew fastest generally combined one inorganic lever with several organic ones. Acquisitions or mergers produced large, immediate revenue spikes and confidence in a company’s growth story. More durable growth came from converting acquired capabilities into recurring managed services, cloud and application modernization, data and AI services, cybersecurity, industry solutions and broader client relationships. That’s a near-exhaustive list, and TBR’s most consistent advice has been that companies should do what they do well and only what they do well. But a consistent pattern emerges from that list: acquire capabilities, package those capabilities into differentiated offerings, cross-sell through partners and existing accounts, and deliver through recurring or managed services models. Easy, right?

Which overall strategies produced growth over the last few years, especially in IT services and consulting?

Acquisitions generated the most visible short-term revenue increases when companies added one or more of four assets: an existing client base that could be cross-sold existing offerings; specialized capabilities in cloud, data, AI, IT engineering or cybersecurity; that magical blend of credible global reach and authentically local presence; and recurring managed services, business process or subscription revenues. No company acquires like Accenture, but that simply means the 800,000-pound gorilla exemplifies the serial-acquisition model. Accenture’s investment capacity allows it to spend ahead of peers, add capabilities continually and enter adjacent markets. When looking at Accenture and its peers, TBR’s analysis distinguishes between lower-risk consulting acquisitions, which usually center on relationships and near-term revenue, and higher-risk AI platform and data acquisitions, which promise differentiation but have less-certain returns. By the start of 2026, industry-specific AI, data engineering and AI infrastructure had become central acquisition priorities across IT services companies and consultancies. Notably, many people lump mergers and acquisitions together, despite the significant difference. In our analysis since late 2021, mergers produced some of the highest reported growth rates, although the first-year results were often more inorganic than operational. For example, NTT DATA’s addition and integration of NTT Ltd. materially boosted 2023 revenue and expanded NTT DATA’s ability to sell integrated networking, data center, infrastructure and IT services. By 2025, closer alignment with parent NTT was creating additional cross-selling opportunities, stronger financial backing and a more unified enterprise proposition.
 
New offerings provided strong organic growth, with the most successful new offerings addressing work that clients could not defer indefinitely. Long-duration application, infrastructure and business process contracts produced more predictable revenue than discretionary consulting. During the last few years, the Big Four significantly expanded managed services and transaction services to protect client relationships and compete beyond advisory work. Application management, hybrid cloud, SAP modernization and platform engineering also generated significant revenues even when IT directors complained about tight digital transformation budgets (see TBR’s Digital Transformation: Voice of the Customer Research for details). Of course, new AI capabilities generated new revenues, especially when IT services companies and consultancies connected AI to data modernization, operating efficiency and industry workflows, not just isolated proofs of concept. For example, HCLTech’s AI Factory, Physical AI and data intelligence offerings contributed to its strongest growth since 2023. In addition, cybersecurity — in which companies perennially underinvest — as well as sovereign cloud and localized delivery, shifted from optional growth areas to required capabilities, particularly in Europe and among regulated industries.
 
In addition, strategic investments didn’t generate revenue spikes but remained essential for sustained growth. Training employees in hyperscaler platforms, generative AI, data engineering and industry skills helped IT services companies and consultancies execute increasingly complex, AI-enabled programs. At the same time and, for the leading companies tightly correlated, structured and strategic relationships with the hyperscalers, software vendors and semiconductor companies expanded market access while reducing the cost of building capabilities internally. Over the last few years, Accenture, Capgemini, HCLTech, IBM Consulting and the Big Four increasingly used partnerships to create multiparty offerings. And AI-enabled delivery, agent frameworks and reusable assets improved productivity and allowed IT services companies and consultancies to package services more consistently. Notably, according to TBR’s analysis, AI adoption by IT services companies and consultancies continues to contribute more to productivity and scope expansion than to broad-based revenue acceleration.

The next winning strategy

Since October 2021, traditional global systems integrators have generally produced steady single-digit growth. Accenture, Cognizant, HCLTech, Infosys and Tata Consultancy Services have stayed in the top 10 for year-to-year revenue growth in TBR’s IT Services Vendor Benchmark as their large-deal pipelines, installed client bases, partner ecosystems and managed services exposure have provided greater revenue stability.
 
In the same period, IT services companies and consultancies have derived the fastest growth from changing the revenue mix, not simply adding more people: recurring services instead of projects, industry solutions instead of generic capabilities, platforms and AI-enabled delivery instead of labor-only delivery, and acquisitions that could be cross-sold rather than merely consolidated. That has been the winning strategy for the last few years.
 
Will it remain a winning strategy for 2027 and beyond? AI might upend significant parts of the technology stack and force disruption of every company’s business model, but playing to strengths, doing only what you do well, and staying flexible in your commercial model will likely remain core attributes of leading IT services companies and consultancies.

AI-wrapped IT Modernization Opportunities Will Serve as Both Marketing and Revenue-generating Engines as Infosys Builds Verticalized Use Cases Tied to Outcomes to Expand AI Revenue Share

Infosys is using AI to sell modernization — not replacing modernization with AI

With front-office transformation remaining among the top AI use cases, Infosys is leaning on Infosys Aster to drive opportunities beyond campaign execution and into a broader platform for redesigning knowledge-intensive marketing and content workflows, evidenced by the deal with Handelsblatt Media Group and the launch of CMO AI hub in collaboration with ANA’s Global CMO Growth Council. These two use cases could allow Infosys to move from implementing marketing technology to advising CMOs on where AI should be deployed, but given the bespoke collaboration, the company will need to think more strategically to turn outcomes into repeatable IP and scale sales beyond one-off engagements.
 
We estimate Infosys’ Digital Marketing Services revenue was $1.8 billion in 2025 and will reach $3.1 billion by 2030, with the company largely leaning on its core application services capabilities to drive development and management of web, mobile and commerce offerings. Using Infosys Aster as the entry point to AI-led marketing transformation could help Infosys shift the revenue mix toward managed-services-led consulting work.
 
Infosys’ opportunity is not simply to sell more AI tools but also to use AI as the reason clients modernize applications, clean data, rethink workflows and consolidate vendors. That positioning matters because buyers remain practical: They want productivity, measurable outcomes and lower operating complexity, not another layer of technology hype.
 
Supporting both open and closed public models through Infosys Topaz Fabric will give the company the flexibility to strengthen its position as an AI orchestrator. We believe supporting both models is table stakes for a services provider that, for years, has played the technology-agnostic game with its alliance partners. The true value will come from Infosys’ ability to deploy its frontier engineers at speed and capture the right balance of AI-first and AI-infused revenue opportunities, as the former will help it drive higher pricing and the latter will increase client stickiness. Managing expectations for impatient shareholders will be key, especially as peers pursue similar strategies.

Capturing foundational revenue opportunities will remain essential as Infosys looks to balance driving AI-first and platform-enabled sales to build a beachhead for long-term opportunities across lines of business

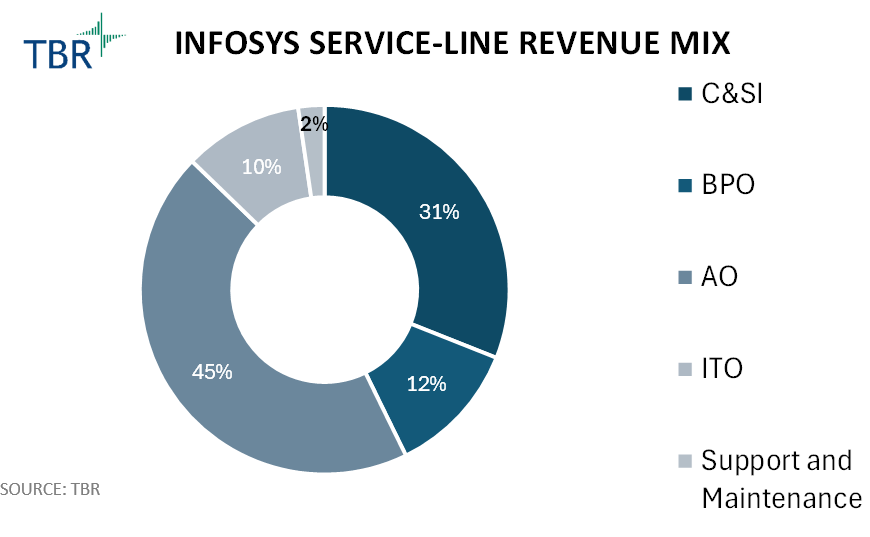
As Infosys enhances and expands its AI-ready portfolio, the company understands the value of long-term IT modernization contracts, especially as AI services revenue is only 8.2% of its total revenue in 2Q26. Deal wins in 2Q26 with Truist Financial for Global Capability Center (GCC) setup and management, Sterling Bank for Finacle implementation, IHH Healthcare for AI-enabled ERP transformation, DNB Bank ASA for financial crime operations modernization, and Global Foundas for AI-enabled IT modernization and managed services, among other engagements, demonstrate Infosys’ commitment to securing its foundational revenues, especially after the company faced headwinds in renewing the entirety of its marquee deal with Mercedes-Benz in 1Q26.
 

Infosys Service Line Revenue Mix (Source: TBR)


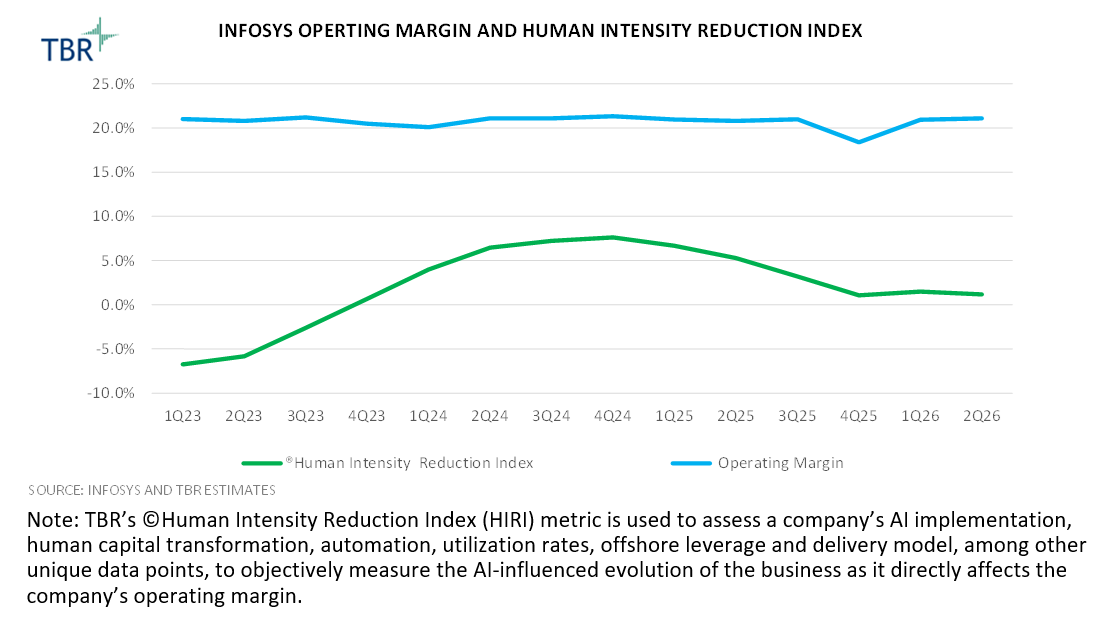
Infosys Operating Margin and Human Intensity Reduction Index (Source: TBR)


Although we do not expect Infosys to slow its pursuit of such deals anytime soon, the company needs to balance AI labeling with real AI usage to avoid AI washing. Generating $1 billion of AI services revenue is a milestone worth recognizing, but pushing the narrative too much could increase the cannibalization of traditional revenue. While TBR will continue to monitor and estimate Infosys’ AI performance, we believe that the company will become less vocal about itemizing AI sales in the next two to three years.

The Paradox of AI Infrastructure: Hyperscalers’ Ambition Collides With the Power Grid and What This Means for Telcos

The AI infrastructure supercycle is entering a new phase. The central question is no longer whether hyperscalers have the capital or appetite to build AI infrastructure but whether the power grid can support what they intend to build.
 
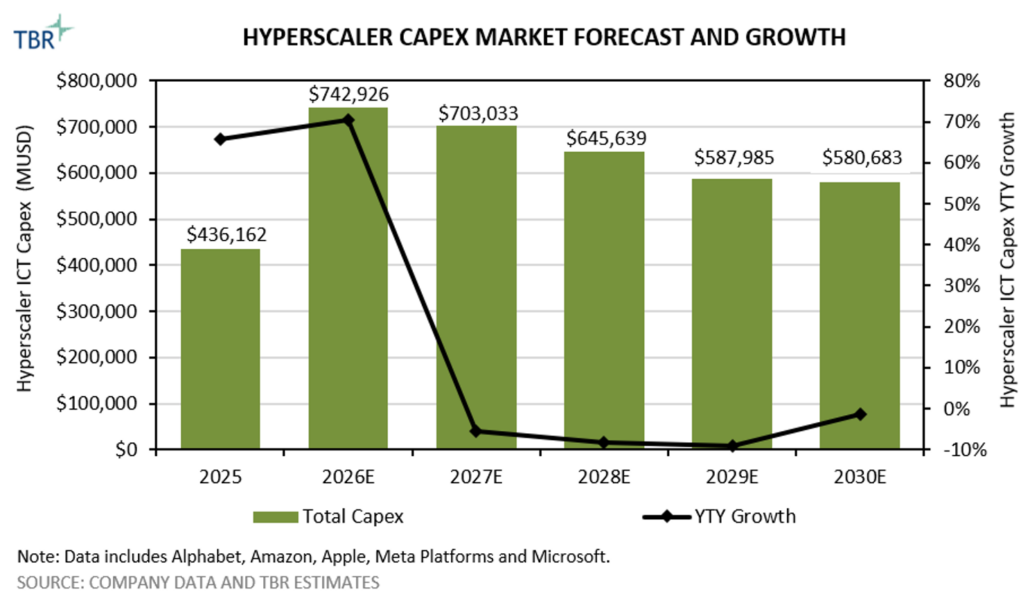
TBR’s latest Hyperscaler Capex Market Forecast 2025-2030 estimates that Meta, Alphabet, Microsoft, Amazon and Apple (MAMAA) will collectively spend approximately $743 billion in capex in 2026, up 70% year-to-year. Much of that investment is flowing into AI-related infrastructure, including data centers, servers, storage and networking.
 
But capital alone cannot build the AI economy. Increasingly, the constraint is energy.

Power is becoming the limiting factor

U.S. data center developers have requested 1,066 GW of electricity, equivalent to roughly 83% of existing U.S. utility-scale generation capacity. Yet an August 2026 Bloomberg study titled “Most Power Sought for US Data Centers Will Never Materialize” indicates utilities and grid operators can ultimately commit to only about 28% of that amount.
 
Some of that demand is undoubtedly inflated by duplicate or speculative applications. Even so, the underlying problem is clear: Generation capacity as well as grid infrastructure and interconnection timelines cannot expand at the pace AI investment currently requires.
 
Hyperscalers are already responding. TBR noted in the same forecast that Alphabet, Amazon, Microsoft and Meta are increasingly looking beyond conventional utility procurement and pursuing natural gas, renewables, energy storage, nuclear and geothermal resources.
 
That shift has significant competitive implications. Access to power is evolving from an operating requirement into a strategic differentiator. The companies that can secure reliable energy — and place compute where that energy is available — will be better positioned to translate AI capex into usable capacity.

For telecom operators, the collision between AI and energy creates both opportunity and strategic risk

The first wave of generative AI infrastructure has been dominated by centralized training clusters, helping to delay the long-anticipated shift toward more distributed edge cloud infrastructure. That dynamic could begin to change as AI moves increasingly from training toward inferencing.
 
Inference workloads that require lower latency, faster response times, or proximity to users and devices will create greater incentives to distribute compute closer to endpoints. At the same time, power constraints could push AI infrastructure into a wider range of locations based on not only proximity to demand but also access to available electricity. That combination could make the AI infrastructure footprint substantially more distributed.
 
For telecom operators, this creates an important opening. Hyperscalers will need greater network capacity to connect AI infrastructure spread across data centers, edge locations and new power-rich geographies. Telecom networks therefore become increasingly important not simply as pipes connecting compute but also as infrastructure that enables hyperscalers to place compute wherever power, economics and workload requirements are most favorable.
 
A more distributed inference architecture could also alleviate some pressure on large, centralized power hubs by spreading portions of AI compute across a broader infrastructure footprint. It will not solve the underlying energy shortage, but it could change how — and where — that constraint is managed.
 
TBR Graph: Hyperscaler Capex Market Forecast and Growth

Conclusion

The next infrastructure bottleneck for AI may not hinge solely on computational power but could be significantly influenced by energy availability.
 
As the demand for new AI capabilities rises, power constraints will likely reshape the geography of data centers and accelerate the distribution of inference workloads. Moreover, the strategic importance of telecom networks will increase as they connect an increasingly fragmented AI infrastructure landscape.
 
Consequently, the upcoming phase of the AI infrastructure supercycle could be characterized as much by access to megawatts and connectivity as it is by the availability of GPUs.

AMD Enters the Execution Phase of its Full-stack AI Strategy

Advancing AI 2026 showed that AMD has assembled the architecture and road map required to compete at rack scale. Helios connects the company’s GPUs, CPUs, networking and software into a system-level platform, while expanding partnerships with Microsoft, OpenAI, Anthropic and Meta provide credible paths to large deployments. ROCm.ai gives AMD a new way to reduce the engineering effort required to bring up and optimize applications on Instinct GPUs. Agentic workloads also expand the AI-driven opportunity for EPYC beyond its role as a host CPU for accelerators, allowing AMD to address the agent sandboxes, applications, databases and data services surrounding GPU inference.

Hidden Costs of AI Market Intelligence

From AI assistants to enterprise intelligence infrastructure

For most organizations, the economics of enterprise AI begin with a familiar metric: the software subscription. Whether evaluating ChatGPT Enterprise, Microsoft 365 Copilot or another generative AI platform, procurement teams often focus on a straightforward calculation of monthly cost per employee.
 
That view captures only a fraction of the enterprise AI equation.
 
The larger expense emerges after deployment, as thousands of employees begin incorporating AI into their daily work. The ease of generating research, analysis, presentations and strategic content encourages broader adoption, more frequent interaction and increasingly sophisticated requests. Every prompt initiates inference. Every inference consumes compute. Every generated response requires some degree of human validation before it influences an important business decision.
 
As the cost of generating intelligence declines, the demand for intelligence expands.
 
This is a modern expression of Jevons Paradox. Throughout history, improvements in efficiency have rarely reduced overall resource consumption. Instead, they have lowered the barriers to use, encouraging dramatically higher levels of consumption. Steam power increased coal demand. Cloud computing reduced the cost of infrastructure while driving unprecedented growth in compute utilization.
 
Enterprise AI is following a similar trajectory, replacing physical infrastructure with machine cognition as the resource being consumed.
 
The implications become apparent when AI is deployed across an entire enterprise.
 
Sales organizations generate competitive battle cards. Product marketing develops positioning documents. Corporate strategy evaluates competitors and ecosystem partners. Customer success prepares executive briefings. Regional teams produce account-specific analyses. Communications teams draft white papers and case studies.
 
Viewed independently, each request appears inexpensive. But viewed collectively across thousands of employees, these activities often represent repeated attempts to answer substantially the same strategic questions. Similar prompts generate similar analyses, consuming new inference capacity each time while producing variations in language, emphasis and interpretation. The organization pays repeatedly to recreate knowledge that, in many cases, already exists somewhere within the enterprise.
 
The resulting cost extends beyond tokens or compute consumption. Enterprises also see duplicated validation efforts, fragmented institutional knowledge, inconsistent market messaging, and strategic drift across customer-facing materials. Two sales teams may describe the same competitor differently. Marketing may publish messaging that differs from corporate strategy. Product managers may rely on analyses that have already been superseded by more recent market developments.
 
The issue is not that AI generates poor content. The issue is that, without a common intelligence foundation, decentralized generation produces decentralized understanding.
 
As enterprises mature their AI strategies, many are beginning to rethink where AI should generate knowledge and where it should retrieve knowledge.
 
This distinction is becoming increasingly important. AI models excel at synthesizing information, adapting content to specific audiences, and producing incremental analysis. They are less effective as the sole source of authoritative market intelligence, particularly when that intelligence must remain consistent across thousands of employees and hundreds of customer interactions.
 
An emerging architectural pattern addresses this challenge by introducing a trusted intelligence layer between enterprise users and the language model. Rather than asking AI to reconstruct market intelligence from public information each time a question is asked, organizations provide AI with access to continuously maintained repositories of validated research, competitive analysis, benchmark data, and proprietary industry intelligence. The model retrieves trusted information first and then applies its reasoning capabilities to contextualize, summarize and personalize the response for the user’s specific objective.
 
The result is a shift from repeated generation to governed reuse.
 
This architecture changes the economics of enterprise AI in several important ways. Reusable intelligence reduces unnecessary inference, lowers duplicate validation efforts, accelerates response times, and creates a persistent body of institutional knowledge that improves with every update rather than disappearing at the end of each conversation. Equally important, it establishes a consistent strategic narrative across customer-facing deliverables.
 
For organizations competing in dynamic technology markets, narrative consistency has tangible business value. Battle cards, white papers, executive presentations, case studies, sales proposals, analyst briefings, and account strategies should reinforce a common view of competitors, ecosystem partners, market trends, and corporate differentiation. When every employee independently generates these materials through public AI models, subtle variations inevitably emerge. Over time, those variations dilute strategic messaging and increase governance risk.
 
Trusted third-party intelligence providers can play an important role in this architecture.
 
Organizations such as Technology Business Research, Inc. (TBR) continuously develop proprietary competitive intelligence, quantitative benchmarks, ecosystem analysis and market research that extend beyond the knowledge available in publicly trained language models. When this intelligence is licensed through APIs or securely incorporated into enterprise retrieval architectures, AI no longer begins each interaction from a blank slate. Instead, it reasons from an authoritative and continuously updated foundation.
 
And the value extends beyond only reducing inference costs. Trusted external intelligence provides an objective source of market truth that complements internal expertise while enabling consistent positioning across the enterprise. Marketing, product management, sales, strategy and executive leadership can draw from the same validated knowledge base while allowing AI to tailor outputs for different audiences without altering the underlying strategic narrative.
 
This represents a meaningful evolution in enterprise AI. The competitive advantage no longer comes solely from selecting the most capable language model. It comes from building an intelligence architecture that combines AI reasoning with governed, reusable and continuously refreshed knowledge.
 
Organizations that embrace this approach are likely to realize two complementary benefits: a reduction in the hidden costs associated with repeatedly generating the same intelligence and strengthened consistency and credibility of every market-facing interaction.
 
The enterprises that succeed will not be those that provide unrestricted AI access to every employee. The winners will build trusted intelligence architectures enabled with proprietary, non-public data and analysis that prevent organizations from paying thousands of times for the same expensive thought.
 
The future of enterprise AI is not simply broader access. It is governed intelligence aligned to enterprise strategy, with CFO approved efficiency. And increasingly, that efficiency may prove more valuable than the AI models themselves.

Global Analyst Summit 2026: Value Creation Through Operating Model Transformation  

As consulting continues to evolve due to AI’s influence on business models and day-to-day operations across enterprises, EY’s leaders discussed how the firm is adapting its approach to guide clients through uncertainty and increased speed of change, and introduced featured clients, giving them an opportunity to share their experiences. The client stories emphasized the speed at which they need to navigate market changes and their desire to work with a long-term partner such as EY to guide the transformation as well as to create an ecosystem of vendors that support their end goals. The notion of value was consistent throughout the event, as the firm seeks to reconfirm its positioning in the consulting space despite ongoing market uncertainty about consulting’s future relevance.

AI Disruption: New Data on Productivity, Profitability and Business Model Evolution

Every company and consultancy faces pressure to change, but they’re not all evolving at the same pace and with the same AI-induced intensity

AI’s massive disruption across the professional services space has created pressure on companies to change their commercial, operational and partner models, as well as relentless expectations that the human component of service delivery will succumb to radical reorganization.
 
TBR’s research shows this is only the beginning, making it the perfect time to measure and evaluate the effects of internal adoption of AI-enabled solutions within these IT services firms and consultancies.
 
TBR’s new ©Human Intensity Reduction Index (HIRI) is a proprietary metric that measures changes in productivity at companies that primarily deliver human-centric services, taking into account nuances around utilization, automation and organizational change alongside AI adoption. Clients can then compare HIRI to a company’s or consultancy’s operating margin to assess how internal AI efforts are (or are not) leading to more profitable revenue.

In the on-demand webinar below, Patrick Heffernan, Principal Analyst & Practice Manager, and Bozhidar Hristov, Principal Analyst, discuss:

  • What questions large-scale IT services companies and global management consultancies have about reinventing their business models as they adopt AI-enabled solutions
  • How TBR can answer those questions with a mix of data and analysis and help clients understand what’s coming next
  • Which companies and consultancies can provide lessons learned for competitors and ecosystem partners


This TBR Insights Live session is available on demand on our YouTube channel. Visit this link to download the presentation’s slide deck.
 
If you’d like to further explore the data mentioned in this TBR Insights Live session, sign up for a free trial of TBR Insight Center™ today.
 
TBR Insights Live sessions are held typically on Thursdays at 1 p.m. ET and include a 15-minute Q&A session following the main presentation. Previous sessions can be viewed anytime on TBR’s Webinar Portal.

The Race for Digital Sovereignty: How 4 IT Services Leaders Are Positioned

TBR Fourcast is a quarterly blog series examining and comparing the performance, strategies and industry standing of four IT services companies. The series also highlights standouts and laggards according to TBR’s quarterly revenue projections as well as its geographic and segment estimates. With discussions about sovereignty in Europe only becoming louder, TBR thinks it is worthwhile to examine Atos Group, CGI, Fujitsu and Kyndryl. Our intent is to shine light on these similarly sized companies that have a strong presence in Europe and/or a strong presence in ITO and consulting and to discuss where each company’s opportunity lies.

Who will secure and defend market share in sovereignty in Europe?

In the sixth iteration of the Fourcast Blog, we examine the sovereignty market in EMEA across Atos Group, CGI, Fujitsu and Kyndryl.
 
Atos Group and Kyndryl share a similar motivation to pursue and expand sovereign capabilities. Atos Group is reducing its low-margin infrastructure services contracts and focusing on three target areas to improve revenue growth and regain market share: mission-critical agentic AI, digital sovereignty and cybersecurity. Similarly, Kyndryl aims to reduce the share of its low-margin infrastructure services contracts inherited from IBM and seeks deals in hybrid cloud, cybersecurity and agentic AI.
 
CGI and Fujitsu are both concentrating on scaling their global presence. Specifically, CGI is expanding its presence in Europe, and TBR predicts the company will enhance its sovereign capabilities in the second half of 2026 and in 2027. Similarly, Fujitsu has begun increasing its sovereign capabilities in Europe as it pushes to expand beyond Japan.
 
As sovereignty becomes an enabler for deals such as agentic AI and application modernization, developing the right solutions and go-to-market approach, while challenging established players such as Atos Group, will be a key battle in the coming years. The companies that most effectively combine sovereign solutions with IT consulting, hybrid cloud, secure infrastructure and AI governance and management expertise will be best positioned to defend existing accounts and capture new opportunities across Europe.
 

CGI is becoming a stronger rival to Atos Group. What now?

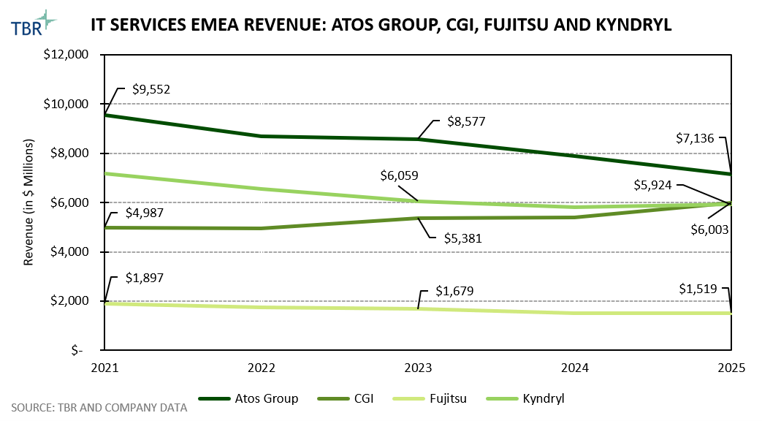
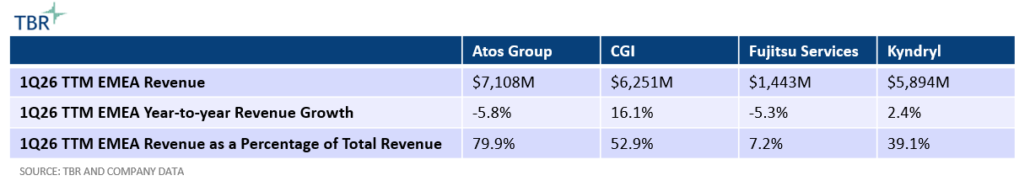
Five years ago, Atos Group’s trailing 12-month (TTM) EMEA revenue was approximately twice CGI’s revenue in the region, with Atos Group at $9.6 billion in 1Q21 compared to CGI’s $4.7 billion. Although Atos Group is historically a larger and more established company in EMEA, CGI has significantly expanded revenue in the region through selective acquisitions to build its geographic footprint. CGI focuses on underpenetrated regions and metro markets, including the Nordics and Baltics. CGI acquired Comarch Polska SA, expanding its presence in Poland and the Baltic states, with visible impacts in areas such as infrastructure services and consulting and systems integration (C&SI).
 
The company has announced a slew of engagements in the region during 2026, including a deal with the Finnish National Agency for Education, Stockman, Telia and Posti, all based in Finland. CGI is, in part, evading direct competition in the sovereign market to expand its revenue share; in contrast, Atos Group is focusing on its largest core geographies, such as France, U.K. & Ireland, and Germany, Austria & Eastern Europe, which collectively accounted for 53% of revenue in 1Q26. Atos Group’s renewed focus on its core territories will make it a greater threat to CGI in these regions.
 

If you believe you have access to TBR’s IT Services research via your employer’s enterprise license or would like to learn how to access the full research, click here.


CGI maintains a strong presence in Europe and France, Atos Group’s home territory. Although both companies now have similar revenue levels, CGI is not straying from expanding into France’s highly penetrated market. Last August, CGI completed the acquisition of Apside, a digital and engineering services firm headquartered outside of Paris with 2,200 employees in France and approximately $250 million in revenue.
 
However, the biggest challenge will be overcoming Atos Group’s established brand reputation in Europe. Atos Group’s long-standing work with commercial clients and public sector organizations such as the European Union (EU), national governments, NATO, EU cybersecurity bodies and municipalities has created a level of trust CGI will struggle to replicate. Atos Group’s work on sovereign AI platforms, critical infrastructure cybersecurity testing and emergency management systems reinforces its compliance expertise and operational credibility.
 
Recently, Atos Group launched its Digital Sovereignty offering, Threat Research Center, and Atos Sovereign Agentic Studios, signaling its push to embed AI-driven cybersecurity into enterprise operations, enhancing its revenue growth opportunities and resiliency. For these reasons, TBR believes Atos Group will be able to defend its turf in EMEA, despite its TTM EMEA revenue declining year-to-year since 1Q22. Long-term growth will depend on Atos Group’s ability to industrialize AI-led offerings, convert consulting capabilities into scalable revenue, and differentiate through sovereignty and systems integration rather than relying solely on innovation.
 
CGI is no stranger to mission-critical environments, but Atos Group is more explicitly tied to cybersecurity and sovereignty in mission-critical environments related to national security and defense. TBR believes CGI’s portfolio may be less developed in this regard. CGI emphasizes embedded capabilities, whether AI, security or other, as part of larger contracts that support clients’ needs holistically rather than with a one-size-fits-all solution.
 
CGI announced a sovereign AI and data services platform in Finland called KATAKRI that complies with local regulations. The platform runs on CGI’s hybrid service on a certified data center within the country, intended for classified and other sensitive workloads. TBR anticipates CGI will expand its sovereign capabilities, prioritizing underpenetrated regions. In this regard, it will be difficult for CGI or any competitor to completely shake Atos Group’s grip on France.

Where does Atos Group go from here?

TBR anticipates the company will double down on refining its portfolio to focus on what it does best — mission-critical cybersecurity and IT services — and will expand in its high-value and high-growth target areas, including mission-critical agentic AI, digital sovereignty and cybersecurity. Second, the company has a new corporate brand and national communications campaign in France.
 
As described in the 1Q26 Atos Group report, “The campaign supports Atos Group’s objective to rebuild client, investor and employee confidence while clarifying the relationship between the Atos (services) and Eviden (products) business lines. The new Accelerating Intelligence tagline supports the company’s positioning around AI-powered, sovereign- and cybersecurity-focused transformation services. The branding effort reflects Atos Group’s recognition that restoring commercial momentum requires more than operational restructuring and cost reduction.”

All roads lead to consulting

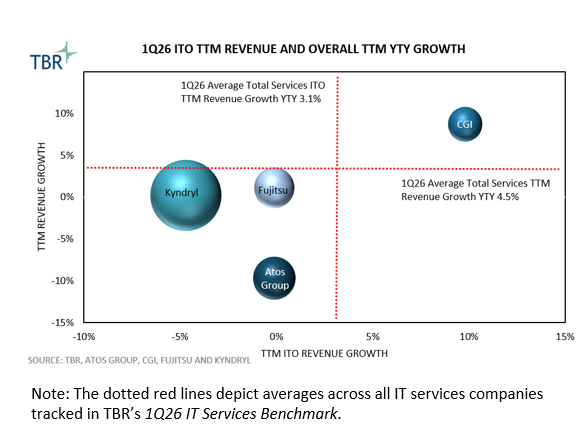
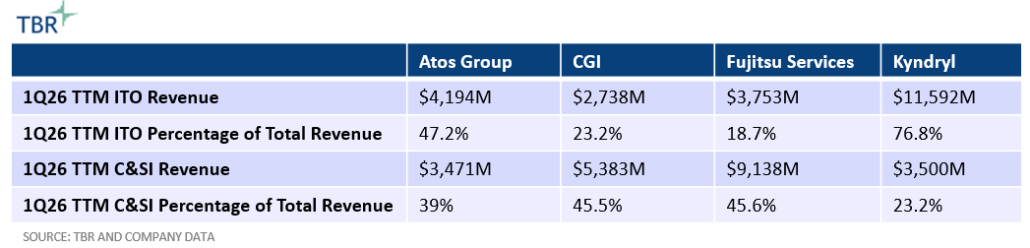
According to TBR’s proprietary data, Atos Group and Kyndryl have the largest ITO segments among the four companies. Further, ITO accounts for the largest revenue share for Atos Group and Kyndryl. ITO resources are foundational in sovereign delivery because they include cybersecurity teams, sovereign technology and dedicated managed infrastructure teams. In many ways, cybersecurity and sovereign demand have revived sluggish growth in the segment.
 
According to TBR’s IT Services Benchmark, TTM ITO revenue growth declined for seven consecutive quarters before rebounding in 4Q25 as these deals were realized. We expect the two companies’ presence in ITO, along with their portfolios of managing mission-critical environments, to provide a competitive advantage. As with Atos Group and CGI, Kyndryl has launched key solutions such as Kyndryl Sovereignty Solutioning, a suite of advisory, implementation and managed services. TBR believes this reflects the company’s focus on addressing data sovereignty, regulatory compliance and business continuity requirements.
 
Kyndryl also launched its first Cyber Defense Operations Center in India, a command hub that combines network operations and security operations, and the Kyndryl Intelligent Recovery Service, both of which indicate a shift toward making cyber resilience and recovery a central, differentiated capability as regulatory and operational pressures mount.
 
Despite improved performance in ITO currently, Atos Group and Kyndryl have been pivoting to consulting, in part to capture higher-value, higher-margin opportunities. Atos Group has formalized its consulting efforts by introducing Atos Amplify, a new unified and AI-powered consulting business unit. Similarly, Kyndryl is scaling Kyndryl Consult to shift toward higher-value transformation work rather than relying on legacy infrastructure outsourcing services. Kyndryl Consult’s revenue share has improved to approximately 23% of revenue in FY26, up from 19% of revenue in FY25, supported by AI modernization, cloud and cybersecurity.
 
By embedding AI into Kyndryl Consult, the company is moving to higher-value advisory and transformation services. Atos Amplify and Kyndryl Consult support a more comprehensive delivery strategy and will improve profitability for both companies.
 
Fujitsu is also expanding its consulting profile through Uvance, its consulting segment that addresses enterprise societal challenges, to drive revenue growth and broaden project scope. Although Uvance typically focuses on advisory services, Fujitsu is positioning itself around sovereignty to gain market share in Europe. Fujitsu recently introduced Digital Sovereignty Advisory Services, encompassing cybersecurity assessment and related security services concentrating on compliance with recent regulations for organizations in Europe.
 
Although a follower in sovereignty compared to peers such as Kyndryl and Atos Group, Fujitsu is well-equipped in certain pockets of Western Europe, leveraging its experience with Japan’s similar security initiatives and industry expertise. For example, Fujitsu is manufacturing sovereign AI servers as it adapts its focus in light of Japan’s Economic Security Promotion Act. Like CGI, TBR views Fujitsu’s messaging strategy and deal engagement as focused on holistic client outcomes, which makes its sovereign services slightly less visible.
 
Among the four companies, CGI and Fujitsu generate the most revenue from consulting and systems integration, segments that Atos Group and Kyndryl are trying to scale. While TBR expects CGI and Fujitsu to remain dedicated to consulting in EMEA, it raises the question: Why would CGI and Fujitsu also want to delve into the typically lower-margin ITO market?
 
The answer is twofold. First, increasingly complex infrastructure and digital landscapes, driven by new regulations, the advent of AI and rapidly changing macroeconomic environments, create more opportunities for consulting-enabled transformational engagements (along with enhancing their service quality). Second, for Atos Group and Kyndryl, consulting will help drive contracts in sovereignty and cybersecurity as environments become more complex.
 

What is the future direction of sovereignty?

The sovereignty boom will be important over the next two to three years, but can those with more revenue and dedication to ITO, like Atos Group and Kyndryl, survive in the long run on this new demand? After all, the wave of cybersecurity and sovereignty is acting like a life raft for ITO. One answer is to leverage growing geopolitical uncertainty to expand  consulting, but what about when that uncertainty is no longer a concern too?
 
If Atos Group and Kyndryl successfully build out larger consulting arms, how will they use them in the future? TBR believes these types of sovereign environments and heightened scrutiny of cybersecurity practices will be around for the long haul; if anything, it was a long time coming. Where Atos Group and Kyndryl may have value is providing broader C&SI engagements, such as change management with AI and cybersecurity practices on the ground, as well as integrating next-generation technologies in mission-critical environments across heavily regulated industries, such as the public sector, financial services and healthcare.
 
What does this mean for Fujitsu and CGI? TBR believes their freshly built-out sovereign and cybersecurity capabilities will enhance service quality and secure their position in consulting in Europe. If CGI and Fujitsu did scale ITO more significantly, TBR could see some added resources and capabilities eventually phased out slightly once sovereign solutions reach maturity, as the two companies will opt to stay true to their consulting roots.
 
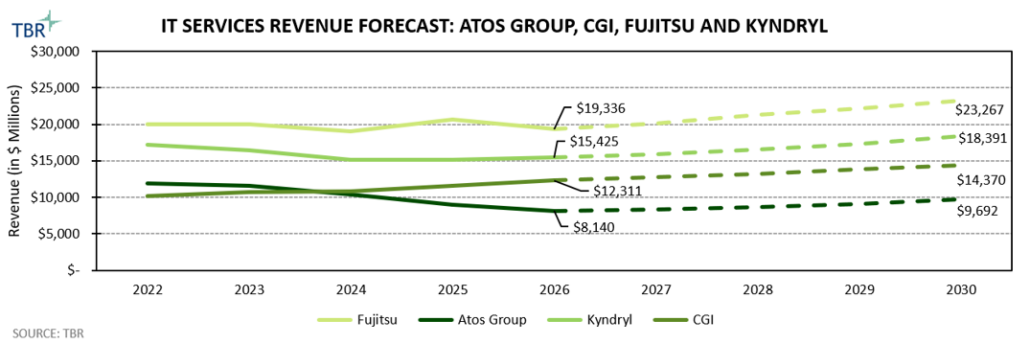
The IT Services Revenue Forecast graph below shows TBR’s total revenue projections for the four companies. Notably, CGI surpassed Atos Group in 2024, but we expect Atos Group’s revenue to rebound in 2028, with Fujitsu continuing to lead through 2030. In the second graph, we present historical data for each company, using TBR’s proprietary taxonomy, beginning in 2021 to provide a five-year view. CGI’s and Atos Group’s EMEA revenue converged from 2022 onward, and CGI’s revenue exceeded Kyndryl’s for the first time in 2025. Fujitsu’s EMEA revenue increased from $5.8 million in 2024 to $5.9 million in 2025.