ISAC will be the Next Big Thing in Telecom

On Sept. 15, Ericsson hosted industry analysts at the Boston Public Library. The company focused on industry trends and how its portfolio and partnerships intersect with them. The event covered the company’s major enterprise- and government-related portfolio areas at a high level, including private networks (Enterprise Wireless Solutions and Mission Critical Communications), network APIs (Vonage), and financial services (Ericsson Mobile Financial Services). A slate of partners and customers also participated in some of the sessions to delve deeper into market trends and how ecosystem partnerships are helping Ericsson address market needs.

Ericsson is best positioned to lead Western ISAC deployments

Among the ideas for how the telecom industry can derive new revenue from networks, integrated sensing and communication (ISAC) holds the most promise, and Ericsson is positioned to be one of the biggest beneficiaries of this trend. Regardless of who owns and controls ISAC systems (e.g., communication service providers [CSPs], government and defense entities, enterprises), more radios will be deployed in the field to monitor environments such as lower airspace for commercial and national security reasons. Governments worldwide are exploring solutions to strengthen national security and prepare for a future where lower airspace and land-based transport systems become more congested and increasingly intertwined with digital systems like autonomous vehicles.
 
TBR believes Ericsson is the best-positioned RAN vendor to support ISAC in the Western world because it remains hyperfocused on RAN innovation and holds the largest market share in mobile infrastructure when excluding China. Western governments also view Ericsson as a trusted supplier of critical technology. The company’s sprint to obtain security clearances and other certifications to support government initiatives also puts it in an advantageous position to win related deals across the public sector, not only in ISAC but in the broader domain of mission-critical communications.

Impact and Opportunities

ISAC gains momentum

ISAC is one of the most relevant technologies currently being developed in the telecom sector. ISAC essentially turns the network into a radar system, capable of generating data such as location, velocity, and elevation, and identifying moving objects. In an era where warfighting increasingly relies on drones, ISAC is being assessed by the top levels of government and military forces globally. Evidence suggests all major defense-oriented nations are at least thinking about solutions that can map and monitor lower airspace, which is where the drone threat is most acute, as drones typically evade existing radar systems.
 
CSPs have an obvious role to play in ISAC, but the question remains how and to what extent. CSPs will need a clear monetization path to commercialize ISAC at scale. Other economic models are in the running, including governments buying their own private ISAC systems separate from CSP control, though these control points will likely be co-located, at least in part, on top of commercial, terrestrial networks.
 
There may even be multiple ISAC systems operational in a given environment, one controlled by the government and/or military and one or more run by a commercial player for commercial purposes (e.g., coordinating drone package delivery or flying taxis). In each of these situations, and regardless of whether the CSP is involved in the economic structure, RAN vendors like Ericsson would stand to benefit from the deployment of these systems as they would drive additional need for radios and core products and services.
 
The beauty of ISAC for the telecom industry is that there is no need to wait for the 6G specification to become commercially available; usable ISAC solutions can already be implemented using 5G Advanced and 5G core. ISAC trials are underway, and commercial deployments are expected to begin in 2027.

ISAC will drive incremental RAN investment

ISAC can leverage existing 5G network infrastructure, particularly Massive MIMO radios, though standardized ISAC remains an emerging capability that will mature through 5G-Advanced and 6G. Existing cellular networks were primarily designed to provide terrestrial coverage, meaning their antenna patterns and network configurations are not optimized for sensing lower airspace. Use cases such as drone detection will therefore require greater elevation-domain coverage, which can be enabled through beamforming, radio and antenna configuration, and potentially hardware upgrades where existing infrastructure is insufficient. Massive MIMO is particularly well suited for ISAC because its large antenna arrays and beam-steering capabilities can improve sensing coverage, accuracy and resolution.
 
TBR expects ISAC to create an incremental RAN products and services opportunity for RAN vendors such as Ericsson as network operators add sensing software, signal processing and edge compute capabilities and optimize their networks for sensing. One of the key benefits of ISAC, however, is that network operators can reuse much of their existing infrastructure, including sites, spectrum, transport and, in some cases, radios, limiting the need for large-scale network overlays. Investment beyond the RAN will also be required for sensing control, data processing and service delivery, but the larger opportunity is likely to come from integrating the RAN-based sensing layer with defense, public safety and commercial applications that consume and act on the sensing data.

Advanced private networks still rely heavily on government funding

Success stories about what 5G can do in enterprise environments are plentiful now, but the important consideration is whether these solutions are ROI-positive for the entities they are meant to benefit. Many advanced uses of private 5G networks rely on government sponsorship to get off the ground, including grants and tax breaks. One such example is how certain enterprises in Singapore are working with the telecom industry, especially SingTel and Ericsson, to show how advanced networks can deliver superior results, as demonstrated with the National University Health System in Singapore.

6G will be iterative on top of a 5G foundation

5G New Radio and 5G core are expected to migrate seamlessly to 6G specifications once standards are ratified. Many in the industry, TBR included, believe 6G will primarily be software-based upgrades on top of a 5G radio and 5G core foundation. Yes, net-new radios and core elements will likely be required as well, but giving operators an easier glide path to adoption of new capabilities will be the best path for the industry as it will provide CSPs with a more economical way to make the transition. With that said, new spectrum bands are expected to be in play leading up to the 6G era, many of which will require new hardware. AI RAN and edge computing will also likely drive some additional CSP investment, but the question remains when this will become meaningful.

Ericsson is making progress in the defense sector

Ericsson achieved several critical certifications over the past 12 months, including a top-level security clearance in the U.S., which enables the vendor to begin playing a more significant role in the rapidly growing defense communications sector. The vendor was also selected to be involved in the U.S. government’s SHIELD program, which includes the Golden Dome initiative. Ericsson will still struggle to muscle its way into a prime contractor position against incumbent defense contractors like L3Harris, Raytheon and Lockheed Martin; a partner model with the primes is likely the best path forward to monetizing opportunities in this sector. (TBR notes that Ericsson did not mention by name in presentation materials or have any defense partners participate in this year’s Ericsson Industry Analyst Day.) Specifically, Ericsson’s products can support aspects of mission-critical communications and command and control systems, including ISAC.

FOMO may catalyze demand for certain network slices

A trend is emerging in which leading CSPs offer prioritized connectivity for a premium price. In many cases, these slices are offered as part of special events like sports games and concerts, where a certain cohort of consumers may be willing to pay extra for better quality of service (QoS) during the event.
 
TBR believes this trend aligns with the K-shaped economy, marking a departure from the best-effort-for-all connectivity model of the past. However, in the case of telecom, the idea that connectivity QoS may degrade if people are not willing to pay more could drive some level of FOMO (fear of missing out) among participants in a given situation.
 
TBR notes that FOMO is a powerful driver of user behavior in other industries, such as travel insurance, where a cohort of travelers will pay extra up front for something they may or may not actually need to have peace of mind. Network connectivity services are similar. One mechanism for CSPs is to partner with ticket distributors such as Live Nation, which also owns Ticketmaster, where ticket buyers would be prompted at the point of sale to consider buying a special connectivity package with their ticket. Insurers already offer this at scale through similar partnerships, and it has proven lucrative.

Conclusion

ISAC is emerging as a potentially significant new growth opportunity for the telecom industry, and there is no need to wait for 6G; ISAC can be implemented now with existing 5G RAN and 5G core products. Regardless of who owns ISAC systems, Ericsson would be one of the biggest beneficiaries of this trend due to its leading position in RAN and strong position in core.
 
Network slicing also holds promise for the telecom industry, with CSPs increasingly offering these capabilities, but success will depend on ecosystem partnerships and clever marketing.
The Federal IT Services Reset: Traditional Consulting Evolves to Embrace Mission Outcomes

The traditional consulting paradigm in the federal sector has been upended in the post-DOGE environment

Federal IT demand will not return to a consulting-heavy transformation cycle. Agencies remain under cost pressure as AI adoption at scale crawls from pilots to production, while spending concentrates on mission-critical modernization, cybersecurity and defense. Amid the recent chaos, is an opportunity emerging for companies offering platforms, automation, managed services and technology programs with measurable operational outcomes?
 
TBR’s Federal IT Services research includes annual profiles of Accenture’s, CGI’s and IBM’s U.S. Federal Services practices. This special report examines current trends, those companies’ strategies and recent performances, and expectations for federal fiscal year 2027 (FFY27).
 
CGI Federal enters the environment described above with the cleanest near-term story because its platforms already map to efficiency, financial management, and fraud, waste and abuse (FWA) reduction. TBR believes Accenture Federal Services (AFS) will have an upside when enterprise AI adoption and defense modernization accelerate. IBM Consulting’s U.S. federal unit has a relevant technical portfolio, but questions remain about whether the company can parlay its technology competencies into sustained contract growth. One certainty and two questions.

Federal IT investment pivots toward operational platforms and mission-ready AI while demand for traditional consulting evaporates

The federal market remains split. Civilian spending is constrained, while defense, intelligence, homeland security and selected mission-critical civilian programs are roaring. Durable opportunities stem from AI-enabled automation, cybersecurity, shared services, fraud reduction, modernization with the Department of Veterans Affairs (VA), secure cloud, and mission systems, with defense growth strongest around missile defense, AI-enabled mission systems, cybersecurity, Intelligence, Surveillance, and Reconnaissance (ISR), secure cloud-to-edge environments and software-defined modernization. That reads like a long list of fantastic growth opportunities for IT services companies.
 
Looking at recent results, CGI Federal returned to growth ahead of AFS and IBM Consulting, supported by more than $1.2 billion in 1H26 contract value and strong demand for its Momentum financial management and Sunflower asset management platforms. Lower dependence on conventional strategy and management consulting, areas targeted by DOGE, gives CGI Federal a degree of structural advantage.
 
Critically, CGI Federal is winning the right work: nearly $500 million of 1H26 awards tied to the Environmental Protection Agency, VA and General Services Administration involved Momentum, creating multiyear opportunities across hosting, licensing, operations, maintenance, upgrades and cloud optimization. CGI Federal’s AI-enabled Fraud, Waste and Abuse platform, which embeds AI in an operational platform rather than selling it as a stand-along consulting promise, also has a positive trajectory as federal AI enters a more intense phase.
 
Although this may be an oversimplification and counterexamples abound, U.S. federal agencies have begun moving beyond generic generative AI pilots and are focusing on hardened, secure, mission-specific AI platforms. As in the commercial enterprise space, data readiness, governance, cybersecurity and integration determine the depth and pace of AI adoption at scale.
 
Among the advisory-focused federal systems integrators, TBR believes AFS stands to benefit the most as this trend evolves. AFS has built the broadest AI-native alliance ecosystem among the three, leveraging relationships with OpenAI, Anthropic, Palantir, Databricks and Quantum Computing Inc. to position across the federal AI lifecycle of experimentation, application design, deployment, managed services and ongoing operations. Unsurprisingly, AFS’ alliances strategy mimics that of its parent company, which has long set the standard for ecosystem strategy.
 
Like Accenture, AFS addresses security, data quality and governance through partner orchestration rather than a proprietary stack. Databricks supports data curation; Anthropic brings secure AI; Palantir supports mission data and applications; OpenAI provides a foundation for agentic AI development and deployment. The challenge for AFS is whether the use of AI in the federal sector will remain experimental through 2027 or if AI will finally begin to scale across agencies particularly in the civil space.
 
In contrast, TBR believes CGI does not need an AI boom to continue growing in the federal sector. The company can use Google Cloud Gemini and other tools to improve design, testing, automation, security and shared-services offerings, and enhance its flagship Momentum and FWA platforms — solutions agencies already buy. IBM’s approach is more technology-led, built around watsonx, AIOps, Red Hat, hybrid cloud and defense platforms. The technology is highly relevant; the commercial proof is still catching up.

In FFY27 federal IT vendors will parlay AI capabilities into repeatable platforms, measurable outcomes and mission impact

In the defense and intelligence space, AI-enabled mission systems, missile defense, cybersecurity, ISR, secure cloud and edge computing drive federal IT spend. AFS has been deliberately trying to increase its relatively modest defense exposure (currently just 20% of AFS revenue, per TBR estimates). Garrett Berntsen’s appointment as chief AI officer is telling: His background includes leadership roles in the Department of Defense’s (DOD) data and AI organization.
 
AFS can meaningfully expand as defense AI spending accelerates, and TBR strongly believes it will. Similarly, TBR estimates roughly 30% of IBM’s federal revenue comes from DOD and intelligence accounts, and TBR believes IBM’s Digital Intelligence Suite for Defense could deepen that presence by turning secure AI capabilities into a repeatable platform. IBM has also secured a position on the Missile Defense Agency’s SHIELD program, although it has not yet received task orders as of the publishing of this report.
 
For IBM, the SHIELD program illustrates both the opportunity and the problem. The company’s AI, cybersecurity, data governance and systems integration portfolio fits future defense requirements well, but contract access must translate into actual task-order revenue before the strategic potential matters financially.
 
Echoing trends TBR sees across the commercial sector, federal technology and services buyers are consolidating work around strategic partners that can combine AI, cloud, data, cybersecurity and operations into repeatable delivery and measurable outcomes. Agencies are moving away (slowly now but accelerating soon) from labor-based consulting and toward platform-enabled managed services that reduce cost, improve security and accelerate mission execution.
 
CGI appears to be the closest vendor to that model in federal IT. Its platform-led business, contract momentum and embedded AI strategy align cleanly with agency demand for efficiency and operational continuity. AFS is rapidly transforming toward the model through alliances and will be well positioned to capture new AI-based implementation awards if agencies finally move AI into production at scale. IBM has the technology foundation, but it needs stronger commercial traction and a more visible federal ecosystem strategy.
 
In TBR’s view, in FFY27 the federal sector will not reward the providers that simply sell AI capabilities. Instead, the IT services companies that can turn AI in lower costs, stronger security, faster mission execution and measurable results will reap the benefits of this emerging growth area, stronger security, faster mission execution and measurable results. CGI is there today; AFS has the ecosystem to scale; IBM still needs to prove it can convert technology relevance into sustained federal growth.
 
For additional insights join the Oct. 8 TBR Insights Live Webinar: From Contraction to Opportunity: What’s Next for the Federal IT Market and Leading Systems Integrators?

AltitudeIQ and the Coming Disruption of AI-powered Enterprise Automation

In late August, TBR met with AltitudeIQ Founder and CEO Acyr da Luz and AltitudeIQ Board Advisor Michael Yadgar to discuss the startup’s proprietary technology, its role within the technology ecosystem, and its potential to disrupt the broader IT services, consulting and AI space. The following reflects that discussion as well as TBR’s ongoing research and analysis of SAP, IT services companies, consultancies and AI. 
 
Reducing the human effort needed to complete repetitive and low-thinking tasks ranks prominently among AI’s promises in the enterprise space. If a well-trained robot can do it, AI will do it, freeing humans for higher-value work. The reality to date, however, is that bots remain more expensive than people, and the costs of running AI continuously can be ruinous. When that begins to change, TBR expects startups like AltitudeIQ to be at the technological forefront, with business-model disruption right behind them.
 
While TBR does not rank speeds and feeds and does not measure latency or token usage, the business impacts AltitudeIQ has demonstrated with clients imply considerable changes coming for IT services companies and consultancies helping their clients adopt emerging and, maybe more significantly, mature but complex technologies, such as SAP’s S/4 HANA. In short, AltitudeIQ could help enterprises realize AI’s productivity promise while significantly upending IT services as we know it.

What AltitudeIQ is and is not

Founded less than a year ago, AltitudeIQ offers an agentic AI software solution to an age-old business problem: how can a company design, build, test and deploy enterprise applications faster? If every phase — from business process and efficiency through data migration to training and enablement — could be reduced from multiple months to weeks, even days, by deploying AI-enabled agents, enterprises could spend less time and money on consulting and IT services, keep their top IT talent engaged on niche and challenging problems, and derive more value from their ERP systems, such as SAP.
 
By tackling every phase with a combination of prebuilt skilled agents, expert-directed agents and human-led decision making, AltitudeIQ has begun proving to clients that a 30% reduction in time and expenses is possible, even in a large-scale enterprise with complex IT environments and reporting requirements, according to Luz and Yadgar. TBR notes that one key characteristic that may separate AltitudeIQ from other startups in the agentic AI space is the founder’s 20-plus years of experience as a consultant. He and the team have designed a technology to solve a business problem, rather than designing a technology solution and then looking for a business application.
 
Further, Luz and Yadgar repeatedly assured TBR that AltitudeIQ will remain a software company content to partner with services companies. As Luz commented, “Some clients are asking us to take services, and we’re inviting consulting firms to partner with us … one client asked for help with the business case and implementation, and we said, ‘OK, good, but I’m going to bring another partner.’ … I don’t want to be doing the service work there … we don’t want to go down that path … That’s strategic for us to stay on software.” In TBR’s view, this combination of a business-problem mindset and a focus on just software makes AltitudeIQ an ideal partner for IT services companies and consultancies — at least for now.
 
Speed cannot be all that an AI-enabled solution delivers, particularly for enterprise clients with substantial governance, risk and compliance (GRC) considerations. Speed must be paired with quality and trust. For every startup, proving quality and gaining trust present challenges, and AltitudeIQ has approached one by upending the established order and the other by following a tried-and-true strategy.
 
Luz and Yadgar relayed an experience with an enterprise client’s IT team: “The technical people were very skeptical,” according to Luz. But AltitudeIQ took on a problem that had festered for nine months and solved it in two and a half hours. While not every problem will be as easy to solve, this example shows AltitudeIQ’s mindset: that its work can withstand scrutiny and testing and it can handle enterprise clients’ most complex problems. Partnering with global brands such as Big Four firms, global systems integrators (GSIs), and large management consultancies also conveys AltitudeIQ’s quality to clients.
 
Consultancies and IT services companies repeatedly tout trust as part of their value proposition. For example, Big Four clients expect any startup a Big Four firm introduces to be thoroughly vetted, which builds trust. Additionally, close partnerships with these trusted brands help transfer some of that trust to AltitudeIQ.
 
AltitudeIQ does not rely on strategic alliances and faith in its technology. The company upends the established order — and reinforces quality and trust — through documentation, governance and reporting. Rather than generating documentation as a matter of course during software development and rollout, Luz explained, “You generate documentation just in time, fully updated when you need it … you go and generate because the agents can code and do the testing and everything for you. Now I need something for audit or something for validation. Now we generate the documents you need.” Are clients ready for this? Not yet, in Luz’s view, but they will come to appreciate it.

The disruptive impact of AltitudeIQ and companies like it

AltitudeIQ’s success could be hugely disruptive to the traditional consulting and IT services landscape. Drastically shortened timelines for implementation threaten system integrators’ traditional commercial models. Enterprises will rethink how they deploy and update their ERP systems and what is required for GRC, potentially reducing the need for large offshore staff dedicated to managed services around IT stacks.
 
When generative AI burst onto the scene, we read about (and maybe predicted a little bit ourselves) this kind of disruption to consulting and IT services, but adoption at scale by enterprise lagged well behind the hype. And IT services companies and consultancies continued to provide value through change management, GRC, and the management of increased complexity wrought by AI adoption. AltitudeIQ’s offerings, along with similar products in the market, significantly accelerate the time it takes to adopt and manage large ERP systems. However, this could create challenges for the very partners that AltitudeIQ currently collaborates with, at least in the short term. These companies and firms may need to adjust their own value propositions, technologies and capabilities in response.
 
The wild card remains change. Enterprise will likely be slow to fully adopt agents, or at least fully rely on them, for compliance and reporting. Typically, startups do not handle or consider change management, relying on consulting partners to guide clients, which can be another potential brake on disruptive adoption. But in the current AI age, even cultural and structural impediments to change seem to be overwhelmed by the need for speed. Yadgar noted, “I think for people that have got a problem today, the take-up is much faster. They go, ‘That’s my problem today. How can I use [AltitudeIQ’s software] tomorrow?’”
 
As AltitudeIQ scales, knowledge management will present another challenge. Currently, IT services companies and consultancies bring AltitudeIQ into their client meetings. If those opportunities scale quickly, will these consulting and SI partners be able to tell the AltitudeIQ story, from both a technology and a business perspective, without AltitudeIQ in the room?
 
White labeling and reselling make sense while AltitudeIQ remains in startup mode, but will GSIs and consultancies consistently consider AltitudeIQ IP, especially when other similar tech stacks are available? Alternatively, the AltitudeIQ IP may be so good that SAP or another tech giant might buy it, which could be the best path forward for a company operating in a paradoxical environment.
 
One more alternative path: small and midsize businesses. TBR has heard repeatedly in 2026 that GSIs and large consultancies have been investing in their SMB practices and offerings.
 
In TBR’s view, GSIs and global consultancies will need all the proven IP they can get to make it worthwhile for SMB clients to listen. Absent productization of services, the GSIs will not be able to meet SMB budgets. AltitudeIQ seems to have the right pricing and go-to-market model that will not interfere with GSIs’ SMB plans, should AltitudeIQ opt for hundreds of small clients rather than a dozen large ones? One thousand SMB clients using off-the-shelf AltitudeIQ IP? Or 10 Fortune 100 clients demanding customization, leading AltitudeIQ to expand into more services, against its strategic intentions? Knowledge management, client selection and selling out are all business-model challenges for AltitudeIQ, particularly as the company continues to grow.

Conclusion

TBR does not evaluate technology solutions; we evaluate businesses. While small relative to the companies TBR reports on quarterly, AltitudeIQ receives investment support from established technology investors with track records of building scaled businesses. TBR typically does not evaluate startups, but AltitudeIQ’s consulting heritage, relatively quick partnerships with leading IT services companies and consulting firms, and seamless fit within an exceptionally well-established technology environment (the vast SAP landscape) led TBR to take a closer look, and we will keep AltitudeIQ on our radar as 2026 winds down and return to hear more of their story in 2027.

Could Responsible AI Spark Transformative Change at HCLTech?

In mid-August, TBR met with Heather Domin, HCLTech’s vice president and head of Office of Responsible AI and Governance, and Grace Davin, Responsible AI and Governance Thought Leadership and Enablement leader, to discuss HCLTech’s Responsible AI Advisory Services practice. The following reflects that conversation as well as TBR’s ongoing analysis of HCLTech, the IT services ecosystem, AI and disruptions across business models in the technology space.

 
HCLTech’s strengths lie in its engineering DNA; entrenched and well-managed client relationships; and extensive alliance partnerships, which include critical technology players and even HCLTech competitors. Playing to those strengths has been one element separating HCLTech from IT services peers in the last few years, especially with respect to profitability. With a suite of AI Advisory Services, the company continues to follow its proven strategy: focus on core values, deliver relentlessly, partner smartly, and expand within an existing client base.
 
Responsible AI, a critical subset of AI Advisory Services, could serve as a strategic enabler of HCLTech’s market leadership ambitions, elevating its market stature and strategic relevance with clients, peers and ecosystem partners.

Responsible AI: The basics

AI Advisory Services is aligned with HCLTech’s overall organization and strategy including partnerships across technology companies, industry organizations, nongovernmental organizations and governments. In Domin’s view, staying current with the fast-changing AI landscape requires partnering broadly as well as putting HCLTech through the rigors of leading AI, technology and organizational certifications. Domin noted HCLTech’s partnerships with Microsoft and IBM, as well as a growing collaboration with the Massachusetts Institute of Technology.
 
HCLTech’s core client value proposition combines Responsible AI governance with large-scale engineering and transformation delivery. Unlike niche governance or AI red-teaming providers, HCLTech’s AI advisory capabilities span AI red teaming, AI governance, enterprise strategy, agentic engineering, and road-mapping from prototype through production. The company brings technical talent, local regulatory knowledge, customization by industry and geography, and the ability to embed governance into major AI programs rather than treating it as a stand-alone compliance exercise.
 
According to Domin, HCLTech has seen increasing demand for AI advisory services from clients, particularly in financial services, healthcare, and energy & manufacturing, all areas that face significant regulatory challenges. HCLTech has developed expertise in addressing governance, risk and compliance (GRC) issues for clients in part by hiring talent from legacy GRC firms and by recruiting professionals with backgrounds combining legal, compliance and AI experience. In TBR’s view, HCLTech’s decision to explicitly call out Regulatory Services as a component of AI Advisory Services provides a subtle but significant differentiator when contrasting HCLTech with its closest IT services peers.
 
HCLTech bakes Responsible AI into every element in the AI Advisory Services suite, as well as across the broader set of HCLTech’s AI offerings, such as AI Force (see TBR’s assessment from late 2024). Domin acknowledged that Responsible AI should be at the forefront of any engagement with an AI component and not, like change management traditionally, left to the end of the engagement process.

Responsible AI: The nuance

When discussing whether HCLTech’s Responsible AI services offering allowed the company to interact with decision makers beyond the usual CIO clients, Domin noted that organizations have different approaches to “placing the responsible AI responsibilities … sometimes they put it in the technology office, sometimes in the CIO, sometimes it’s in the chief risk officer’s office, and so [CIOs will] bring in the right people.”
 
These changing roles and responsibilities help expand HCLTech’s influence and footprint within a client. Domin added that some “big companies that we work with already have pretty well-established [AI and tech] broad capabilities. What they need is to understand how to deploy a specific AI deployment with the right guardrails integrated. So it just depends on the company. We might not even need to go to that other buyer, but in some cases we do.” In TBR’s view, expanding HCLTech’s role by providing Responsible AI services will undoubtedly bolster client retention and help prove the company’s overall value.
 
In multiple client use cases presented by Domin, HCLTech’s AI Advisory Services practice essentially solved complex problems driven by a lack of responsible AI practices or guardrails and emerging technology deployments. For example, one client’s use of GitHub Copilot had returned underwhelming results and created unwanted risks, providing an opening to use nearly the full suite of HCLTech’s AI services. In TBR’s view, these brownfield opportunities will likely remain plentiful as hype around AI’s promise coupled with fears of being left behind outpace responsible approaches to AI deployments.
 
TBR noted Domin and HCLTech’s emphasis on governance, risk, and compliance, as well as the operational aspects of AI and not the specific technology itself (discussion touched on broader aspects beyond the common technology aspects such as which large language model to choose, vibe coding, retrieval-augmented generation, or token consumption). Every IT services company does tech. Not every company understands and delivers on broader governance and risk management.

What Responsible AI really means for HCLTech

Domin discussed HCLTech’s customer-zero story and how the Responsible AI team participated in the firm’s ongoing internal AI deployment, including ISO 42001 certification and an AI ethics board. She added that, “some of our experience around our own tooling, it’s been useful. Like where clients are deploying similar tools or things, we’ll say, ‘Oh yeah, but our team is doing that internally. Go talk to them.’ And so yes, [customer zero] is very much a core integral part of what we do.”
 
In TBR’s view, HCLTech’s customer-zero story around Responsible AI could be part of a catalyst for change within the company. Not only will the customer-zero story resonate with clients and with HCLTech’s technology and ecosystem partners, but employees will also be able to see the company’s value to clients in a different way.
 
Domin’s presentation and the discussion with TBR included frequent mentions of “board-level narratives” and deliverables from HCLTech ready for “audit committee review,” all wrapped around the Responsible AI and AI Advisory Services offerings. TBR had not previously considered that HCLTech’s value proposition includes board-level contributions, except for highly specific, technology-centric issues, such as large-scale IT implementations or business-model-changing AI deployments at scale.
 
Domin subtly suggested the company’s Responsible AI professionals would consult consistently at the board and audit committee levels, bringing HCLTech’s brand repeatedly into that environment in a different way.
 
Notably, Domin commented on a “cultural transformation of our teams” as part of the positive effects of internal AI adoption at HCLTech. Continued adoption and cultural transformation could help the company position itself as a different kind of partner to boards and C-Suites than other IT services companies. That shift would likely strengthen HCLTech’s standing as a strategic advisor to clients and ecosystem partners, creating opportunities for additional services engagements beyond Responsible AI.

Grant Thornton Expands Its Oracle Practice Through Leadership, Industry Expertise and AI

TBR recently spoke with Brandon Johnson, Oracle Advisory Leader at Grant Thornton, about the firm’s growing Oracle practice, his experience prior to joining Grant Thornton, and his expectations for Oracle and Grant Thornton over the next few years. The following reflects that discussion as well as TBR’s ongoing analysis of both companies, their competitors and peers, and trends across the entire technology landscape.

 
TBR believes Grant Thornton has built a differentiated Oracle practice around senior leadership, direct field access, and focused industry investment, all centered on midmarket clients. Grant Thornton has Oracle breadth without bloat, connecting finance, human capital management (HCM) and supply chain with tax, risk, cyber and industry advisory while keeping experienced leaders close to the work.
 
Existing demand supports growth, and, notably, Oracle generates about half of Grant Thornton’s leads, while Grant Thornton creates the remaining pipeline internally, reflecting the depth of the two companies’ relationship. Scale remains the biggest challenge, with Johnson admitting the bench needs strategic growth and a better balance of offshore and nearshore talent.
 
Despite this constraint, TBR expects Grant Thornton’s annual Oracle practice revenue to grow in the high teens to low 20% in the near term, potentially higher if Grant Thornton institutionalizes more of a relationship-led practice through standardized delivery, a broader talent pipeline, and reusable AI offerings with defined governance and outcome measures.
 
In short, Grant Thornton recruited the right leadership and developed tight relationships, and now it must execute on Oracle’s platform changes plus client demand.

Leadership, industry focus and co-selling have deepened the Oracle alliance

Grant Thornton hired Johnson, a 25-plus-year Accenture veteran, where he had successfully built a substantial Oracle business and established strong relationships with Oracle’s sales, product and alliance teams. He has been joined by additional experienced professionals specializing in Oracle HCM, finance, supply chain and enterprise transformation.
 
In TBR’s assessment, Grant Thornton gained unusually broad and deep access to Oracle for a firm of its relative size, and its long-standing experience working with Oracle provides it with the discipline and confidence to treat Oracle’s consulting practice as a delivery partner rather than a competitor.
 
For decades, professional services firms, particularly the Big Four, have maintained strained — at best — relationships with the consulting arms of software giants such as SAP, Microsoft and Oracle. In contrast, according to Johnson and Grant Thornton Chief Marketing Officer David Clarke, Grant Thornton enjoys a more mature, cooperative understanding of different consulting opportunities and roles.
 
Grant Thornton, in their view, leads transformation and draws on Oracle for specialized infrastructure and product depth. Of course, the age-old challenge of converting personal access and relationships into consistent field enablement and referrals remains.
 
According to Johnson, Grant Thornton’s Oracle practice concentrates on financial services, healthcare, hospitality and travel, professional services, transportation and logistics, with new investments in energy, utilities, oil and gas, and consumer sectors.
 
TBR’s research has consistently shown that concentrated industry specialization, rather than serving all industries, yields faster, more sustained revenue growth. Technology vendors increasingly reward partners that combine industry talent, subindustry offerings and reusable IP; broad but shallow coverage carries less value than proven depth in a limited set of markets.
 
Like many consultancies, Grant Thornton creates demand for Oracle through a presales team that demonstrates the technology, joint go-to-market campaigns and introductions to existing Grant Thornton clients.
 
Not surprisingly, Oracle, according to Clarke, promotes Grant Thornton in partner forums. More surprising, Oracle generates about half of Grant Thornton’s Oracle pipeline, reinforcing a shift from simple referral flow to co-selling.
 
TBR believes a technology company’s ability to explain a consulting partner’s value and tell that consultancy’s story remains the most critical indicator of the current depth and long-term potential of a tech vendor-consultancy alliance. A tech vendor must be able to effectively communicate a consultancy’s story to generate significant pipeline, and clearly, Oracle is doing this well for Grant Thornton.
 
Further cementing the alliance, Grant Thornton’s relatively early participation in Oracle’s AI Agent Studio gives the firm a foothold in the transformation layer between applications and infrastructure, enabling the firm to use agents to connect data, automate processes and coordinate decisions across Oracle and non-Oracle systems.
 
Oracle’s Fusion Agentic Applications expand that opportunity rather than reduce services demand. Clients still need integration, controls, process redesign, data readiness and change management, and Grant Thornton should be able to tie each deployment to measurable gains in close cycles, workforce operations, procurement, service or supply chain.

Grant Thornton’s Oracle sweet spot: Complex midmarket transformations

Grant Thornton’s ideal clients share a few basic characteristics: large enough to have outgrown boutique consultancies and IT services companies; small enough to neither need nor want to pay the higher prices of a Big Four firm or global systems integrator; and experiencing rapid growth fueled by acquisitions, carve-outs and increased technology investments while contending with fragmented IT systems and business model disruptions.

How does Grant Thornton marry its client base and Oracle’s technology?

  • Integrated Fusion transformations: Grant Thornton positions HCM with finance and supply chain; it reported to TBR that roughly 70% of its Oracle pipeline includes HCM packaged into a broader bundle. Oracle’s common application and data architecture enables the firm to frame workforce, financial and operational change as a single program.
  • Private equity (PE) carve-outs and post-acquisition integrations: Grant Thornton combines PE relationships and preconfigured designs to establish finance, consolidation, HR and operational systems quickly, especially when a portfolio company must separate from a parent or prepare for another transaction. Undoubtedly, Grant Thornton brings its customer-zero experience to these opportunities.
  • Industry-specific transformations: In the healthcare, financial services, transportation, hospitality and energy verticals, Grant Thornton can combine Oracle with regulatory, tax, risk, cyber and operating expertise. Grant Thornton is not unique, but by staying focused on a handful of industries, the firm’s expertise sets it apart from its peers. TBR notes that even if the industry transformations are not unique among services companies, there is a level of differentiation among tech partners. In our opinion, Oracle is one of the very few SaaS vendors that offer fully prepackaged industry applications, giving firms like Grant Thornton opportunities to build around these applications, helping them lead with business discussions and work backward into horizontal finance and HR transformations.
  • AI-enabled finance and enterprise transformation: For Grant Thornton’s clients, Oracle agents can improve finance, HR, procurement, supply chain and service workflows, but only when Grant Thornton pairs the deployments with process redesign, governance, controls, data readiness and workforce change.
  • Alternatives to large integrators: According to Johnson and Clarke, Grant Thornton’s senior-level attention and practical delivery style appeal to buyers concerned about junior staffing, change orders or standardized playbooks. Sustaining that advantage may require Grant Thornton to make its capacity model as credible as its relationship model.

In TBR’s view, Grant Thornton will likely avoid infrastructure-heavy Oracle Cloud Infrastructure (OCI) programs, complex database modernization and very large global transformations until it builds deeper capabilities — though these may be necessary as OCI matures and continues to underpin the broader platform and applications portfolio.
 
OCI will also become more essential to the One Oracle positioning and sales strategy Oracle will increasingly emphasize with its partners. Until then, Grant Thornton can own the transformation agenda with its clients from the apps layer and continue developing its deep relationship with Oracle without overstating its full-stack depth.

Capacity, field awareness and technology depth will set the ceiling

Talent remains the most pressing constraint. With almost no Oracle bench, each large win for Grant Thornton creates staffing pressure, even as the firm continues building a talent base in India and recruiting top-flight nearshore talent as well as considers investing in Philippines-based capacity ahead of demand, all without weakening the firm’s promise to lead every delivery with senior, experienced professionals.
 
Compounding the talent shortage, Oracle field awareness of Grant Thornton’s strengths remains uneven. Executive access opens opportunities, but scale requires a formal enablement system that gives sellers concise guidance on target clients, industry plays, credentials, reference architectures, available capacity, and reasons to select Grant Thornton. The firm could also develop more depth across analytics, data and OCI.
 
Although becoming an infrastructure outsourcer would not fit Grant Thornton’s strategy or brand, strengthening OCI architecture, integration, security and data governance would prove more credible ownership of the transformation layer.
 
To further differentiate from peers, Grant Thornton could assign ownership, governance, version control and performance metrics to its own accelerators and link each asset to faster deployment or better client outcomes. Those metrics could also be a catalyst for disruption of the commercial model, should Grant Thornton and its clients together see benefits in fixed-fee and/or value-led commercial structures.
 
In TBR’s view, consulting commercial models have begun to evolve rapidly toward explicitly tying fees to adoption, productivity, transaction speed, working capital, workforce efficiency and/or financial close improvement. Grant Thornton’s Oracle practice could be an internal catalyst or accelerator for that change.

Productize, scale, prioritize, invest and attach

Leadership, client demand, alliance access and proven delivery competency give Grant Thornton the foundation to make its Oracle practice one of its fastest-growing technology businesses. With C-Suite-to-field-level relationships that run deeper than market awareness, the practice has room to take market share before larger competitors react.
 
Adding capacity, converting beta AI work into marketable solutions, proving industry plays, and expanding Oracle-originated opportunities could all help Grant Thornton when it comes to hiring, delivery, and field awareness.”
 
TBR believes Grant Thornton will likely accelerate its growth and increase its relevance to Oracle and shared clients by:

  • Productizing a small set of repeatable offerings in Oracle’s AI Agent Studio, including financial close, procurement, HR service delivery (HRSD), workforce planning and supply-chain, through ideally defined deployment methods and outcome metrics
  • Scaling through delivery pods, which will preserve senior client leadership while expanding offshore and nearshore leverage across the entire Oracle stack
  • Prioritizing sectors where Oracle commitment, Grant Thornton relationships and midmarket demand overlap, especially financial services, healthcare, energy, transportation and logistics, and hospitality
  • Investing in OCI architecture, Oracle Integration Cloud, data governance, security and cross-platform orchestration rather than commoditized infrastructure
  • Attaching optimization, managed services, agent governance and adoption support to implementations while providing recurring revenues

To bring the greatest value to its clients and to Oracle, Grant Thornton does not need scale parity with the largest Oracle partners — a point Johnson and Clarke made repeatedly to TBR. Instead, the firm will institutionalize its alliance access, focus its industry model and bring measurable results to its midmarket  clients. Capacity, repeatability and field execution will help Grant Thornton punch well above its weight.

Lenovo’s AI-native Support Services Transformation: From Reactive Support to Intelligent Service Orchestration

Enterprises are under pressure to do more with less. Infrastructure estates are becoming more complex, user expectations are rising and support organizations are being asked to deliver faster, more personalized and more consistent support across varying geographies, device types and service channels. TBR’s 2026 Infrastructure Strategy survey reflects this operational burden, with 66% of respondents agreeing or strongly agreeing that most of their team’s time is spent trying to keep up with day-to-day tasks. Additionally, according to respondents, shortages of skilled IT staff remain a major compounding constraint. The result is a widening gap between what customers expect from support services and what traditional operating models can consistently deliver.

AMD Enters the Execution Phase of its Full-stack AI Strategy

Advancing AI 2026 showed that AMD has assembled the architecture and road map required to compete at rack scale. Helios connects the company’s GPUs, CPUs, networking and software into a system-level platform, while expanding partnerships with Microsoft, OpenAI, Anthropic and Meta provide credible paths to large deployments. ROCm.ai gives AMD a new way to reduce the engineering effort required to bring up and optimize applications on Instinct GPUs. Agentic workloads also expand the AI-driven opportunity for EPYC beyond its role as a host CPU for accelerators, allowing AMD to address the agent sandboxes, applications, databases and data services surrounding GPU inference.

Global Analyst Summit 2026: Value Creation Through Operating Model Transformation  

As consulting continues to evolve due to AI’s influence on business models and day-to-day operations across enterprises, EY’s leaders discussed how the firm is adapting its approach to guide clients through uncertainty and increased speed of change, and introduced featured clients, giving them an opportunity to share their experiences. The client stories emphasized the speed at which they need to navigate market changes and their desire to work with a long-term partner such as EY to guide the transformation as well as to create an ecosystem of vendors that support their end goals. The notion of value was consistent throughout the event, as the firm seeks to reconfirm its positioning in the consulting space despite ongoing market uncertainty about consulting’s future relevance.

Are Hyperscalers Really Competing for Services Revenue? 

TBR has consistently highlighted hyperscalers’ professional services units, despite their relatively small revenue streams, as potentially credible threats to IT services companies.  Hyperscalers do not intend to displace global system integrators (GSIs) in consulting or managed services, but their growing services capabilities create more margin pressure for (and anxiety among) the GSIs each quarter. This report examines where hyperscalers’ professional services units overlap with GSIs’ and how their roles continue to evolve. We begin by comparing the companies’ services operating models.

How hyperscalers work alone

Among the hyperscalers, Amazon Web Services (AWS), Google and Microsoft have their own services units, with AWS having the highest cloud professional services revenue and being the most vocal about its offerings. AWS ProServe (Professional Services) and Amazon Managed Services take tailored approaches and have customer-forward strategies. AWS provides ProServe offerings on AWS Marketplace, making it easier for account teams and customers to procure consulting alongside cloud products.
 
At the end of 2025, AWS launched the Professional Services Delivery Agent, which changed the workflow for AWS and its clients, making agents the first step, not a consultant-led pilot. Now agents can perform architecture validation, migration planning, code generation and documentation while consultants focus on customer-specific decisions. In comparison, Google Cloud Consulting introduced packaged engagements around new technologies, such as AI Readiness and Agent Launchpad, to help customers reach production quickly before partners scale the deployments.
 
Microsoft’s professional services practice, which once focused on paid implementation, is moving toward adoption and customer success through services like FastTrack, Unified, and Cloud Solution architects. The introduction of Microsoft Frontier Company could change the dynamic by giving the company a more direct role in helping clients design, deploy and scale agentic AI solutions. The model creates a more comprehensive delivery motion that may resemble AWS’ and Google Cloud’s by taking a more formalized approach to technology, engineering support and consulting around emerging AI workloads.


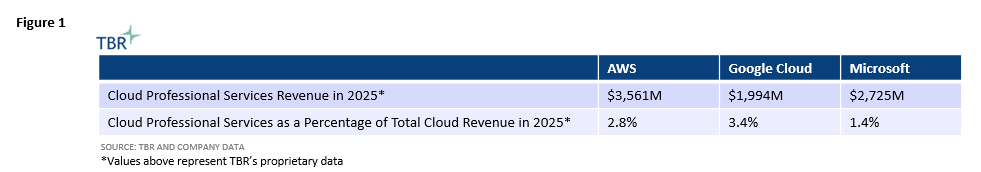
Figure 1 contains TBR’s proprietary data and includes estimates of professional services revenue developed over years of experience covering these companies and the broader IT services market. Microsoft receives the smallest share of revenue from cloud professional services, and this may be part of why the company rebranded its former Microsoft Consulting Services to be included as part of Microsoft Industry Solutions and the broader Microsoft Professional Services unit, which is more closely aligned with the client-facing brands AWS ProServe and Google Cloud Consulting. Microsoft intends to gain higher margins in consulting-related work as part of its broader strategy to become AI-first.
 
TBR believes Microsoft may be trying to emulate margin leader AWS’ approach in its professional service business. Compared to five years ago, Microsoft’s and Google Cloud’s professional services revenue has been declining as a percentage of total cloud sales. Yet, many vendors are increasingly giving away managed services as a value-add.
 
As AI matures and repeatable solutions become more attainable, AWS may borrow Microsoft’s and Google Cloud’s more platform-based approach. In addition, repeatable outcomes will make services partners even more important, and they can focus on ecosystem orchestration. Services orchestration of go-to-market motions incorporating emerging solutions indicates that interconnected revenue is rising. Google Cloud saw a 9x combined increase in seats sold with partners and in the number of partners using the application internally in 1Q26. On the GSI side, TBR believes hyperscaler partnerships will become more important and account for a larger share of revenue, as described in TBR’s 1Q26 Accenture report, for example.

Where is the threat to services partners?

Hyperscalers’ services revenue is increasing much more year-to-year than GSIs’. Each of the three hyperscalers’ professional services revenue grew by more than 10% from 2024 to 2025. TBR believes this is due in part to adding services to existing and emerging product lines. Hyperscalers want to ensure customer satisfaction, since it is their AI platform and software on the line, while GSIs remain technology agnostic as their measure of client satisfaction comes from their own services and not the technology products or platforms delivered by the hyperscalers. In addition, hyperscalers also want to obtain more consumption usage around AI.
 
TBR believes GSIs may be losing ground around adoption and solution-specific implementation engagements. TBR’s Cloud Professional Services Market Forecast 2025-2030, which focuses on a GSI perspective, predicts that hyperscalers “can influence not only how services are delivered but also how outcomes are achieved, strengthening their role in driving client success and increasing their share of the value chain.”
 
Typically, GSIs are more instrumental in broader transformation and change management engagements that require greater scale and complexity. TBR does not expect these areas of influence to change anytime soon. As discussed in TBR’s 1Q26 Cloud Go-to-market Benchmark, “As [cloud] portfolios shift toward consumption-based and modular pricing, [services] partners play a critical role in driving adoption, expansion and usage discipline, which directly influences lifetime value even when the initial transaction is small.”
 
In turn, hyperscalers are increasingly relying on GSIs’ large benches. As we also noted in the benchmark, “many AI and platform revenues are usage-based or deferred, while partner services revenue is front-loaded. [Cloud] vendors use incentives to bridge this timing mismatch and keep partners economically engaged even when vendor revenue recognition lags. Essentially, incentives are replacing guaranteed margins, enabling [cloud] vendors to steer partners’ behavior without permanently increasing the ecosystem’s costs, which would happen if they continually added headcount.”
 
Hyperscalers’ growing influence is affecting which services GSIs offer. Each new frontier model and agent release promises new, exciting potential outcomes across business workflows, security measures and applications. Yet it is up to GSIs to ensure all technology layers are prepared for AI, beyond what hyperscalers’ professional services teams offer. Hyperscalers are more interested in developing advanced solutions and earning more consumption-based revenue.

How are cloud professional services evolving on their own?

Do hyperscalers and GSIs differ in their delivery approaches? Hyperscalers may have more depth in platform-enabled delivery, given their closer proximity to innovation and heavier IP assets. Hyperscalers are not headcount-heavy and thus are motivated to keep headcount in check. AWS’ Professional Services organization is adding AI agents internally, including a Professional Services Delivery Agent, to speed consulting work and reduce delivery costs. More broadly, GSIs are an entry point for multiparty orchestration when clients need packaged repeatable offerings across cloud, services, AI-native and hardware ecosystems. We expect cloud-partner-backed revenue to increase as a share of overall revenue over the second half of the decade. However, multiparty orchestration creates competition for margins. A strong partnership means all parties need to be upfront about pricing expectations and about which engagements are best for each point of contact, the latter of which TBR believes hyperscalers and services vendors are already addressing.
 
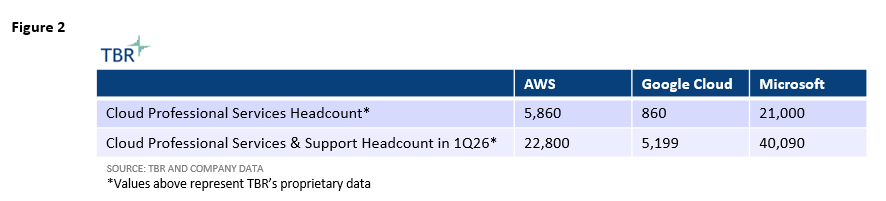
Hyperscalers want to be the first choice of technology providers for basic migration. As such, the three companies are focusing on providing consulting with designated solutions and more defined frameworks. Alongside strong alliance partners, repeatable solutions help hyperscalers keep consistent professional services despite some recent increases in cloud professional services revenue. For example, Google Cloud’s cloud professional services revenue rose an estimated 26.7% from 2024 to 2025, but the company’s professional services headcount grew an estimated 6% year-to-year from 4Q24 to 4Q25. The conservative headcount growth is indicative of hyperscalers staying true to their nature and not becoming a services business. Google Cloud, which has significantly lower headcount numbers in its professional services unit comparable to peers, may increase hiring or, at the very least, redirect resources to make services headcount more accommodating for effective AI deployment.
 
Forward-deployed engineers (FDEs) are changing the conversation around services headcount. As the IT market scrambles to accommodate growing client demand for ROI, hyperscalers are introducing FDEs. These professionals are being deployed alongside GSIs’ teams and are gaining headlines, but a deeper look suggests these roles previously existed in some capacity. The FDE model is less a clean break from prior services roles and more of a product- and adoption-oriented version of technical architecture support. FDEs share similarities with systems architects in that both sit close to the client and translate platform capabilities into workable solutions, but FDEs are more tightly linked to implementation and iteration as AI use cases move into production. One example of this is Avanade, the joint venture between Microsoft and Accenture.
 
The two companies are deploying FDEs together, with a focus on Microsoft’s Frontier Suite. As described in TBR’s 1Q26 Microsoft Cloud report, “The announcement is important because the FDE model, while made prominent by Palantir, has historically been less common among software vendors that prefer more scalable and margin-accretive delivery models. FDEs are expensive because they place technical resources close to the customer, but that proximity becomes more valuable as AI moves from experimentation into mission-critical workflows that require customization, governance and fault tolerance.” Hyperscalers are rebranding existing solutions to highlight their capabilities.
 
In the newest example, Microsoft has launched the Microsoft Frontier Company and announced a $2.5 billion investment. The company will “embed” 6,000 professionals to design and implement AI solutions, suggesting a more services-forward approach to clients, perhaps similar to AWS’. Although FDEs and related professionals are important and are likely to expand in some capacity, especially in the short term, as technical expertise is necessary for enterprises navigating AI transformation, we believe the build-out will be confined to when AI solutions begin to reach maturity. For now, hyperscalers’ professional services units will stay in their lane, focusing on how their solutions are best built and deployed, leaving the other noise, such as change management and ecosystem orchestration, to the GSIs.


PwC India Moves From a Growth Market Story to an AI-enabled Execution Engine

Trust, AI and impact shift from event themes to integral parts of the operating model

Two years after PwC India used its 2024 analyst event to emphasize India’s strategic importance as a growth market, the firm has returned with a more mature, execution-oriented message. India is no longer simply a promising geography for PwC; it is becoming a core engine for AI-enabled consulting, technology transformation, managed services, global delivery, Global Capability Centers (GCCs), support and emerging-market expansion.
 
PwC India Analyst Summit 2026’s tagline themes — trust, AI and impact — could have easily become broad consulting slogans. Instead, PwC India grounded them in client examples spanning cybersecurity, privacy, SAP, Oracle, data transformation, AI platforms, consumer growth, steel manufacturing, GCCs and public sector digital infrastructure. The result was a clearer view of how PwC India wants to compete: not by selling AI experiments or strategy road maps alone, but by combining technology partnerships, industry knowledge, delivery scale and outcome-focused accountability.
 
PwC India’s 2026 story reflects a more ambitious role within the global PwC network. The firm continues to benefit from India’s macroeconomic growth, client maturity, GCC expansion and technology talent base. But PwC India’s leaders also described a more deliberate operating model built around global integration, AI-native delivery, upskilling, expansion into emerging markets, lower-cost delivery and a stronger managed services business. In TBR’s view, PwC India is positioning itself as both a high-growth domestic consulting business and an increasingly important global transformation change catalyst for PwC.

PwC India’s strategy is shifting from growth participation to capability leadership

PwC India Chair Sanjeev Krishan framed the broader opportunity in India around economic resilience, entrepreneurship, technology adoption, manufacturing growth, the importance of services and the need for trustworthy, inclusive progress. He also described PwC India’s strategic priorities through the lens of PwC’s Vision 2030 agenda. Five priorities stood out: upskilling PwC’s people; becoming more AI-native; expanding into emerging Indian markets through the Kal Ka Bharat program; lowering delivery costs through AI and delivery industrialization; and investing more deeply in operate-led services. These priorities suggest PwC India is not merely adding AI to existing offerings but is rethinking talent, delivery economics, geographic reach and post-transformation operating models.
 
Advisory Leader Dinesh Arora expanded on that message, focusing on client concerns including geopolitical risk, AI uncertainty, cyber risk and the increased importance of trust. He highlighted that PwC India’s approach emphasizes agility, speed, AI democratization, AI-enabled delivery, industry-specific AI solutions, startup collaboration and outcome-linked commercial models. The discussion about outcome-based pricing was particularly important. Arora indicated that more large proposals now include client questions about PwC’s “skin in the game,” and he suggested that outcome-linked work could become a much larger share of the business over the next few years, aligning with the broader direction of consulting where clients want measurable value, not simply transformation activities.
 
Arora also emphasized PwC’s globally integrated consulting model, under which offerings, methodologies, tools and teams are increasingly shared across member firms. For PwC India, this matters in two ways. First, it gives India access to global credentials, methods and teams. Second, it positions India-based talent as a larger delivery base for global clients, particularly as remote and distributed consulting delivery becomes more accepted.

Palantir partnership gives PwC India (and potentially PwC as a whole) a sharper enterprise AI story

A panel discussion featuring PwC, Palantir and a joint insurance client was one of the most strategically significant sessions at the 2026 summit. It shifted PwC’s AI story from a generic generative AI (GenAI) discussion to the more challenging enterprise realities of data integration, governance, traceability, sovereignty, observability and operating model change.
 
The client described Palantir Foundry as a long-standing strategic platform, initially used for analytics and increasingly central to AI adoption and data management. The client is moving from a central data warehouse to a more business-owned data integration model built on Palantir Foundry. The scale is significant: roughly 100 source systems and double-digit terabytes of data are being moved into a new operating environment.
 
The client highlighted PwC’s data engineering, architecture and delivery expertise. PwC India’s role is particularly relevant as the client has a major GCC presence in Bengaluru, allowing PwC India teams to work closely with the client’s local and global stakeholders.
 
Further, Palantir executives emphasized the company’s strategic relationship with PwC in key markets and described PwC as a partner that brings enterprise access, cultural fit, domain experience and engineering scale. Additionally, Palantir positioned India as a critical talent pool and force multiplier, especially as global clients seek to use GCCs as centers of transformation rather than support.
 
In TBR’s view, the Palantir partnership gives PwC India a more differentiated narrative for its enterprise AI platform. Many consulting firms talk about AI strategy, AI governance and GenAI use cases. Few can combine a high-profile AI and data platform, global client transformation, regulated-industry trust requirements, and India-based engineering talent into a single story, especially when the message is amplified through a key technology partner. PwC’s opportunity will be to turn this partnership from a select marquee engagement into a repeatable global growth engine as the firm relies on its dedicated Palantir Foundry team and leans on similar use cases where PwC provides GCC services to two to three other large global clients.

Client stories highlight PwC’s evolving business plus technology operating and delivery model

During the event, PwC hosted 11 client use-case panel discussions. While each highlighted a key aspect of the firm’s evolving value proposition, some really brought the story home.
 
A pharma client’s SAP transformation was among the most compelling client stories as it demonstrated PwC’s multidisciplinary model in a complex, global environment. The engagement began with business process redesign, industry best practices, global leadership alignment and a business blueprint, then moved into the technical blueprint and implementation. Several aspects stood out: The program covered 17 manufacturing sites across several geographies; PwC brought global pharma and life sciences expertise into local market workshops; the client pursued one global SAP template, with incremental adjustments for specific countries, businesses and regulatory requirements; and PwC’s business process specialists worked alongside SAP implementation teams to ensure a smooth transition from process design to technology delivery. This case reinforced PwC’s strength as a business integrator and system integrator and its ability to drive large SAP-led business transformation. For clients with complex multinational operations, this is the kind of integrated role PwC wants to own.
 
An India-native e-commerce client implementing Oracle Fusion offered a different but equally useful proof point. The client’s finance transformation involved moving multiple businesses and acquired entities from disparate ERP environments into Oracle Fusion. The risk profile was also high. The client needed to migrate critical finance, payment and purchasing systems with limited fallback options. The timing added pressure because the go-live occurred shortly before India’s festive season, when e-commerce volumes surge.
 
The client emphasized change management as a major success factor. PwC helped identify impacted areas, prepare stakeholders, support training, and guide users through the shift from customized legacy ways of working to more standardized enterprise processes. In TBR’s view, the e-commerce use case stood out because it showed PwC in a setting where execution risk was immediate and measurable. Unlike conceptual AI programs, ERP transformations of this scale expose weaknesses quickly. The client’s description of three-shift workdays, relay-race execution and a no-fallback go-live underscored PwC’s role as a delivery partner in business-critical transformation.
 
A panel discussion between a global engineering R&D services client, PwC and Google about the client’s implementation of Google SecOps effectively connected PwC’s trust and AI themes. The client moved from a legacy outsourced managed security services provider security operations model to an AI-led, automated and more forward-looking security operations center using Google SecOps, with PwC as the implementation and operations partner. The client chose PwC after evaluating multiple partners, including other large firms.
 
The client highlighted that PwC’s key differentiators included the firm’s experience with Google SecOps, its certified Google team, and prior client implementations. Gaining partners’ trust by investing in the development of certified resources is a recurring theme in TBR’s ongoing Ecosystem Intelligence research. This further confirms PwC’s understanding of the importance of shifting from the usual vendor-agnostic message to a focus on becoming a preferred player in specialized sectors. Additionally, this use case supported PwC’s broader argument that AI creates value when embedded in operating workflows. It also reinforced the trust theme: faster security operations yield not only efficiency gains but also improvements in risk and resilience.
 
A use case from an India-based pharmaceutical client provided one of the clearest examples of AI value being built on data discipline. Following a multiyear transformation journey — from establishing a cloud data lake to building more than 1,000 enterprise dashboards with strong governance and data quality — the client introduced an AI-powered conversational analytics platform. The solution, built in partnership with PwC, enables business users to interact with enterprise data in natural language, instantly generate insights, and accelerate decision making without relying on traditional dashboards or technical teams. PwC’s AI-led data managed services role was notable. The client moved from a more transactional data engineering relationship with PwC to a managed services model centered on cross-functional teams, shared ownership, agile delivery discipline, AI in the software development lifecycle, and productivity improvements.
 
The company cited that it had already achieved a 15% productivity gain, with a longer-term goal of 30% and, eventually, higher productivity improvements. This use case aligned closely with PwC’s central summit message: AI value does not come from pilots alone. It requires governed data, process ownership, shared incentives, productivity discipline and operating model change. We also believe that use cases like this one will help PwC test its ability to drive outcome-based pricing at scale, as productivity gains remain a focal outcome objective for clients.
 
A session with a multinational technology provider in the travel industry highlighted how India-based GCCs are transforming from mere cost centers into global value centers, owning not just execution but strategic decision making for their parent organizations. The client story aligned with PwC India’s own GCC positioning. PwC is positioning itself to serve global companies both at clients’ headquarters and at PwC’s India-based GCCs, using its network model and India’s talent depth to connect strategy, engineering, transformation and operations under one coherent offering. The earlier use case with the insurance client and Palantir echoed this point: India GCCs are no longer just client organizations to be advised from the outside; they are co-innovation partners, with PwC India embedding itself as a strategic architect of that transformation.

AI Labs move PwC India’s AI story from presentation to productized go-to-market

A notable addition to PwC India’s 2026 Analyst Summit was a GenAI pop-up lab that shifted part of the event from client storytelling to hands-on demonstrations. The lab showed how PwC India is working to translate its AI positioning into a more tangible portfolio of assets, accelerators, solutions that have delivered value to customers, and repeatable use cases aligned with CXO priorities: revenue enhancement, cost optimization and risk reduction.
 
PwC framed the AI lab around the layers where enterprise clients can most directly influence outcomes: platform orchestration, models, data and knowledge, agents and applications. Rather than focusing on foundational compute or model development — areas dominated by hyperscalers, chipmakers and governments — PwC emphasized the enterprise-facing layer where clients need orchestration, process integration, data unlock, domain context and governance. We see the framing aligning with PwC’s broader strategy to position itself as the integrator of AI into enterprise workflows.
 
The lab demonstrations also reinforced a key message from the summit. PwC India’s AI strategy is not limited to advisory or proof-of-concept work. The firm is building use-case-specific solutions that can be shown, adapted and commercialized across sectors. PwC’s AI lab highlighted use cases including an agentic procurement suite; an AI-enabled Social Registry platform for the government of Assam; a multi-agentic AI project management twin; an agentic e-commerce solution; and a Palantir-enabled procurement and sourcing offering.
 
The lab’s session structure was important as PwC did not present the assets as disconnected demos. They were mapped to business priorities and to a maturity stack, AI factories and data centers, platforms and orchestration, models and weights, data and knowledge, agents and apps. That structure gave the lab more strategic relevance than a conventional technology showcase.
 
In TBR’s view, the AI lab served three purposes. First, it made PwC India’s AI capabilities more concrete. Throughout the summit, PwC leaders noted that clients want AI to improve revenue, reduce cost and manage risk. The lab gave tangible examples of how PwC intends to meet those needs through repeatable assets focused on delivering business value with AI at the center rather than bespoke consulting alone. Second, the lab supported PwC’s broader move toward asset-based and lower-cost delivery.
 
Several PwC leaders discussed the need to reduce delivery costs using AI, institutionalized delivery and reusable tools. The lab demonstrated how PwC India is packaging domain expertise into repeatable AI-enabled solutions that can accelerate client work and potentially improve margins. Third, the lab strengthened PwC India’s go-to-market credibility with enterprise buyers by aligning demos with recognizable business problems. Such positioning can help PwC address key pain points in scaling AI adoption as clients increasingly want AI solutions that integrate directly with business processes, rather than generalized AI experimentation.

PwC India is making a credible case for scaled AI delivery, but proof must remain outcome-led

PwC India is increasingly playing a more consequential role within PwC’s global consulting network as the firm is being positioned — and increasingly tested — as a platform for AI-enabled delivery, global client execution, alliance-led transformation and outcome-accountable commercial models. PwC India’s 2026 event showcased a stronger, more coherent model than in 2024: trusted relationships, India-based delivery depth, global integration, AI-asset-based delivery and commercialization and partner-enabled platforms.
 
The challenge is that every major professional services firm is pursuing similar themes. PwC India’s differentiation will depend on whether it can turn client-specific success stories into repeatable offerings without weakening the local intimacy, senior partner involvement and execution discipline clients and partners praised throughout the event. The firm’s opportunity is substantial; so is the operating complexity it is choosing to absorb.