 Technology Business Research, Inc.
Should Accenture Enter Assurance?
What would Accenture Assurance look like?
Accenture’s potential entry into assurance would represent a logical, albeit controversial, extension of its Reinvention Services strategy, particularly as enterprise adoption of AI creates demand for independent verification of technology performance, business outcomes and regulatory compliance. Rather than replicating the Big Four’s traditional financial audit businesses, Accenture could establish a technology-led Assurance practice centered on AI model validation, cybersecurity, data integrity, agentic AI governance and continuous performance monitoring. Accenture’s September 2026 partnership with Anthropic offers an early blueprint.
The opportunity becomes more compelling as enterprises increasingly adopt open-weight models, assuming greater responsibility for model customization, security and performance rather than relying exclusively on proprietary model providers. Accenture’s August 2026 blog outlines the company’s open-weight models services, including Model Onboarding and Assurance, demonstrating Accenture’s recognition of this opportunity. Although it is a somewhat separate and rather long-term play, Accenture could pursue assurance as a recurring, IP-enabled business that extends its relevance beyond implementation and managed services into ongoing verification of enterprise AI environments.
How would competitors and the ecosystem react?
Accenture’s expansion into assurance would challenge the Big Four’s ability to capitalize on the convergence of technology, risk and regulatory compliance, potentially accelerating their investments in AI-enabled assurance delivery. But the Big Four are not standing still. PwC launched Assurance for AI in June 2025, while KPMG expanded its AI Assurance capabilities in September 2025 and subsequently invested in Fieldguide to develop agentic capabilities for assurance delivery. Yet the more consequential disruption could emerge across the broader AI ecosystem.
As enterprises diversify their technology stacks across proprietary and open-weight models, demand for vendor-neutral evaluation should increase, creating opportunities for Accenture and its peers to establish themselves as an intermediary between foundation model providers, hyperscalers and enterprise buyers. This could shift some influence over AI governance from individual technology vendors to services providers capable of validating increasingly heterogeneous AI environments. However, hyperscalers and model developers could respond by embedding more sophisticated evaluation capabilities into their platforms, while the Big Four could leverage their established independence credentials and regulatory relationships to defend their market positions.
Accenture’s extensive commercial relationships with technology partners, including Anthropic, could also undermine its claims of independence. The company would need to demonstrate that its evaluations are not simply extensions of its implementation and alliance businesses. Ultimately, we believe the competition would extend beyond the vendors that evaluate AI models to those that control the standards, assessment frameworks and ongoing relationships that govern enterprise AI adoption. With AI governance top of mind for buyers, vendors and their technology partners, the race is just getting started.
Does TBR think assurance is a good strategy for Accenture?
TBR believes Accenture should selectively expand into technology and AI assurance, but entering traditional financial audit would create unnecessary complexity and distract the company from its broader Reinvention Services ambitions. The more attractive opportunity lies in establishing an independent assurance capability that complements Accenture’s engineering expertise while addressing the growing accountability gap created by enterprise adoption of open-weight models and increasingly complex multimodel architectures.
Importantly, Accenture’s existing Model Onboarding and Assurance capabilities raise a strategic question: Would establishing a dedicated Assurance business create meaningful differentiation or simply repackage services already embedded within its portfolio? TBR believes the answer depends on Accenture’s willingness to separate validation from implementation and managed services. Although Faculty provides Accenture with technical credibility in model evaluation, formal independent assurance requires governance, professional standards and conflict-of-interest safeguards that cannot be established through technology capabilities alone.
Accenture could initially target independently governed assessments of third-party AI environments, avoiding engagements where it is simultaneously responsible for building, operating and validating the same systems. Such an approach could create recurring, asset-enabled revenue streams, strengthen board-level relationships, and reduce reliance on traditional FTE-based services economics. However, the commercial potential remains unproven, particularly as technology vendors increasingly automate model evaluations and the Big Four expand their own AI assurance capabilities.
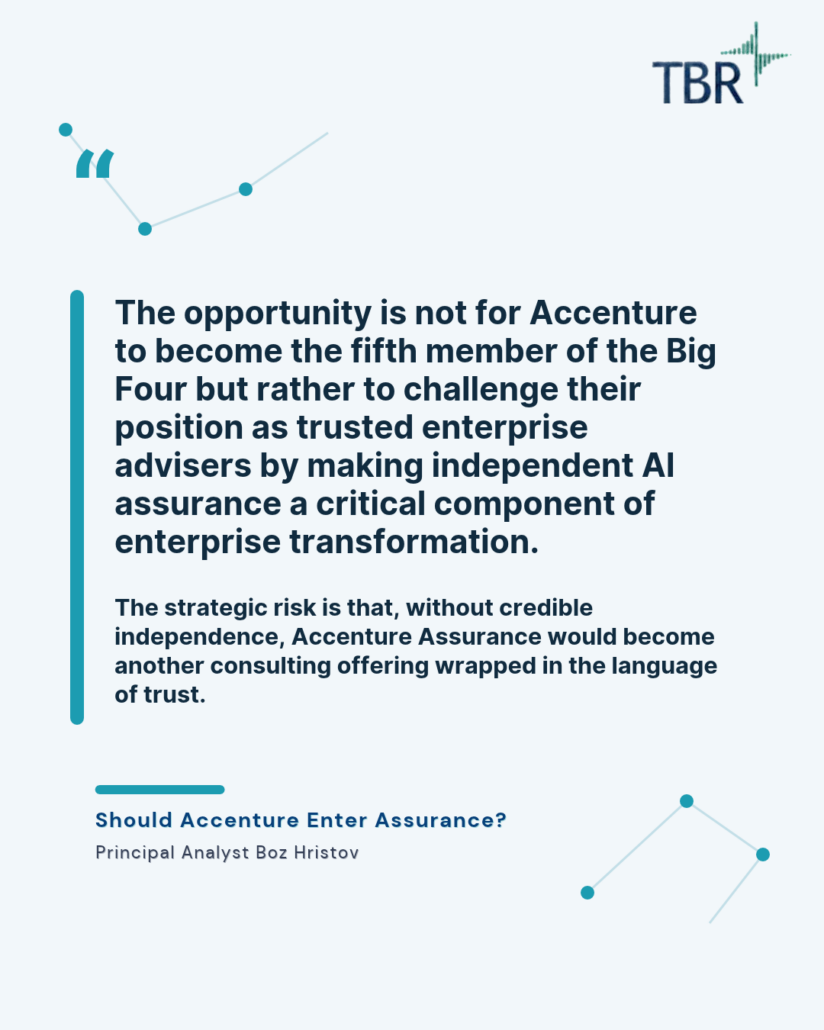
TBR believes the opportunity is not for Accenture to become the fifth member of the Big Four but rather to challenge their position as trusted enterprise advisers by making independent AI assurance a critical component of enterprise transformation. The strategic risk is that, without credible independence, Accenture Assurance would become another consulting offering wrapped in the language of trust.
 Maxim Basinski, Vasabii via Canva Pro
 Elnur, via Canva Pro
 Getty Images via Canva Pro
 Getty Images, via Canva Pro
 JLGutierrez, Getty Images via Canva Pro
 Technology Business Research, Inc.