Salesforce vs. ServiceNow in AI Adoption Expectations for 2027

The defining question for ServiceNow and Salesforce in 2027 is no longer whether they can articulate compelling agentic use cases. It is whether those use cases begin driving meaningful consumption on their platforms. Both companies have been messaging that opportunity for months, but 2027 should show whether early momentum can translate to sustainable growth.

ServiceNow: Data and analytics must become part of the platform

ServiceNow enters 2027 with a strong growth profile, supported by new pricing and packaging changes. Its ©Human Intensity Reduction Index (HIRI), TBR’s proprietary metric that measures the impact of a company’s AI, human capital, automation, utilization, offshore leverage and delivery model evolution on its operating margin, is expected to continue rising. The company has indicated it will start the new year with pre-acquisition headcount. Together, those signals point to a steady increase in HIRI rather than a sudden jump.


ServiceNow may also pursue tuck-in acquisitions, particularly as pressure mounts to expand data and analytics capabilities. The challenge will be integration. Rather than using the building-block approach associated with Salesforce, ServiceNow will need to make data and analytics part of the platform layer so those capabilities can scale across the stack.

Salesforce: Agentforce adoption can support durable growth

Agentic-driven revenue at Salesforce is still growing from a small base, but early customer behavior has been encouraging. Metrics shared during the 2Q26 earnings call showed usage doubling among early Agentforce adopters. This positive trend points to growth from both new logos and existing customers as well as a more sustainable trajectory. Given the small base and high growth rates, that momentum may not taper soon.

Partnerships and model diversity will matter more

Across the agentic execution layer, partnerships with model labs are becoming increasingly important. Salesforce has moved aggressively to open integrations, including its Claude announcement ahead of the 2Q26 earnings call. That direction suggests more connections between software incumbents and rapidly rising model labs.
 
At the same time, model diversity should expand. Smaller language models, open-weight models and domain-specific models can help vendors manage the AI cost curve. ServiceNow and Salesforce are positioned in front of large install bases, giving them an opportunity to act as intelligence brokers: offering the best model for the job at the right price, while tuning models to the tasks their customers need.

The signal to watch in 2027

The key test is consumption. ServiceNow will need to pair a rising HIRI with broader integrated platform adoption, while Salesforce will need to convert early Agentforce usage into sustained growth among new and existing customers. For both companies, the strongest evidence will be meaningful agentic activity on the platform, not just another round of announcements.
 
Listen to “ServiceNow vs. Salesforce Showdown: AI Adoption” to hear TBR experts compare changes in revenue per employee and operating leverage, identify weaknesses in both companies and across the technology space, and build a competitive intelligence case for each vendor’s market position. Part of the Vendor Showdown Series on the TBR Talks podcast, the episode puts analysts in the role of head of strategy for the companies they cover.

Should Accenture Enter Assurance?

What would Accenture Assurance look like?

Accenture’s potential entry into assurance would represent a logical, albeit controversial, extension of its Reinvention Services strategy, particularly as enterprise adoption of AI creates demand for independent verification of technology performance, business outcomes and regulatory compliance. Rather than replicating the Big Four’s traditional financial audit businesses, Accenture could establish a technology-led Assurance practice centered on AI model validation, cybersecurity, data integrity, agentic AI governance and continuous performance monitoring. Accenture’s September 2026 partnership with Anthropic offers an early blueprint.
 
The opportunity becomes more compelling as enterprises increasingly adopt open-weight models, assuming greater responsibility for model customization, security and performance rather than relying exclusively on proprietary model providers. Accenture’s August 2026 blog outlines the company’s open-weight models services, including Model Onboarding and Assurance, demonstrating Accenture’s recognition of this opportunity. Although it is a somewhat separate and rather long-term play, Accenture could pursue assurance as a recurring, IP-enabled business that extends its relevance beyond implementation and managed services into ongoing verification of enterprise AI environments.

How would competitors and the ecosystem react?

Accenture’s expansion into assurance would challenge the Big Four’s ability to capitalize on the convergence of technology, risk and regulatory compliance, potentially accelerating their investments in AI-enabled assurance delivery. But the Big Four are not standing still. PwC launched Assurance for AI in June 2025, while KPMG expanded its AI Assurance capabilities in September 2025 and subsequently invested in Fieldguide to develop agentic capabilities for assurance delivery. Yet the more consequential disruption could emerge across the broader AI ecosystem.
 
As enterprises diversify their technology stacks across proprietary and open-weight models, demand for vendor-neutral evaluation should increase, creating opportunities for Accenture and its peers to establish themselves as an intermediary between foundation model providers, hyperscalers and enterprise buyers. This could shift some influence over AI governance from individual technology vendors to services providers capable of validating increasingly heterogeneous AI environments. However, hyperscalers and model developers could respond by embedding more sophisticated evaluation capabilities into their platforms, while the Big Four could leverage their established independence credentials and regulatory relationships to defend their market positions.
 
Accenture’s extensive commercial relationships with technology partners, including Anthropic, could also undermine its claims of independence. The company would need to demonstrate that its evaluations are not simply extensions of its implementation and alliance businesses. Ultimately, we believe the competition would extend beyond the vendors that evaluate AI models to those that control the standards, assessment frameworks and ongoing relationships that govern enterprise AI adoption. With AI governance top of mind for buyers, vendors and their technology partners, the race is just getting started.

Does TBR think assurance is a good strategy for Accenture?

TBR believes Accenture should selectively expand into technology and AI assurance, but entering traditional financial audit would create unnecessary complexity and distract the company from its broader Reinvention Services ambitions. The more attractive opportunity lies in establishing an independent assurance capability that complements Accenture’s engineering expertise while addressing the growing accountability gap created by enterprise adoption of open-weight models and increasingly complex multimodel architectures.
 
Importantly, Accenture’s existing Model Onboarding and Assurance capabilities raise a strategic question: Would establishing a dedicated Assurance business create meaningful differentiation or simply repackage services already embedded within its portfolio? TBR believes the answer depends on Accenture’s willingness to separate validation from implementation and managed services. Although Faculty provides Accenture with technical credibility in model evaluation, formal independent assurance requires governance, professional standards and conflict-of-interest safeguards that cannot be established through technology capabilities alone.
 
Accenture could initially target independently governed assessments of third-party AI environments, avoiding engagements where it is simultaneously responsible for building, operating and validating the same systems. Such an approach could create recurring, asset-enabled revenue streams, strengthen board-level relationships, and reduce reliance on traditional FTE-based services economics. However, the commercial potential remains unproven, particularly as technology vendors increasingly automate model evaluations and the Big Four expand their own AI assurance capabilities.
 
TBR believes the opportunity is not for Accenture to become the fifth member of the Big Four but rather to challenge their position as trusted enterprise advisers by making independent AI assurance a critical component of enterprise transformation. The strategic risk is that, without credible independence, Accenture Assurance would become another consulting offering wrapped in the language of trust.

Sapiens’ AI Transformation: Inside its Bet on Autonomous Insurance

On Oct. 5-6, Sapiens hosted TBR and a dozen other analysts at the kickoff of the 2026 Ignite event in Nashville and provided presentations from and access to many of the new Sapiens’ executive team including: Mike Ettling, executive chairman of the board; Paul Wheeler, CEO; Glen Ceniza, chief technology officer; James Hannay, chief revenue officer; Yariv Hasar, North America president; Paul Hutchison, chief delivery success officer; Michael Rieder, chief customer success officer; and Franck Cohen, chairman, CYE, and senior board advisor. TBR’s assessment of the event and Sapiens’ recent changes reflect the presentations and conversations in Nashville as well as TBR’s ongoing assessment of Sapiens and its place in the broader technology ecosystem.
 
Forty-year-old companies do not transform at the speed of AI. They do not upend their commercial and delivery models at the same time. And successful transformations almost never start with a wholesale leadership overhaul spurred by new ownership. Well, maybe that last one happens, but the first two do not. For the last nine months, Sapiens has been testing the possibilities of radical AI-enabled change, while continuing to support customers in a highly regulated and hidebound industry. New leadership has challenged the company to move at AI speed while establishing a new standard for quality. Sapiens has made a massive bet that the trust it has built with long-standing clients will carry over as the company shifts its commercial, delivery and technology partner models to a fully AI-enabled way of working. It is a bold bet; now comes the execution.

New leadership, an AI-enabled platform and a SaaS-first model are reshaping Sapiens

Sapiens became a private company on Dec. 17, 2025, when Advent completed its acquisition. Ettling became executive chairman and interim CEO, and Wheeler and Hannay joined as CFO and chief revenue officer, respectively. Ceniza joined as CTO in January 2026, and Hutchison and Rieder were subsequently appointed to lead delivery and customer success, respectively. Wheeler was named CEO in August. With more than 40 years of experience behind it, Sapiens has put that experience to work in SapiensAIP, the Sapiens Autonomous Insurance Platform, launched in September 2026. Sapiens also moved its global headquarters to London as of June 2026.
 
Cohen noted that Sapiens does not view technology and AI as the core challenges facing its clients. Instead, legacy insurance processes create a barrier to change, data remains siloed and the opposite of seamless, and change management confounds even the most agile insurance companies. Hannay added that Sapiens’ clients express an eagerness to learn about AI but do not understand the reality of what AI can (and cannot) do or where to start. Notably, during both an analyst breakout and main-stage presentations, a few clients discussed success they are achieving in AI adoption, although every other client TBR spoke with remained in the exploration and pilot stages, reinforcing Hannay’s assertion.
 
On Sapiens’ evolving business model, both Wheeler and Ettling said the company had shifted its services strategy, deemphasizing services revenue and forgoing the standard time-and-materials commercial model. When TBR asked how those changes could affect ecosystem partnerships, Sapiens executives described prioritizing SaaS commercial models while concurrently packaging services with traditional global systems integrators’ and consultancies’ core offerings. In TBR’s view, Sapiens’ commercial model pivot may prove to be as consequential as the company’s AI platform investment. Sapiens’ ecosystem partners will increasingly expect flexibility, outcomes-based pricing, and a focus, by Sapiens, on staying in its swim lane. Driving a SaaS business model while pulling back on services should make Sapiens a highly attractive business partner to the likes of Capgemini, Accenture and Deloitte.
 
The customer panel with analysts provided tremendously useful insights into the challenges Sapiens faces in the near term, including overcoming legacy perceptions about the company’s products, delivery and customer support. (Note: Sapiens’ newly hired customer success executive was in the room to hear the unvarnished customer feedback.) Customers voiced common concerns about AI and technology adoption, including the need for change management embedded at the start as well as a target operating model, the benefits of evangelists and champions, and the imperative to encourage experimentation. Another customer mentioned that documentation had long been a problem when working with Sapiens but noted his expectations had changed with the new ownership and leadership.
 
In TBR’s view, Sapiens’ CTO’s repeated assertions that the new AI-enabled platform would include near-complete auditability likely addressed the documentation concerns. Overall, the customers on the panel with analysts and on the main stage, as well as those TBR spoke with during the event, all expressed quite clearly that they believed the new leadership brought critically important change to Sapiens.

Sapiens makes auditable AI its competitive advantage

Sapiens built a brain. As simplistic as that sounds, it perfectly captures exactly what Sapiens did in a surprisingly short time. Sapiens had 40-plus years of documentation, software code, change orders and contracts it used as a foundational data layer, which created 500,000-plus nodes and 11 million connections between those nodes. Every Sapiens engagement going forward will be grounded in this AI brain, which AI agents can tap into, provide answers, and make decisions faster and more accurately than Sapiens’ own engineers. Sapiens’ brain provides the knowledge base, the agents do the reasoning, and what Sapiens calls “surfaces” allow actions by Sapiens’ clients and their agents.
 
Notably, whenever Ceniza discussed AI or SapiensAIP, he stressed that Sapiens’ AI included oversight by design and is and will be held to a higher standard than humans. He also noted that Sapiens built the AI platform outside of the core Sapiens software systems, in no small part because those legacy core systems were not built for AI, could not adapt at AI’s speed, and could not be reused in an AI-native manner. Critically — and this point came up during sessions with analysts and on the main stage — Ceniza said the company intended to “set a new standard for AI quality,” which he defined as AI that is “accurate, consistent and fully auditable.”
 
Moving to a 10,000-foot view of the AI age, TBR notes that during the last 18 months “fully auditable” has shifted from a niche concern of governance, risk and compliance consultancies to a near-board-level discussion at many enterprises (perhaps thanks to those consultancies themselves, notably KPMG and Grant Thornton). Sapiens has exceptionally deep domain knowledge around how insurance companies’ software and IT actually work. The company has tapped into that knowledge in a secure and compliant manner while leveraging it to make Sapiens’ AI smarter. And Sapiens is bringing all of that to clients in a unified and comprehensive manner while remaining respectful of the systemic challenges clients continue to face.
 
Without deep expertise on the insurance industry, TBR has to analyze Sapiens’ approach from our extensive technology and services business model knowledge and the perspectives of ecosystem partners. In short, we believe Sapiens’ approach makes tremendous sense. Build a knowledge layer on your own proprietary, but highly relevant, data. Establish proper governance. And unleash AI to make processes and decision making faster. Can the insurance industry keep pace with Sapiens? That is for others to determine, but in TBR’s view Sapiens has assembled nearly all the essential components. Now comes the execution. After Sapiens’ new executive team made a 90-minute pitch about the company’s reinvigorated strategy, TBR asked clients attending the event for their assessments. Responses varied from genuine surprise and excitement to wait-and-see skepticism. As always, delivering results will determine what customers come to believe.

2027 predictions: Not Your father’s Sapiens

A few questions remain for TBR:

  • Will becoming more local, placing talent closer to clients, and embracing the forward-deployed engineer model conflict with Sapiens’ overall strategy of retiring the federated model and presenting clients with one view, one experience, one commercial engagement? It might. But if on-the-ground Sapiens professionals can sell, deliver and support the full Sapiens portfolio, maybe these strategies will not create tensions and uncertainties. Being exceptionally local and maintaining a global quality standard has bedeviled IT services companies and consultancies for generations. With its combined AI and SaaS model, perhaps Sapiens will not struggle with this challenge.
  • As Sapiens rapidly transitions into AI, how will the company’s slower-moving customers respond? Will the new Sapiens be able to satisfactorily support laggards on the AI journey? Will Sapiens say “no” when customers resist a move toward the new AI-enabled platform? The answers to the last two questions are probably “yes” and “no,” but the company will be looking for customers to match Sapiens’ own acceleration into AI.
  • With the new ownership, Sapiens has taken a cudgel to every aspect of its business model: commercial, operations, delivery and (soon) partner. For a 40-year-old company with its own technology, process and skills debts, the question becomes, “What happens to the legacy people, knowledge and culture?” In TBR’s view, uncertain leadership would struggle to navigate these seismic changes. Sapiens’ new leadership is not uncertain.

So, what should we make of Sapiens now and heading into 2027? TBR cannot evaluate what all these changes mean for customers. Like most of the new Sapiens leadership, TBR does not have insurance domain expertise. But TBR understands what these changes mean for Sapiens’ ecosystem partners: a commercially flexible, AI-enabled, well-established, industry-specific software leader should be an exceptionally good partner for an SI or consultancy changing its own commercial, delivery and partner business models. TBR repeatedly stresses three core business beliefs: Do what you do well (and nothing else), do not bore clients with your internal changes, and do everything possible to help your ecosystem partners sell you. Sapiens appears to be moving along those tracks with AI-enabled speed. For the third time: Now comes the execution.

Infosys Moves From AI Experimentation to Enterprise Orchestration as Infosys Topaz Takes Center Stage in the Company’s Next Chapter

Infosys hosted more than 200 clients, partners, analysts and advisers during its flagship event, Infosys Americas Confluence 2026. The packed agenda included Partner Day and Analyst Day tracks, client stories, partner presentations and Living Labs demos of both Infosys- and partner-developed solutions and services. AI dominated the agenda, but the conversations were notably different than those at Confluence 2025. Last year, Infosys and its clients largely focused on the prerequisites for enterprise AI adoption, including data readiness, governance, architecture and talent. This year the discussion shifted toward what happens when enterprises actually begin scaling AI; the need to address rising complexity, agent governance, token economics, cybersecurity and model choice; and the ever-difficult task of proving business value. Infosys used the event to reinforce its ambition to become a leading enterprise AI services provider, positioning Infosys Topaz — and increasingly Infosys Topaz Fabric — as the enabling layer connecting models, applications, data business processes and partner technologies.

Infosys Topaz is evolving from an AI portfolio into an orchestration layer, putting Infosys’ integration strengths back at the center of the AI opportunity

Infosys’ AI strategy has matured considerably since Confluence 2025 and even more significantly compared to two years ago. In 2024, Infosys was positioning Infosys Topaz as a collection of AI services and solutions that could sit on top of the company’s Cobalt cloud foundations, as the company was taking a more pragmatic approach to increase its value with clients, using the idea that a client could not meaningfully scale generative AI (GenAI) without first addressing data, governance, architecture and workforce readiness.
 
In 2026 these prerequisites remain, but Infosys is now trying to operationalize them through a more coherent AI architecture. Infosys’ AI-first value framework spans areas including strategy and engineering, data, process AI, agentic legacy modernization, physical AI and AI trust, with the company tying these capabilities to three broader market shifts: automated intelligence, AI-augmented workforce and AI-powered predictive agility. Infosys Topaz Fabric provides a common layer through which the company can expose models, tools and AI assets while protecting client data and managing the economics of model consumption.
 
Supporting both open and closed public models through Infosys Topaz Fabric will give the company the flexibility to strengthen its position as an AI orchestrator. We believe supporting both models is table stakes for the services provider, which, for years, has played the technology-agnostic game with its alliance partners. The true value will come from Infosys’ ability to deploy its frontier engineers at speed and capture the right balance of AI-first and AI-infused revenue opportunities, as the former will help it drive higher pricing and the latter will increase client stickiness. Managing the expectations of impatient shareholders will be key, especially as peers pursue similar strategies.
 
An event session with an energy client brought some of that strategy to life. Infosys argued that the only part of the AI stack the enterprise truly owns is the context, including processes, institutional knowledge, operating history and domain expertise. The model can be rented or swapped, but context can not. The client described context not as a static database but as a supply chain containing years of engineering knowledge, operational data, procedures, decisions and best practices.
 
This framing aligns with Infosys’ strategy as the company does not need to own the client’s context but rather make the context usable across applications, data and business workflows. Understanding the context is key to Infosys’ value proposition. The client described Infosys connecting those dots while leaving ownership of the underlying knowledge to the client. Executing well against the strategy could help Infosys elevate in the context-orchestration assurance value chain, a step above its traditional implementation services realm, but it could also fall short if the company fails to remain proactive in the “what’s next phase” of the client’s business growth conversations.

AI-centric alliances allow Infosys to build its position as a tech orchestrator, but differentiation will require agility as the tech requires a multiparty setup

Although alliance partners remain central to Infosys’ go-to-market strategy, AI is changing their function. In a traditional cloud or enterprise application relationship, partners often provided the technology platform while Infosys supplied the integration, implementation and managed services. AI, however, makes the relationship a bit more fluid as clients may use several model providers, hyperscalers, SaaS platform and AI-native tools simultaneously. This will test Infosys’ traditional vendor-agnostic stance as the ability to move between technologies and govern them consistently becomes as important as expertise in any one platform.
 
During the event, Infosys’ executives including company’s CEO Salil Parekh highlighted partnerships with cloud, SaaS and frontier AI companies while noting that Infosys Topaz Fabric can select the appropriate model for the task and cost requirements. Meanwhile, the company continues to use its large install capabilities around vendors such as SAP and Microsoft serve as the foundation for AI-enabled transformation, particularly as those vendors increasingly embed AI into their own platforms. The 360-degree arrangements of some of these relationships has historically benefited Infosys, as clients often view Infosys as a trusted execution provider.
 
AI has now raised the stakes, and Infosys has an opportunity to elevate that trust further and become as independent orchestrator across a fragmented AI stack. Over the last six months, Infosys’ alliances with Anthropic, OpenAI, Intel, Harness and Cursor suggest the company is trying to capture the emerging opportunity between AI creation and enterprise execution. Anthropic gives Infosys access to frontier reasoning and agent design for complex, regulated workflows, which help Infosys move upstream into operating-model redesign rather than be confined to downstream implementation.
 
Through its relationship with OpenAI, Infosys is combining Infosys Topaz Fabric and OpenAI Codex to jointly drive AI adoption across enterprises, with a focus on transforming software development and modernization. We see the relationship with OpenAI as both an opportunity and a threat for Infosys, highlighting leadership’s willingness to disrupt the company rather than be disrupted. By tying Infosys Topaz Fabric to Intel Xeon, Gaudi and AI PC environments, and by emphasizing rightsized architectures, benchmarking and total cost of ownership, Infosys is positioned to shape enterprises’ infrastructure decisions before they select hyperscaler-led architectures. Harness then tackles the production bottleneck that follows AI-enabled code generation by standardizing the path from code to governed deployment across hybrid and multicloud estates.
 
Cursor adds another layer of significance because it pushes Infosys deeper into the developer workbench. If Infosys can standardize these partner technologies across its own delivery base, it could convert internal productivity gains into a proprietary delivery advantage by using its workforce as both a proving ground and a distribution channel. With Infosys’ ©Human Intensity Reduction Index (HIRI) trending toward 0% in the last few quarters, the company has a long way to go before nonlinear growth materializes. We believe the best path forward for Infosys will be less about monetizing agents through direct sales and more about bundling them in fixed-priced-wrapped contracts that can help it generate higher volume, but only after it pivots from IT-based to business-centric outcomes.

Client use cases demonstrated that Infosys’ AI value proposition centers on embedding AI into transformations already understood

Client examples throughout the event were more mature than the productivity pilots that dominated early GenAI discussions, with some of the more concrete examples revolving around embedding AI into broader modernization, engineering and operating model changes.
 
For an energy client, Infosys built an operations assistant that began as a conversational interface for engineering procedures but evolved into a tool that helps engineers aggregate data, conduct analysis, and move from the client reactively addressing issues toward more proactive operations. The client linked the approach to improved maintenance and reliability; lower operating costs; and extended useful life of assets, potentially by several years. Infosys is also codeveloping the client’s enterprise AI platform, where multiple agents support both revenue-generating and cost-cutting use cases.
 
A financial services client offered a different modernization example. Instead of approaching legacy IT environments as systems that must be replaced wholesale, the company described using AI to automate regression testing, document legacy applications and incrementally modernize older code. This use case shed light on the shift AI is creating around cost versus value, potentially making incremental renovations more attractive than large-scale replacement programs, especially as the overuse of tokens can backfire and slow progress. For Infosys, this could expand its application modernization opportunity, even as automating coding reduces the labor needed for individual tasks.
 
A personal-care provider illustrated the relationship between platform implications and AI readiness. Using the Infosys Equinox commerce platform to support its IT transformation initiative, the company is in the process of consolidating seven disparate commerce platforms into two. The client emphasized that fragmented technology and data environments become even more problematic as AI scales, as they amplify wherever complexity already exists, further reinforcing Infosys’ position that AI does not replace the need for modernization but makes it more urgent.
 
Other examples showed similar progression from isolated pilots to scale programs. One client said it had moved roughly 24 AI use cases into production within several months, with another 27 ready to follow, and described Infosys Topaz as helping turn large volumes of operational events into actionable outcomes. Infosys is also extending Infosys Topaz Fabric into developer environments and operations tools, including lightweight embedded apps and purpose-built applications for modernization, software development life cycle, data engineering and process engineering.
 
Protecting relevance while creating a path toward higher-value orchestration work will allow Infosys to maintain client stickiness as the company continues to use AI to deepen and accelerate transformation programs across technology estates it is already familiar with. Although one can argue that forums such as Confluence often have a predetermined agenda and talking points, TBR’s attendance at the conference the last several years and ongoing coverage of the company for the better part of the last two decades have allowed us to see and hear clients’ firsthand accounts and consistent feedback about the company’s culture built around humility. Many of the clients presenting on stage are not just frequent presenters but also expand on the relationship story and discuss what’s new and what’s changing in their work together.

Governance is moving upstream as agentic AI expands both the opportunity and the complexity of enterprise transformation

One of the consistent themes of the event was that AI becomes more complicated as it scales. Enterprises are discovering that moving several controlled pilots to hundreds or thousands of agents changes the governance problem significantly. Data lineage, agent identity, model selection, security, token consumption and accountability must increasingly be considered at the architecture and operating-model levels rather than handled on an ad hoc project basis.
 
Infosys’ clients, both on and off stage, repeatedly emphasized the importance of addressing governance earlier. For example, an energy equipment and manufacturing client described an approach in which AI ideas move through the governance process that asks questions about ROI, subject matter expert (SME) availability and data readiness before development begins.
 
Meanwhile, as agents proliferate across the enterprise and governance complexity increases the need for better cybersecurity, Infosys will create further openings if the company manages to combine capabilities that clients previously bought separately. As AI trust, cybersecurity, data architecture, application modernization and managed services increasingly intersect around the same workflows, the company could use Infosys Topaz Fabric as the connective layer while monetizing governance and assurance through recurring services. With both Infosys’ cybersecurity and Infosys Consulting capabilities cutting horizontally across the company’s entire portfolio, Infosys needs to ensure the internal governance hierarchy does not create a hurdle of greater integration, impacting client relationships.

AI will compress labor intensity faster than it eliminates Infosys’ talent pyramid, increasing pressure on the company to monetize productivity gains

Infosys is redesigning its workforce model for an AI-first services business. The company is building a talent strategy around three pillars: a new talent operating model, a new career model and a new talent development model. According to Infosys executives, these pillars will help the company “augment the whole organization with AI while also building deeper engineering and domain expertise to deliver AI-first services.”
 
We see these pillars as an evolution rather than a complete delivery model transformation as the company tries to minimize the disruption of its ongoing contracts and broader stakeholder ecosystem. We do not expect Infosys to ever fully change its delivery model and develop a HIRI that resembles that of a software company. However, the company’s workforce redesign will give it the necessary insights into how to position the newly developed skills with clients and tech partners. Executives noted that the company has trained more than 270,000 employees on AI, with a significant number already using AI-powered coding tools.
 
In addition, Infosys plans to build a pool of 6,000 frontier engineers over the next several years. This is in line with many of its peers, which are looking to pursue similar routes to elevate the value of their offerings. The challenge ahead for both Infosys and its peers is centered on balancing the scale and skills of this bench and on managing the influence of this bench on their staffing pyramids. The Palantir-developed forward-deployed engineer (FDE) model relies on fewer people and more platform-based service delivery centered on outcomes.
 
Moving away from the mindset and messaging around scale of this bench could be a double-edged sword unless Infosys transforms its commercial model at scale. The current use of fixed-price engagements creates a buffer against potential pushback from shareholders about revenue visibility. Using fixed-price contracts as a wrapper for outcome-based services will likely be the next phase but will compel Infosys to better align its expectations with tech partners.

Leadership continuity limits transition risk but could make it harder for Infosys move up the value chain

Confluence also served as an important marker in Infosys’ leadership transition. Parekh introduced company veteran Ashiss Dash, who was recently appointed by the board as the CEO Designate until April 2027, when he will become the company’s next CEO. Dash used his initial remarks to emphasize client centricity, continuous learning and the company’s long history of reinventing itself through successive technology disruptions. Although we do not expect Dash to make any drastic changes to Infosys’ operating model, we believe he will likely try to put a stamp on his tenure, just like every CEO, by pursuing further industry specialization and deeper alliance alignment.
 
Leaning on a strong foundation enabled through a pragmatic approach to enhance rather than fully transform its operating and delivery models will allow Infosys to focus on preparing its commercial and partner models to scale AI sales. Initial results suggest Infosys has the proper ingredients to execute on the task. Accelerating that evolution will test Dash’s ability to double the company’s revenue, as Parekh has done during his tenure, with Infosys growing from $10 billion in 2018 to over $20 billion in 2025. The stakes are high for Dash and his team, especially as AI is as much of a revenue tailwind worth messaging as it is a compressor of core areas. Expanding AI-first and AI-infused revenue while maintaining service quality execution will also test Dash’s readiness as the company looks to meet expectations within its stakeholder ecosystem.

Infosys’ next challenge is no longer proving it can build AI but whether it can shape what clients do with the technology

Infosys’ share of AI revenue grew from 5.5% in 1Q26 to 8.2% of total sales in 2Q26, suggesting that the company’s formula is working for now. Generating over $1 billion in AI services revenue on an annual basis is a notable milestone, but pushing the narrative too much could increase the cannibalization of traditional revenue. TBR will continue to monitor and estimate Infosys’ AI performance, especially as AI-related sales and marketing expenses create new margin headwinds. We believe that in two to three years, the company will be less vocal about itemizing AI sales. Sustaining momentum will be measured not just by sales but also by profitable growth, something Dash will have to navigate.
 
Infosys has a credible opportunity to separate from peers if it can make Infosys Topaz Fabric the operating layer for governed agent delivery while using FDEs to shorten the time to value and embed AI into clients’ operating models. That would strengthen Infosys’ differentiation at a time when many competitors continue to go to market leaning on AI tools plus their services. However, this shift will pressure Infosys’ commercial model. Clients are already expecting AI productivity benefits to flow back to them, and competitive intensity is increasing, raising the risk that Infosys gives away too much value through pricing concessions.
 
The company will need to carefully balance its use of time-and-materials (T&M)-based, fixed-price and agent-based pricing models, ensuring productivity gains are captured through outcome-based constructs rather than diluted through discounting. Execution complexity, partner dependence, offshore-led margin protection, and the need to recalibrate the staffing pyramid around FDEs and other AI-native roles remain the main risks to watch.
HCLTech Advances its Total Experience Services Through AI-led Operating Model Transformation

In September 2026, TBR spoke with HCLTech’s Enterprise Transformation & Advisory team about its Total Experience Services portfolio, which combines customer experience, employee experience and user experience into a single, unified framework, and how the advent of AI has accelerated the need for a connected and unified experience. HCLTech leadership also emphasized the need for Responsible AI to ensure that every layer of AI remains safe, governed and trustworthy, an essential aspect for IT services vendors to engage effectively with clients. 

Central platforms to overcome friction in experience

In an ever-connected world, HCLTech established its Total Experience offerings to create a unified user and customer experience for its clients, removing pain points and friction across teams and departments. The transformation begins with the operating model, as many companies have different platforms and experience solutions across functions. The goal of the company’s experience solutions is to connect users across operations by optimizing and redesigning operating models.
 
Lester Lam, HCLTech’s EVP of Enterprise Transformation & Advisory, discussed key market trends that are increasing the need for and relevance of HCLTech’s Total Experience Services. The notable market trend for TBR is the increasing pressure on clients to scale experience transformations. This trend is making it easier for vendors to convince clients to modernize legacy systems and adopt an AI-led operating model.

Lam explained that clients mainly face operational challenges, leading HCLTech to focus on operating model transformation and connecting all parts of the organization. The friction caused by managing disparate systems could be alleviated through AI, creating opportunities for HCLTech around advisory, design, implementation and management. By leveraging AI, HCLTech shortens analysis and workflow planning time, helping clients design systems that address their challenges faster and more cohesively.
 
HCLTech structures its Total Experience Services around three main groups — business, product and platforms. The groups help clients set and achieve outcomes by focusing on internal experience (business), services and products delivered (product), and underlying technology (platform), all grounded in a foundational level of experience. Lam also noted that establishing an AI-led operating model is the key to improving experiences and ensuring the transformation sticks by uniting all groups under one strategy.
 
According to Nish Trivedi, HCLTech’s SVP of Enterprise Transformation & Advisory, enterprises must transform six core levers to reshape their operating models effectively. The six enablers include strategy & alignment; governance, funding & value; data, platforms & AI; organization & roles; talent & culture; and execution model. HCLTech’s clear definition of AI-led operating model transformation and the key levers that need to be modernized to ensure the client can sustain the transformation set the company apart from its peers. Helping clients connect functions across their business through experience and underlying platforms requires all six levers to operate efficiently while also leveraging data and insights from interactions and customer engagements. HCLTech’s strategy aims to push clients’ organizations to operate as one and use standardized base levels that drive lasting change within enterprises and enable seamless cross-collaboration.

XMO

Trivedi outlined the HCLTech Experience Management Office (XMO), part of its Application Management Services portfolio, which aims to deliver business outcomes by integrating technology and human expertise. Embedding the XMO function into its Total Experience services improves HCLTech’s ability to create effective pathways to achieve outcomes, while combining the user experience with human touchpoints for more personalized and seamless experiences. Trivedi emphasized how HCLTech leverages personas and customer journeys to test its platform, identify challenges and determine how to fix them.
 
Using the XMO approach modernizes HCLTech’s ability to personalize the experience with a simple framework that still delivers value. Matching human touchpoints with the technology experience allows HCLTech to strengthen connections between employees and platforms as well as connections across units. The framework’s repeatable nature, paired with specialized personas, helps HCLTech accelerate engagements while maintaining client stickiness.

Change management

HCLTech would be remiss if it did not acknowledge the impact that AI and experience solutions have on traditional workflows, organizational structures and talent needs. According to Lam, the main challenge is distrust of AI, and organizations must recognize the problem to support change management. Lam noted that enterprises need transparency and acknowledgment to guide the talent transition and provide the resources to properly leverage new technology for greater productivity. Additionally, the theme of continuous change across organizations — including talent, portfolio, structure, partner ecosystems and strategy — that TBR has followed closely remains essential for enterprises to keep pace with changing technologies and client needs.
 
Change management is an essential piece of transformation and is considered an experience management lever for HCLTech. Guiding clients through the workflow and process transition ensures they can achieve outcomes, positioning HCLTech to generate value for its clients. HCLTech’s efforts to align its priorities with those of its clients are reflected in its change management approach, which considers AI-native needs and impacts. Lam also noted how HCLTech recognizes change fatigue among enterprises’ employees, given the frequent introduction of new tools, platforms and processes. Addressing these issues while bringing in a cohesive strategy and experience platform to improve workflows will help clients increase productivity. However, doing so requires careful consideration of these challenges and strategies to manage them effectively.
 
To ease these challenges and concerns within clients’ organizations, HCLTech leverages its Responsible AI framework to bring trust and governance across every AI layer. Heather Domin, HCLTech’s VP of Responsible AI, said that to fully realize value, clients need to blend AI capabilities, human adoption and earned trust. HCLTech’s Responsible AI involves educating and building understanding of risk, including how it will evolve. While it is impossible to predict all future risks, HCLTech’s Responsible AI prepares clients to respond to internal and external threats by establishing controls such as risk-based guardrails that depend on AI agent tasks, adding societal safeguards and human checkpoints, and ensuring leadership alignment.
 
Responsible AI presents many opportunities for HCLTech, particularly as concerns about AI use and controls grow. HCLTech can use these capabilities to strengthen clients’ existing AI environments with additional controls and insight into operations. Embedding responsible AI practices across its portfolio will strengthen HCLTech’s value proposition and build client confidence in integrating AI into their operating models by expanding human-in-the-loop capabilities and clarifying how to implement and monitor usage controls.

Client example

Lester explained how a global retail client used Total Experience to improve its brand management, operating model and digital marketing strategy. HCLTech helped the client rewire its operating model to improve demand ideation and enhance workflows. The main transformation focused on the client’s digital marketing strategy and consolidating brand management into one unit to create more cohesive, consistent operations. Additionally, simplifying the operating model helped HCLTech centralize the client’s brand and strategy to better leverage insights and data.
 
The main change that stands out to TBR is the reorganization of products and brands and the resulting impact on the client’s marketing and engagement with consumers. Lam noted that the platform is the same at its core but enables brands to create their own baseline metrics, identify areas of highest engagement, and retain their differentiated qualities.
 
This engagement is a strong use case for HCLTech’s AI-driven operational model transformations and the need for consistent, personalized experiences. It showcases HCLTech’s expertise beyond technology implementation and into talent strategies, including development, simplification, optimization and change management. Emphasizing these capabilities strengthens HCLTech’s position as a trusted AI partner by focusing on talent transformation and optimizing operations so clients can fully benefit from AI, starting with the operating model.

Conclusion

According to TBR’s Digital Transformation: Digital Marketing Services Benchmark, “As one of the most mature components of digital transformation, customer experience continues to push buyers toward omnichannel programs that unify data, workflows and engagement across the customer life cycle.”
 
HCLTech has quickly advanced experience solutions and created customer and employee journeys through its portfolio to capitalize on the demand outlined above. Focusing on cohesive strategies that work together removes friction and increases the value of insights and data through standardized approaches and frameworks. Lastly, HCLTech highlights the value of its change management portfolio, which optimizes talent structures and facilitates the adoption of AI tools to shift toward higher-value services attached to AI-led transformations while securing client relationships.
 
HCLTech’s ©Human Intensity Reduction Index (HIRI) has remained above its peer average as the company is diligent about staying on top of demand and avoiding hiring talent ahead of services needs. While HCLTech progressively embeds AI agents and leverages advanced tools internally to drive productivity, the company has not significantly increased its service volume with a similar amount of talent. Effective management of talent, including training and the addition of specialized skills, helps HCLTech bring in-demand services to clients and will lead to HIRI improvement.

Gemini for Industries: Context, Governance and the Changing Role of SI Partners

Throughout 2026, Google’s Gemini for business has evolved from a set of components to a unified solution for practical AI. Today, it is used by 90% of the Fortune 100 and has become the fastest-growing product in Google Cloud history. Two complementary pieces exist: the application — which is designed to be the “front door” for the workplace, drawing on context from Workspace as well as other productivity apps (e.g., M365, Slack) — and the platform for building, customizing and operating AI. New FinOps capabilities and the inclusion of the Antigravity harness in all  subscriptions are recent examples of how Google Cloud is addressing both sides of the portfolio, unlocking a strategic flywheel where Gemini creates demand and fuels usage of the Gemini platform. If Google Cloud can effectively deliver both as part of a unified solution, helping customers combat agent sprawl while staying true to its roots of openness and flexibility, it will take a big step to address one of AI’s central challenges: how to translate capable AI models into something that can scale at enterprise levels. 

Reshaping context

Context holds the power to shift the market from AI that assists to AI that acts by connecting to enterprise data and systems. This helps explain why nearly all vendors —SaaS, PaaS and IaaS players alike — are touting themselves as the context layer for agent systems. But what many vendors have yet to address is that context is more than a technical integration and will rarely be confined to a single stack.
 
With Gemini for Industries currently in preview for legal and financial services, Google Cloud is changing the narrative of what context really means. It views context as more than just a set of Model Context Protocol (MCP) servers connecting to trusted data — though those secure MCP connectors are critical for ensuring that agents respect existing entitlements, keeping licensed data licensed and permissioned data permissioned. True context is also access to a broader set of methods, rules and skills relevant for a unique set of workflows.
 
With the Gemini architecture, Google Cloud can deliver this context in a unified way, letting developers build agents that extend to the business through the application. If partner execution is successful, combining industry knowledge with governance access to enterprises systems could offer a confidence boost to enterprises looking to deploy AI agents in production.

The role of partners

Gemini for Industries revolves around three core principles: skills, security and governance, and partners. The skills side of the equation is supported by forward-deployed engineers (FDEs) that cobuild alongside clients. For instance, in legal, elite law firms are moving beyond merely adopting software to actively co-building these solutions as seen in Google Cloud’s newly announced collaboration with Cooley to develop capabilities for complex litigation. It is also being supported by a growing set of out-of-the-box capabilities like the Financial Research agent that offers full explainability and over 50 foundational skills.
 
Meanwhile, security and governance stem from secure MCP integrations with more than a dozen enterprise platforms and industry data sources (e.g., Moody’s, S&P Global).  Successful partners will bring both together and make Gemini deployable.
 
These vendors may claim different levels of industry expertise that complement Gemini, but their commitment to the platform is better reflected in internal adoption. Google reports the number of seats adopted by services partners grew 9x year-to-year. This suggests there is strong app adoption among partners and an overall willingness to experiment with agents, but the real test will be which SIs can rally around the platform, building and governing in ways that elevate client value at a time when agent stacks slowly absorb traditional SI-type work.
 

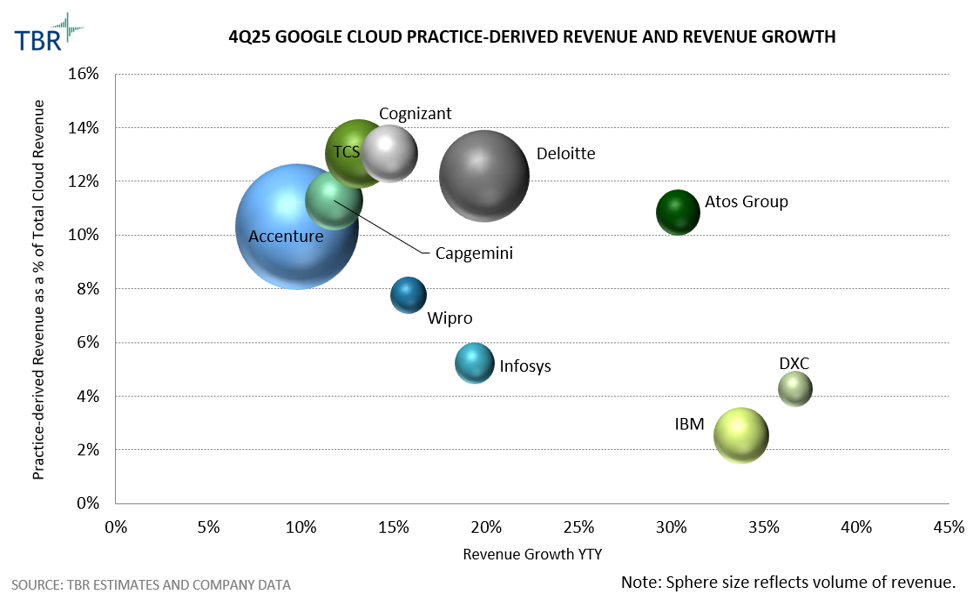
Graph: Google Cloud Practice Derived Revenue and Revenue Growth_4Q25 TBR

4Q25 Google Cloud Practice Derived Revenue and Revenue Growth (Source: TBR)

Industry is the accelerator, but governance is the differentiator

Deep industry expertise is essential to delivering client results, but it is becoming less of a point of differentiation among SIs. Gemini for Industries will test partners’ ability to deploy the right skills and, more broadly, will also test how effectively they can extend unique governance frameworks through their use of Gemini internally to clients.
 
More specifically, with agent identity (e.g., Gemini’s new “co-worker Workspace profile), SIs’ role in governance becomes increasingly real and more urgent as they now need to manage how these autonomous identities interact with business workflows, and do so securely.
 
More broadly, as federated retrieval, industry connectors and out-of-the-box agents, the governance opportunity for SIs starts to shift from governing each source to governing how the context across these sources is combined and used.

Systems integration or systems configuration?

By delivering a common platform for operating agents post-deployment, Google Cloud may help guide the shift to where many SIs are already heading: using implementation and integration as a loss leader with the end goal of driving more managed services.
 
Highlighting the urgency of the shift, a use case was just announced at Gemini at Work. It highlighted how On used Gemini to migrate 24 microservices; an external vendor reportedly quoted $500,000 for a component of the work, and On was able to complete the project without outside implementation resources.
 
With scenarios such as these, it remains to be seen how much foundational services revenues SIs can retain, but prebuilt solutions enabled by agents may be a catalyst for managed services with human in the loop for last-mile, high-value tasks.

Trust at Speed: EY’s Mobility Practice Is a Catalyst for AI-era Workforce Transformation

Earlier this year EY hosted more than 250 people from over 115 companies and 20 countries at the EY Global Workforce Conference in Rome. Over three days, TBR spoke with EY leaders such as Gerard Osei-Bonsu, Global People Advisory Services Tax leader; Maureen Flood, Global People Advisory Services Tax partner; and David Rooney, EY Germany partner, as well as human resources leaders from large and small companies and representatives from EY’s technology partners. The following includes details from the event as well as TBR’s ongoing analysis of EY, people advisory services, and consultancies.

Speed and trust anchor EY’s Mobility growth opportunity

Speed and trust equal momentum. From the opening presentation through every main-stage speech, panel discussion and breakout, EY leaders repeatedly came back to this formulation to reinforce the event’s core message: In an AI age, trust separates good from bad, success from failure, adoption from resistance. EY’s own research supports this formulation. The firm’s 2026 Mobility Reimagined Survey found that “high-trust mobility functions are 1.9 times more likely to report speed in deploying to new markets, 1.7 times more likely to report speed in policy decision-making, and 1.6 times more likely to get significantly positive ROI from their mobility investments.”
 
Gerard Osei-Bonsu, Global People Advisory Services Tax leader, described speed as quicker answers and faster decisions allowing changes at speed, although many companies remain more reactive than proactive. He said building trust requires strategic integration, operational effectiveness and satisfying employee experiences, all rooted in reliable data and technology. And critically, “speed without trust fails.”
 
Osei-Bonsu’s framing of speed and trust informed seemingly every other EY professional’s presentation and resonated with the clients TBR spoke with during the event (as well as EY’s leaders’ remarks during the firm’s Global Analyst Summit, which was also held in May). A few EY leaders and EY clients described a plethora of unreliable technologies and vendors in the Mobility and People Advisory Services space that are generating uncertainty around policies, risks and AI.
 
This counterpoint to EY’s trust narrative creates, in TBR’s view, an excellent environment for EY’s global workforce strategy, connecting mobility, payroll, immigration, rewards, workforce planning and technology, to continue growing. As the trusted adviser bringing speed, reliability and governance, the practice should experience ongoing revenue acceleration and remain among the strongest components of EY’s tax, audit and consulting portfolios.

Microsoft remains the technology backbone of EY’s Mobility strategy

Echoing last year’s event in Barcelona, Spain, EY’s strategic alliance with Microsoft permeated many of the presentations, use cases and discussions, with EY professionals reinforcing that the firm’s Mobility solutions are, almost exclusively, built on Microsoft’s platform. EY’s mobility, technology and industry expertise, orchestrated on Microsoft’s platform, provides EY’s clients with improved employee experiences across a range of mobility issues and journeys.
 
Critically, according to multiple EY partners, the firm’s tight alliance with Microsoft enables faster innovation of both EY’s proprietary solutions and Microsoft’s platform. A Microsoft leader attending the conference summed it up as “cocreated transformation, built-on experience and developed trust.” An EY leader noted that the firm delivers services around data and AI “at speed and with trust” baked in, lending EY “credibility, global scale and proven outcomes” that peers and competitors would struggle to replicate. Osei-Bonsu noted that “none of us have the blueprints” for everything, making technology alliances critical to EY’s success. He added that within the Mobility space a diverse set of players and ecosystem partners rely on EY and Microsoft to provide a kind of “centrifugal, gravitational” force powered by EY’s combination of workforce expertise, data, governance, technology and AI-enabled delivery.
 
In TBR’s write-up of the event last year, our assessment of Microsoft as EY’s most-strategic partner included a hedge that “EY noted expectations that other technology alliance partners, including ServiceNow, will become increasingly strategic to Mobility.” Discussions in Rome show Microsoft remains EY’s predominant technology alliance partner, perhaps even more so than a year ago, leading TBR to believe the EY-Microsoft partnership continues to underpin Mobility and provides a client-zero use case EY can share with clients as well as an example, within EY, of the advantages of partnering tightly and nearly exclusively with a technology provider like Microsoft.
 
TBR continues to see Mobility and People Advisory Services as catalysts for change within EY, further evidenced by Microsoft’s role in the Mobility practice. (Note: In May EY and Microsoft announced a $1 billion-plus, five-year initiative, including integrated EY teams and Microsoft forward-deployed engineers focused on scaling enterprise AI.)

EY brings CHROs deeper into M&A by connecting people, tax and technology

In an M&A-focused breakout session, Flood and EY colleagues discussed challenges around including talent management within a typical M&A process. Flood commented that human resources leaders often get left out of the loop during due diligence, potentially lowering the value of an acquisition (by increasing onboarding and assimilation expenses or failing to see red flags), echoing a sentiment TBR has heard from chief technology officers and IT directors lamenting the costs needed to fit an acquired assets technology into an existing environment.
 
On a positive note, Flood said the chief human resources officers (CHROs) at EY’s clients more frequently have a seat at the M&A table for workforce value creation and workforce integration, although typically only at companies already focused on changes to their people and organization, not just their tech. In TBR’s view, EY has a well-established brand around M&A and, notably, divestitures, and can leverage that experience and credibility to consult around the people aspects, not simply the technology and financials.
 
The firm’s HR Mobility Tax practice, for example, can play a more significant role in transaction evaluation and due diligence, provided EY’s clients fully appreciate the breadth of EY’s services beyond traditional M&A. In TBR’s view, greater adoption of AI by EY and the firm’s clients will, because of the transparency-enhancing nature of AI, accelerate broader consideration of human resources challenges and opportunities during M&A engagements, boost exposure and boost revenue for EY’s Mobility practice. CHROs will not make the final purchasing decisions, but EY will help them to increasingly be expected at the table.

Payroll software: EY’s Trojan horse for scaling IP

In a special session with TBR, Sheri Sullivan, Global Payroll Operate leader, and EY professionals discussed EY’s bet on developing a software platform designed to “demystify” payroll. Sullivan explained that humans frequently serve as the bottleneck in payroll processes, creating an opening for a trusted, auditable AI-enabled solution. With multiple trusted and accurate data sources, AI can generate useful payroll analysis and manage payroll systems.
 
As customer zero for the software, EY has been learning the limitations and seeing the benefits, all of which Sullivan and her team have begun to bring to clients. As of the Rome conference, EY’s client list for this AI-enabled product remains small, and the firm continues to test different commercial models, with the expectation scaling would begin in earnest before the end of 2026. In TBR’s view, even a relatively small client base and modest revenue stream from a payroll services platform could be significantly disruptive within the firm and the market.
 
While learning to perfect selling software from within a professional services firm, the payroll practice could be demonstrating to other parts of EY how to adopt, transform and monetize IP. TBR recognizes EY has been in the software-selling business for a couple of decades, but not at scale and not in the AI age. If that were to change, payroll services would be a likely catalyst. Across the broader market, every single company runs payroll. A trusted services provider, with a legacy brand around audit, tax, governance and risk, and enabled by proven AI, could displace smaller competitors, particularly among large clients that already work with EY. In short, TBR looks forward to hearing soon that EY’s global payroll services practice has become the firm’s fastest-growing revenue line.
 
One critical aspect of this event, as noted by TBR in previous years, has been EY’s near refusal to sell itself or ask attendees to explicitly describe their experiences and relationships with EY.
 
But EY did not present this capability as a customer-zero use case that clients could buy. Instead, EY partners stressed that the firm focused on Mobility as having evolved beyond logistics to include talent development, upskilling and adjusting the entire firm to new skills demands: Mobility within EY as part of improving the firm (and quietly conveying to clients “You could do this, too.”).

EY turns trust into an advantage in an uncertain workforce technology market

EY’s 2025 Barcelona message aged well, but in TBR’s view, mobility has progressed from being human-centric and tech-enabled to trust-dependent, AI-scaled and demonstrably business-critical. EY can increasingly combine employee experience, managed services, regulatory expertise, and its deepening alliance with Microsoft to demonstrate that trusted data and AI can deliver measurable outcomes in this space.

TBR walked away from the event with five themes:

  1. The need to connect Mobility within a company to the company’s business overall echoed a decade-plus of consulting advice to CTOs and IT directors to be part of the business and not simply a cost center. EY has been hammering home the lessons learned from those technology consulting engagements and helping CHRO and tax executive clients become better internal business partners.
  2. AI is a tool, not an answer. The week prior to the Rome conference, TBR attended EY’s Global Analyst Summit in New York and heard repeatedly that AI serves a purpose in an organization but cannot be the answer to every business problem, despite the relentless hype since the release of ChatGPT. As a firm, EY has a compelling and mature AI message.
  3. Unreliable technology, too many vendors, and growing uncertainty in the Mobility and broader People Advisory Services space open tremendous opportunities for a trusted, proven Mobility provider, such as EY. And in Rome, it was not just EY leaders making the case but also clients. During one breakout session poll, only 47% of respondents said their technology platforms are “reliable.” The opening for EY is clear.
  4. An EY software solution for payroll could significantly disrupt the payroll services market while helping EY overall become more adept at running a software practice within a professional services firm. TBR has seen some of EY’s peers fail at precisely that challenge, but EY’s leaders in this effort spoke knowingly about the mines scattered across the space while also bursting with passion for solving payroll problems with an EY software tool. Watch this space.
  5. Immigration issues show no signs of abating in 2026 or beyond, providing more opportunities for EY to bring a mix of tax and consulting services to a growing number of clients. Several conference sessions highlighted immigration’s role in enabling access to talent, supporting workforce strategy and navigating future workforce challenges. As AI threatens to upend employment across a number of tech jobs typically associated with low-cost locations at the same time enterprises realize they lack much needed in-house AI talent, immigration challenges may morph in new ways, boosting demand for a trusted adviser.

EY remains ambitious about its revenue targets for People Advisory Services, and TBR’s assessment from 2025 still rings true: “Companies keep recruiting, hiring, paying, rewarding, moving, repatriating, retiring and hiring in an endless loop … [so] absent the worst possible global political and economic scenarios, including a drastic curtailment of global mobility, TBR believes that ambition is perhaps a bit too modest.”
 
Technology and macroeconomic trends favor EY’s Mobility practice. Perhaps just as significantly, so do trends across professional services, including AI adoption, business model disruption, commercial model shifts, and an all-around recognition that the largest consultancies need to change to meet clients’ changing demands and AI-enabled expectations. For the last three years, TBR has heard from both EY leaders and EY clients that the firm’s Mobility practice is already a catalyst for that change.

5G’s Next Act Is About Monetization, While 6G Builds on the 5G Foundation

5G moves from coverage to economic discipline

The telecom industry is entering a more disciplined phase of mobile network investment. Much of the early 5G buildout in developed markets is complete, and operators are now prioritizing capacity, efficiency and monetization over nationwide coverage. TBR expects global communication service provider (CSP) investment in 5G infrastructure to grow only incrementally, driven primarily by fixed wireless access (FWA), 5G-Advanced and 5G standalone (SA), while initial commercial 6G deployments could begin as soon as 2029. The transition is an evolution as operators seek to extract more value from existing 5G assets while preparing those same networks to support 6G.

FWA leads, but 5G SA remains the monetization bottleneck

FWA remains the clearest source of net-new 5G revenue. According to Ericsson’s June 2026 Mobility Report, there are 175 service providers globally offering 5G FWA, and TBR projects more than 400 million residential and commercial premises will be covered by 5G FWA by the end of 2029. FWA subscriber growth is prompting operators to add dedicated capacity, spectrum and network optimization as the excess mobile capacity that supported early FWA deployments is consumed.
 
The larger challenge is 5G SA. Of approximately 390 CSPs with commercial 5G, only about 90, or 23%, had launched 5G SA as of June 2026. This slow migration limits operators’ ability to monetize new capabilities such as network slicing, RedCap (Reduced Capability) and ultra-low-latency services. Commercial slicing is expanding into premium mobile, public safety, FWA, transportation and live events, but direct revenue remains minimal as most services are bundled into higher-tier plans.

5G-Advanced and AI-RAN create a bridge to 6G

Rather than triggering another broad hardware replacement cycle, 5G-Advanced will emphasize software, Massive MIMO and AI-enabled optimization. For example, AI for RAN is emerging as the first commercial AI-RAN opportunity, using AI to improve channel estimation, beam management, traffic forecasting and energy efficiency. Most deployments remain proofs of concept or field trials in 2026, with initial commercial deployments expected in 2027 and more meaningful vendor revenue beginning in 2028 and beyond. Nokia estimates AI-RAN could improve spectral efficiency by more than 2x by 2028.
 
These investments also establish the technical foundation for 6G. 3GPP (3rd Generation Partnership Project) Release 20 standards, expected in 2027, will continue 5G-Advanced development while studying 6G architecture, spectrum, AI integration and integrated sensing and communication (ISAC). 3GPP Release 21 is expected to establish the first formal 6G specifications, with final protocols in March 2029. TBR expects 6G to rely heavily on software upgrades to existing 5G radio and core infrastructure, supplemented by new spectrum, radios, accelerated computing and edge infrastructure.

6G broadens the operator opportunity beyond connectivity

The most important 6G shift will be commercial, not generational. ISAC can turn communications networks into sensing platforms capable of identifying location, velocity, elevation and moving objects, creating opportunities in drone detection, border security, transportation, industrial automation and emergency response. Importantly, operators do not need to wait for 6G as usable ISAC solutions can leverage 5G-Advanced and 5G core, with trials already underway and commercial deployments expected to begin in 2027.
 
National security could become an especially important catalyst for 6G as governments seek better ways to monitor lower airspace, where drones can evade traditional radar systems. ISAC can reuse much of the existing cellular infrastructure, including sites, spectrum, transport and some radios, but applications such as drone detection will require better elevation-domain coverage and investments in beamforming, sensing software, signal processing and edge computing. This creates incremental RAN investment opportunities while potentially allowing operators to monetize sensing data alongside distributed AI inference, network intelligence and APIs.
 
The commercial model remains uncertain. CSPs could operate sensing services themselves, while governments and militaries may deploy private ISAC systems that are at least partly co-located with commercial networks. Either model expands telecom infrastructure beyond carrying traffic toward networks that can also observe and interpret the physical environment.

TBR perspective: 6G will reward operators that finish the 5G job

TBR believes the path to 6G runs directly through unfinished 5G work. Operators that expand 5G SA, improve spectrum efficiency, commercialize differentiated connectivity and build programmable, AI-ready networks will be better positioned for an economical 6G migration. FWA will remain the near-term revenue anchor, but longer-term value will increasingly depend on whether CSPs can turn AI, sensing and network capabilities into standardized services that enterprises and governments can easily buy. The transition to 6G is about proving that operators can finally monetize the capabilities 5G was designed to enable.

Exploring KPMG’s Role in Quantum

In July KPMG hosted its 9th annual Tech and Innovation Symposium in Deer Valley, Utah, attended by more than 100 technology and business professionals, politicians, academics, KPMG technology alliance partners, KPMG professionals and a handful of analysts, including TBR. Three days of discussions, breakout sessions and informal chats covered AI, the space economy, quantum, cybersecurity, workforce transitions, the NBA, geopolitics and more. This is the second in a series of blogs focusing on specific elements, discussions and/or insights TBR noted during the event.

The urgency around quantum computing

“So right now, our quantum computers work … they do all the stuff that a regular computer does. They even show potential in many areas where we can demonstrate speed up, but we cannot justify an ROI with the existing quantum computers, and no one else can.” — Subodh Kulkarni, President & Chief Executive Officer, Rigetti Computing, during a panel discussion at the KPMG Tech and Innovation Symposium
 
If the hype around AI was a bit subdued this summer compared to last year’s event (see the first blog in this series), the urgency around quantum computing more than filled the gap. KPMG US CEO Tim Walsh’s initial question after the first expert speaker related to quantum. The opening breakout session for industry analysts, including TBR, focused on quantum, led by KPMG’s Aaron Kemp, senior director, Quantum Research, Enterprise Innovation. TBR found KPMG’s quantum message compelling, and maybe a touch frightening across three specific areas: post-quantum cryptography (PQC); quantum advisory; and quantum today, which, as the quote above makes clear, is here now.

Quantum’s disruption potential

“We received an RFI that really caught us caught us off guard about five years ago, asking a lot of deep questions about the coming PQC migration, what it was going to take for an organization to do that. We started looking at how are we going to answer those questions for our clients. PQC is obviously extremely complicated.” — Aaron Kemp, KPMG Senior Director, Quantum Research, Enterprise Innovation, during a panel session
 
In a discussion with TBR and during a couple of panels, Kemp stressed the massive disruptive potential of PQC. Likening the challenge to Y2K, he said IT services companies, consultancies and niche technology vendors would likely see huge opportunities in preparing for and then mitigating against the fallout from post-Q-day cybersecurity challenges. In TBR’s ongoing research and analysis of the U.S. federal sector IT services players, IBM, General Dynamics Information Technology, Booz Allen Hamilton, Accenture Federal Services and Leidos have been concentrating heavily on post-quantum cryptography, cryptographic agility, inventory and remediation services and quantum-safe networking. Even with those efforts focused on government buyers, the activities and investments by companies with significant commercial sector clients (such as Accenture and IBM) prove smart money has positioned for PQC opportunities.
 
During a panel discussion, Barak Bussel, co-founder of 7i Capital and board chair of the UCLA Center for Quantum Science and Engineering (CQSE), said, “We no longer can rely on the old kind of cryptography and the old encryption paradigms. We chatted about this before. We don’t use Enigma anymore. I mean, it’s a different world, and now it’s time to kind of migrate away from, you know, problems of factoring large numbers to a new kind of encryption methodologies that will take us to the next step.” Every panelist, and maybe every attendee at the Symposium, seemed certain that PQC and all that comes with it are frighteningly close.
 
“It’s estimated there’s 16,500 quantum researchers on the planet. When we separate those into the organizations, where does that talent come from, and how do you stay strategically aligned with quantum, the GPUs, AI, as we kind of move into this new paradigm of compute?” — Aaron Kemp, KPMG Senior Director, Quantum Research, Enterprise Innovation, during a panel session
 
According to Kemp, KPMG’s Quantum Advisory practice will focus on Fortune 200 companies, which will likely invest in their own quantum computing capabilities. In discussing this strategy with TBR and other analysts, Kemp noted the dearth of quantum talent, an assessment he echoed the following day during a panel discussion. To address that challenge, KPMG has been training professionals, particularly in the cybersecurity practice, on quantum capabilities and KPMG’s offerings.
 
The firm has also been advising clients on the near-term steps they can make to prepare for Q-day as well as for the business opportunities quantum computing will create in other sectors, such as academic research, government and life sciences. Kemp described a coming “massive opportunity” to retire technical debt, get rid of duplicate software licenses, clean up data, and streamline IT and cybersecurity within an enterprise — efforts KPMG can address with expertise and experience. In TBR’s view, KPMG’s quantum advisory story meets the moment: urgent, practical and preparing for an uncertain, but unquestionably disrupted, future. One nagging question remains for TBR: Is the rest of KPMG ready for quantum?

An analyst’s perspective: the calm before the storm

From my colleague, Principal Analyst Boz Hristov:
 
“PQC is a must-have discussion and investment, given the move to all-things-are-digital and especially the rise of digital currencies. We know blockchain solves for some of the cryptographies, but there are some strong, powerful quantum computers that could reverse the public keys to steal private ones and really defy the idea of blockchain. Given KPMG’s role in the financial services world — across its entire stack of offerings (tax, audit, consulting) — the firm needs to think about how to be part of the solution. Possibly the PQC play, which, in a perfect world, could battle bad actors and help blockchain-based crypto exchanges survive. Lots of GRC [governance, risk and compliance] opportunity here, no doubt. The challenge with PQC is that it can be expensive and very data heavy, making blockchain ledgers slow down and ultimately raise transaction fees. Migration hurdles can be another challenge as users would need to more often move to quantum-safe addresses.
 
“What is the expected play? The good-old hybrid playbook usually helps: develop and run PQC standards that run on classical computers but resist quantum decryption. Although this may not be the state KPMG’s quantum professionals want to operate in, it would be the cheaper option when it comes to scaling. Quantum is exciting, and there is huge potential, but firms like KPMG need to avoid turning it into another blockchain where a technology was looking for a problem to solve. TBR’s December 2025 Digital Transformation: Voice of the Customer Research ​noted 15% of buyers procured quantum to support their digital transformation [DT] programs in 2025, down from 18% in 2024. Since we started conducting the survey seven years ago, quantum has continued to be in the bottom half of the tech enabling buyers’ DT initiatives: not disappearing but also not top of mind. The complexities of the tech might make current buyers even more uneasy, and I think generative AI has given them plenty of change management challenges. Perhaps the generational shift at the buyer side really needs to happen before quantum picks up steam. In the meantime, KPMG has an opportunity to educate and prepare its clients. May have to do some pro bono work. But if the timing is right, it could be KPMG’s Y2K moment in terms of its relationship with IT buyers.”
 

Technologies Purchased for Central Digital Transformation Initiatives

Technologies Purchased for Central Digital Transformation Initiative (Source: TBR)

Be curious

“Quantum’s been five years away for 30 years. Quantum is here. We’re actually working in it. So start looking into where it’s applicable in your organization. What’s going to drive for mandatory migrations, governance, but also what you do with it? And then be curious, which we’ve talked about this whole event. We don’t have a lot of algorithms yet. We don’t have a lot of ideas of what we can do with these. We talked yesterday about we’re going to give these to 18-year-olds with no biases of how computers work, and we’re going to see things we’ve never seen. So inspire your people to poke at it, to understand what’s going on. Get on, play with the free minutes that everybody can get, and accept that this is coming and is going to be part of our strategies going forward.” — Aaron Kemp, KPMG Senior Director, Quantum Research, Enterprise Innovation, during a panel session
 
During the discussion with analysts and on various panels, multiple quantum professionals extolled the idea of quantum computing operating alongside traditional and high-performance computing (HPC), allowing enterprise clients and others to select the best compute power and engine for the task. With TBR, Kemp mentioned IBM’s new data center combining HPC, Watson AI, and quantum computing as a model for helping clients use a “what fits, rather than a one-size-fits-all” approach. Kemp also said (maybe lamented?) that “quantum-enhanced solutions” are possible today, but the focus among quantum practitioners remains the hard problems only quantum may be able to solve, instead of the near-term practical uses.
 
During the larger panel discussion, as reflected in the quotes, the panelists described the current state as progressing faster than expected and delivering value, potentially, when paired with traditional computing capabilities. Pulling all the threads together, KPMG has positioned itself as ready to help clients prepare for when quantum shifts from an expensive idea to an immediate opportunity and threat. Can the firm create near-term revenue as PQC meets its Y2K moment, provide reliable and useful services through hybrid computing, and manage the ecosystem and orchestration layer in quantum? Maybe. At scale with clients? Likely. Are KPMG’s clients really ready for that? Are all of KPMG’s partners, principals and directors? Let’s see.
 
TBR doesn’t have quantum experts, and we don’t pretend to understand the physics. But we do understand business models and consulting. And KPMG appears to be in the right place to bring quantum value to its clients while expanding the firm’s reach, revenues and retention.

Holiday Shopping Is Becoming an AI Story: How Value-conscious Consumers, Rising Memory Costs and Connectivity Are Reshaping Retail

Consumers are spending, but value is winning

The 2026 holiday season is shaping up to be strong on paper. Mastercard Economics Institute expects U.S. retail sales, excluding automobiles and gas, to grow 5.5% year-to-year from Nov. 1 through Dec. 24, while Bain forecasts holiday sales will exceed $1 trillion for the first time. Yet the headline growth masks a more cautious consumer. Forbes reports that 31% of shoppers expect to increase their holiday budgets, but 53% of those spending more say that is because everything costs more, not because they have greater purchasing power. Bain similarly points to inflation, low savings and elevated credit card delinquencies as pressure points influencing spending decisions this holiday season. The result is a shopper willing to spend but increasingly focused on value.

AI is the new holiday shopping assistant

The search for value is accelerating consumer adoption of AI, as AI tools are seen as a means to more effectively locate and pursue greater value with purchasing decisions. Forbes reports that nearly two-thirds of U.S. shoppers expect AI to influence at least 30% of their holiday spending, with deal-finding, product comparisons and retailer selection among the leading use cases.
 
Bain found that 24% of online shoppers expect to begin their holiday search on generative AI platforms, up from 17% in 2025, while another 13% plan to use retailer-owned AI shopping agents. This demonstrates that consumers are lowering their caution around AI usage, as previously skeptical users are more willing to experiment with AI tools in the name of cost savings.
 
Additionally, Mastercard found that AI users tend to shop across a broader set of merchants and spend earlier in the holiday season. AI is therefore becoming an intermediary between consumers and brands. Though humans remain involved as the decision makers, AI enhances and extends the shopping experience to new brands, new shopping platforms and potentially new products.

The hidden cost of the AI shopping boom

The irony is that the same AI adoption helping consumers find value is increasing costs in consumer products such as electronics. Hyperscalers, neoscalers and neoclouds are accelerating AI infrastructure investment, increasing demand for ever-scarcer key memory and components, thus driving up these costs. Suppliers are prioritizing scarce capacity for server DRAM, high-bandwidth memory and enterprise storage, tightening supply for consumer applications. This dynamic will keep memory prices elevated and will continue to result in higher component costs for consumer electronics.
 
For retailers, AI can improve personalization and customer service, but the infrastructure required to deliver those capabilities comes with a rising cost.

Higher device costs add another holiday spending pressure point

The AI infrastructure boom could also reach holiday shoppers through higher smartphone costs. AI server demand is contributing to higher DRAM and NAND prices, and smartphone manufacturers have little appetite to absorb those increases, potentially pushing more costs to consumers at a time when value remains a priority. This creates a challenge for U.S. mobile network operators, which rely heavily on device promotions to drive upgrades and switching. The carriers still offer substantial smartphone discounts, but many of the largest offers require trade-ins, qualifying plans or new lines, with savings delivered through multiyear bill credits.
 
As device prices rise, holiday shoppers may delay upgrades or depend more heavily on financing and promotions, forcing operators to balance consumer affordability with the cost of more expensive device subsidies. The holiday quarter remains an important device sales period for U.S. operators. Consumers that are stretching an inflation-affected budget for the 2026 holiday season may find themselves delaying upgrades, especially if device prices increase further due to component cost growth.
 
Additionally, higher component costs will likely limit U.S. operators’ ability to discount as heavily as they have in years past.

Connectivity turns AI investment into a retail experience

As retailers invest more heavily in AI to capture increasingly value-conscious holiday shoppers, the effectiveness of those investments will depend on the infrastructure supporting them. AI recommendations, computer vision, mobile point-of-sale, real-time inventory and in-store personalization only create value when data can move reliably between devices, stores, edge systems and cloud platforms.
 
A 2026 Verizon Business study found that AI and machine learning applications are driving 67% of retailer network upgrades, while only 39% of retailers are satisfied with their edge computing support. Verizon is positioning 5G Business Internet and private networks for these workloads to address the gap in satisfaction.
 
AT&T’s Connected Spaces combines connectivity, edge infrastructure and Azure AI for environments including retail, and its collaboration with AWS connects fiber and 5G directly to cloud environments for business AI workloads.
 
T-Mobile similarly positions 5G, IoT and advanced network solutions for inventory management, mobile point-of-sale and computer vision. In this sense, connectivity becomes part of the same holiday spending story as retailers may compete through AI-enabled experiences, but networks ultimately determine how reliably those experiences reach consumers.

The holiday shopping cart now reaches back to the data center

Holiday shopping is becoming a useful snapshot of a much larger technology cycle. Consumers, who have been continuously squeezed by inflation for years, want better prices and more personalized experiences. Retailers are turning to AI to deliver both, and AI is driving investment in compute, memory, edge infrastructure and networks to support this shift in demand.
 
The connection from a shopper asking an AI assistant to find the best gift to a retailer’s cloud infrastructure, memory procurement and store connectivity may not be visible, but it is increasingly direct and essential as customers have higher expectations for seamless and positive customer experiences. For telecom operators, that makes retail AI more than an application trend. It is another reason reliable fiber, 5G, edge computing and resilient enterprise connectivity are becoming part of the commercial infrastructure behind everyday consumer experiences.