AI Adoption Predictions: What Will Determine Vendor Success and Who Is Positioned to Win

Specialization around partner technologies and platforms along with industry expertise will steer portfolio developments over the next five years. Although growing AI adoption will lead to greater demand for integration, orchestration and managed services, it will challenge the traditional labor-based revenue models and push vendors to decouple revenue growth from headcount.
 
The shift toward outcome- and platform-based delivery will accelerate vendor consolidation, concentrating market share among providers that can demonstrate measurable ROI and scalable IP-led offerings. These dynamics will be amplified by industry-specific demand, especially in the manufacturing, energy and public sector verticals, where transformation investment and regulatory pressures will outpace market growth and benefit vendors with deep domain expertise and digital engineering capabilities.
 

Watch TBR Insights Live webinar on demand: “IT Services Market Outlook: Forecasting Growth, AI Impact and Competitive Shifts Through 2030”

The next wave of AI

Physical AI will emerge as the next AI frontier, driven by cost-optimization needs in the underperforming manufacturing and industrial sectors. Surging energy demand from AI data centers will create a parallel growth opportunity. The expansion of task- and industry-specific agentic AI in 2025 will enable broader orchestration as enterprises streamline fragmented deployments, generating greater demand for data orchestration to unify enterprise data and maximize AI performance.
 
As physical AI scales, tighter integration between OT and IT systems will become critical, creating opportunities for vendors with combined digital engineering, IoT and AI capabilities while increasing activities around cybersecurity and real-time data orchestration.

Governance and data accountability

As companies increasingly rely on advanced AI to inform decision making, CxOs are scrutinizing governance and the quality of underlying data. In the second half of 2026, TBR anticipates advanced AI spending will partially pivot to governance and accountability frameworks, accelerating engineering and IT consulting engagements to optimize and clean data.

Consulting rebound

Persistent changes to the supply chain due to new and ongoing conflicts in Europe and the Middle East as well as shifting tariffs, immigration issues and compliance requirements will lead to a rise in consulting, as clients realize geopolitical and macroeconomic uncertainty are longer-term than perhaps initially anticipated. IT services companies will continue to build out supply chain consulting, supply chain optimization and analytics capabilities.

Cybersecurity becomes an essential foundation for AI

Rising geopolitical tensions, which are driving European governments to adopt stricter cybersecurity policies and increase investment in sovereign solutions, are creating major short- to mid-term opportunities in infrastructure services and, subsequently, IT consulting. If these concerns persist over the long term, Europe-based enterprise clients may be less willing to work with companies outside the region.
 
Cybersecurity and sovereign solutions will support AI adoption, as secure data, applications and infrastructure emerge as key concerns for the public sector and, subsequently, for heavily regulated industries in Europe such as financial services. EMEA accounted for 34% of revenue in 2025 in TBR’s 4Q25 IT Services Vendor Benchmark, which tracks 30 leading IT services providers.

The rise of local market in APAC

TBR has noted an ongoing uptick in demand for digital transformation and IT modernization in APAC, which is expected to accelerate as internet adoption increases in Southeast Asia and India’s gross national income rises. India-centric vendors stand to gain from the increase in demand for these services due to their unique ability to compete on price and strong local presence.
 
Further, companies that have lost market share with the introduction of new technologies such as AI and advanced AI, such as Wipro, have the chance to capitalize on more traditional services.

Measurable outcomes become a necessity in the U.S. federal sector

Through the end of 2028, U.S. federal spending will be centered on national security and modernization, with demand for AI, cyber solutions and mission software. From 2026 to 2028, providing tangible results and adapting quickly to new efficiency initiatives will be necessary to secure new deals in the U.S. federal space.

Contracting market share of the top 5 IT services providers signals that scale alone is insufficient as AI enables smaller providers to compete in higher-value services

Although the top five IT services providers will continue to increase revenue, TBR estimates their combined market share will contract through 2030. This reflects intensifying competition from midtier, regional and specialized providers across the IT services landscape, particularly as AI lowers barriers to entry and enables more targeted outcome-based offerings. Leading IT services providers must rely on differentiation through AI-led platforms, large-scale transformation capabilities and ecosystem orchestration to defend their share against a long tail of increasingly capable competitors. As clients prioritize ROI and accountability, IT services providers must deliver tangible value from AI-led transformations to sustain revenue growth and retain market share.
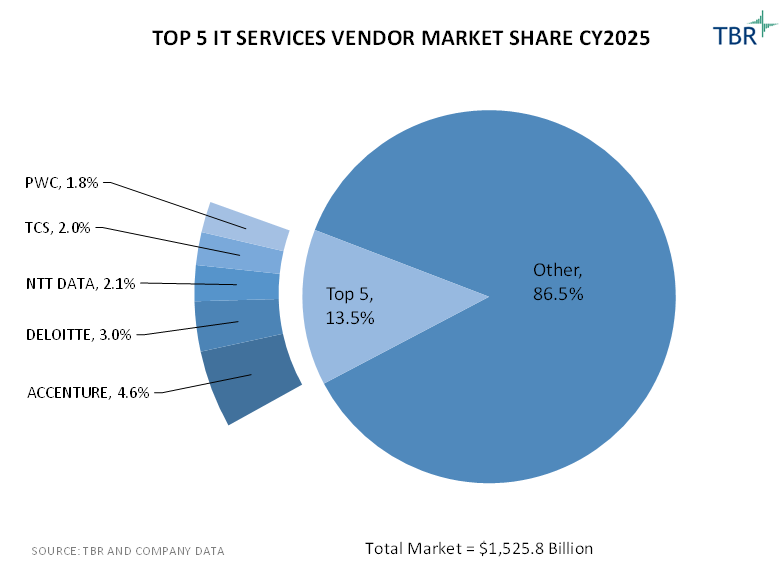
 

Top 5 IT Services Vendor Market Share for 2025 (Source: TBR and Company Data)
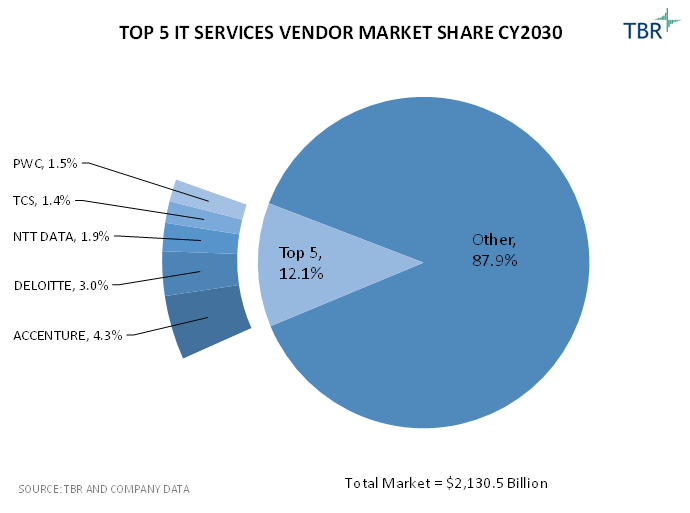


Top 5 IT Services Vendor Market Share 2030 (Source: TBR and Company Data)


Although the IT services market will expand steadily, changing delivery models and client demand will redefine how value is created

TBR’s IT Services Market Forecast is a comprehensive, forward-looking analysis of the IT services market and includes analysis of the market share of leading IT services vendors and competitive and customer dynamics that are driving revenue growth.
 
This research includes estimates for the size and growth of the overall market and by two segmentations, Consulting & Systems Integration and Rest of IT Services, which includes business process outsourcing, IT outsourcing, applications outsourcing, and hardware support and maintenance services. Current-year market sizing and a five-year forecast across the two services segments are featured in each publication, as well as analysis of growth drivers, top trends and leading market players.
 
The first publication of this annual report is now available. Click here to Learn how you can access the full research and all supporting data.
Can the Big 4 Leverage AI to Capture Midmarket Opportunity?

The Big Four Firms can harness AI to disrupt smaller consultancies by moving down market to capture medium-sized enterprises — at least, that’s the theory

If Deloitte, EY, KPMG and PwC enable AI at scale within their own organizations, they should be able to successfully compete with firms like Grant Thornton, Protiviti and Kearney for consulting spend by companies in the $500 million to $5 billion range. In almost 19 years of watching the Big Four firms operate, I’ve seen countless small- and medium-sized enterprises’ initiatives launch, falter and fade. AI promises to upend that track record and, finally, make these firms players in the midmarket.
 
Except it won’t, at least not any time soon. For starters, anyone who has seen enterprisewide AI adoption at scale knows that success, when it comes, comes in small, incremental steps, not as massive, business-model-altering change. AI implementation is harder than it looks, and AI adoption at scale requires time, tech, leadership, experimentation and change management.
 
The Big Four firms provide exceptional advice on adopting AI at scale and have become adept at helping clients on their AI journeys (“tell me what to do” and “do it for me”), but they’re not immune to the challenges all large organizations face. In fact, given their consensus-dependent organizational model, these firms might face higher hurdles than the average top-down decision-making company.

Change management is perhaps the biggest roadblock between the Big Four and the midmarket

Smaller engagements mean more clients, and although AI offers assistance, shouldn’t a midmarket client paying Big Four fees receive Big Four quality and service? Are the AI-enabled solutions equivalent to human expertise, and do they provide cost savings for everyone? TBR research says no to the latter, as digital full-time employees cost more than human workers, at least right now.
 
Until those midmarket companies aiming to become large global enterprises heed the advice of junior partners at Big Four firms, those partners are stuck cultivating, tending and harvesting more clients to close the revenue gap with senior partners. Do they get the chance to lead a major client like Citibank or be their firm’s global financial services lead by serving a local savings bank? No. Serious change management needs to happen within the Big Four, enabled by AI and specifically addressing the organizational, reputational, and compensational challenges of sustaining an investment in the midmarket. Do these firms have more on their plate right now? Yes. (Learn more in our Management Consulting Benchmark.)

With AI more difficult to adopt than expected and change management the bugaboo that never fades, a third element still exists in keeping the Big Four from significantly expanding in the midmarket: the competition

The “tier two” firms listed in the previous section and their peers bring three strengths that help keep the Big Four at bay:

  • Flexibility: Smaller firms can learn, adopt, deliver and sunset faster, making them more responsive to smaller enterprises’ highly specific needs. Where they trail in global scale, they lead in pivoting to meet clients’ shifting demands.
  • Talent: Consulting depends on relationships, showing up and being smart (maybe not in that order). “Tier two” consultancies have tons of “tier one” talent, including consultants recruited from Big Four firms, who sought more entrepreneurship, creativity and runway.
  • Trust: A mix of cultural affinity, affordable pricing and competence with long-standing relationships and midmarket clients makes the value of working with smaller consultancies easy to understand. These attributes make Grant Thornton, Protiviti, Kearney and their peers much harder to displace, even by AI-enabled solutions and more bots.

Do you think there are playbooks for Big Four firms to seriously disrupt the midmarket over the next five years? Do you think Accenture could be a wildcard here? Leave your response in the comments!


Who Will Win the AI Services Race in the Next Wave of AI?

This quarter, TBR FourCast looks at Accenture, Capgemini, HCLTech and IBM Consulting, comparing how their underlying data strategies, especially related to engineering and integration, prepares them for advanced AI adoption.

Anthropic, OpenAI and Palantir: Who Gains and Who Loses in the Federal Fallout

With the largest global IT buyer’s biggest priority — AI — on the line, the stakes could not be higher

The U.S. federal government is the largest single buyer of IT services in the world, making it a critical customer target for leading providers in the space. For the current federal fiscal year (FFY), U.S. federal IT spending is estimated to approach $130 billion. Within that umbrella of spending, the Department of Defense (DOD) is not only the largest driver of spend but is also expected to see the most significant spending growth, at an estimated 5% year-to-year. Cloud-delivered options have been increasingly important to the DOD, most notably with the $9 billion Joint Warfighting Cloud Capability (JWCC) contract in 2022 and the newest iteration of the vehicle, dubbed JWCC Next.
 
The shift to cloud continues, but AI has become the clear priority for the DOD’s large and increasing IT investments over the past six months. As outlined in TBR’s 3Q25 Federal IT Services Benchmark: “TBR believes federal agencies increasingly view AI as an essential technology for enhancing mission workflows rather than as a niche, specialized tool or tool set. As such, we anticipate broadly accelerating implementation of comprehensive, agencywide AI platforms in FFY26 and FFY27. FSIs [federal systems integrators] will be tapped to not only integrate AI into IT infrastructures but also develop secure and ethically sound foundations for AI adoption.”
 
All of this is a long-winded way of setting up just how important the recent developments between Anthropic, OpenAI and Palantir are considering the implications for the largest agency (DOD), within the single largest buyer of IT in the world (U.S. Federal Government), relating to the single largest technology priority (AI).

The downside of Anthropic’s position may have broad financial impacts

Anthropic took a firm stance that the DOD could not use the company’s Claude technology for mass civilian surveillance or in fully autonomous weapons. This position caused Anthropic to lose the contract and receive a designation as a national security risk, threatening its partnerships with other providers. For Anthropic, the loss is not just the $200 million DOD agreement ceiling it won in July 2025.
 
On Feb. 12, Anthropic executives said the company’s run-rate revenue was $14 billion, and it raised $30 billion at a $380 billion valuation that same month. A few weeks later, Anthropic executives told a court the Pentagon blacklist could reduce 2026 revenue by multiple billions of dollars. Company leadership has also argued that the formal legal scope is narrower than the political rhetoric and that it should apply only to Claude’s use in direct DOD contract work, not all business with contractors. Reuters reported the Pentagon left room for exemptions in “rare and extraordinary circumstances.”
 
That means the real financial risk is probably not one canceled award but rather a pipeline contamination: Contractors derisking away from Claude, slower federal conversions, and reputational drag in defense-adjacent enterprise sales. Put differently, the $200 million ceiling is only about 1.4% of Anthropic’s disclosed $14 billion run rate, so the “multiple billions” warning has to be about second-order effects, not just the contract itself.

OpenAI gains short-term incremental revenue opportunity but should benefit even more significantly long-term

For OpenAI, the near-term revenue uplift is real but probably less dramatic than the strategic win. OpenAI’s federal posture was already building before Anthropic’s rupture. OpenAI launched and scaled usage of ChatGPT Gov, announced a $200 million-ceiling pilot with the DOD’s Chief Digital and Artificial Intelligence Office, struck a General Services Administration (GSA)-wide deal offering ChatGPT Enterprise to agencies for $1 per agency for a year, brought ChatGPT onto GenAI.mil for a platform used by 3 million civilian and military personnel, and most recently added an Amazon Web Services (AWS) route to sell models to U.S. defense and government agencies for classified and unclassified work.
 
Although the U.S. government activity is notable, it still represents a small portion of OpenAI’s overall revenue, which was rumored to have surpassed a $25 billion run rate as of early 2026. Put in this context, a $200 million government award represents only 0.8% of that run rate. However, the much bigger financial effect is strategic: Anthropic’s loss makes OpenAI the default frontier-model substitute for defense buyers, which should raise public-sector lifetime value, accelerate follow-on pipeline conversion, and strengthen valuation support.

Palantir’s position as the government AI control plane is reinforced

The impact on Palantir of the change in DOD AI provider from Anthropic to OpenAI includes a very modest short-term financial upside and, more importantly, a reinforcement of Palantir’s position underpinning U.S. government AI technologies. Palantir clearly leans into DOD engagement and lacks any qualms about the use of its technology by the military and controversial domestic agencies like Immigration and Customs Enforcement. Palantir’s revenue is also much more highly dependent on the government sector; in 2025, $2.4 billion of Palantir’s total revenue, or roughly 53.7%, was generated by government contracts.
 
Palantir’s FedStart program is an on-ramp to absorb the federal compliance burden for other vendors on a usage basis, with Palantir handling ATO (Authority to Operate) conversations, compliance artifacts, continuous monitoring and control assessments. Anthropic joined FedStart in 2025, but Palantir integrates multimodal AI and its partners with Microsoft to operationalize Azure OpenAI in classified government environments.

Explore deeper data and analysis

With TBR Insight Center’s interactive data visualization tool, your team can quickly adapt the thousands of data points within the AI & GenAI Model Provider Market Landscape, Cloud Data & Analytics Market Landscape and U.S. Federal Cloud Ecosystem Report for tailored competitive analysis, go-to-market strategy and executive briefings. The tool enables you to curate relevant quantitative insights by company, business unit and/or market segment, creating a report specific to your needs and ensuring consistent frameworks across projects.
 
Click here to explore Insight Center’s data visualization tool, or start your free trial today to access this one-of-a-kind digital-first intelligence platform.
 
If you believe you have access to the full research via your employer’s enterprise license or would like to learn how to access the full research, click here.
 

Salesforce Highlights Strengths in Innovation and Relationships at Agentforce World Tour

On Feb. 25, 2026, TBR attended Salesforce’s Agentforce World Tour event in Sydney along with 10,000 Salesforce professionals, clients, alliance partners and analysts. The following reflects TBR’s observations and discussions during the event as well as our ongoing assessment of Salesforce and its ecosystem partners. TBR’s Salesforce analysis can be found in its quarterly vendor reports, the Cloud and Software Applications Benchmark, and the Adobe and Salesforce Ecosystem Report.

‘Everyone is looking to agency [agentic AI] to drive their companies forward’

During a panel discussion with Salesforce clients, Australian business leaders and Salesforce executives discussed best practices for enterprisewide agentic AI adoption and for scaling pilots. Panelists mentioned common ideas such as ensuring clear ownership of projects and agents, defining desired outcomes at the start of any engagement, and co-locating technology teams with business teams (this blog and others from TBR dive into best practices for IT services companies, consultancies, technology vendors and enterprises with respect to agentic AI adoption).
 
One Salesforce leader noted that clients have expressed frustration that AI has simply allowed them to write better emails. Salesforce, he added, is working to show ROI at scale and “get more production value out of these products.” In TBR’s view, AI adoption sentiments expressed in keynotes, panel discussions, and show-floor discussions with Agentforce attendees reflect common themes around well-understood best practices, concerns and fears about enterprisewide adoption, and confidence that 2026 will deliver clear, measurable and significant ROI from agentic AI investments. This last point may reflect the setting and vibe of the event, although many of the specific use cases described by Salesforce professionals and Australian clients reinforced an overall sense about agentic AI.

‘As a leader, if you think AI is going to replace people, you have more problems than [adopting] AI’

At another point during the panel discussion, the CEO of an Australian student accommodation business described the leadership challenges inherent in adopting AI at scale, both within her company and in her experience speaking with fellow CEOs in Australia. She commented that the most significant hurdles were rooted in business processes and people, not in the technology, and that leaders who failed to consider enterprise resilience from a business perspective would likely fail to gain significant benefits from adopting AI-enabled solutions.
 
This CEO’s comments echoed the sentiment expressed by Sanjna Parulekar, SVP of product marketing at Salesforce, who said “context is king” (in adopting agentic AI) and that companies should focus on business workflows, particularly as large language models increasingly examine business workflows. Parulekar also noted that understanding AI-driven change management, including changes in roles and responsibilities, could help companies break down silos and more rapidly transform their business models.
 
In TBR’s view, the quote in this section’s subhead perfectly captures this CEO’s dilemma at present: AI promises a productivity boost when bots replace people, but successful adoption at scale seems to require more people with different skills. Digital full-time employees (FTEs) are not yet cheaper than human FTEs, but slow-rolling adoption seems untenable. What to do? For Salesforce, and the company’s consulting partners in attendance at Agentforce, the answers are clear: more software, more platforms and more AI, all aimed at solving business problems, not just adding technology for technology’s sake.

Salesforce in the public sector

In a special breakout session, Salesforce’s local and global public sector leaders made three critical points about the company’s overall public sector strategy and recent performance:

  1. Licensing and permitting have been taking off as a use case, frequently tied to efforts to accelerate economic development.
  2. Governments across all levels have been looking for consolidation, from point solutions to a platform, especially in the U.S.
  3. As part of Salesforce’s public sector push in the U.S., the company has been providing partner-like training to employees at government agencies, disrupting traditional systems integrators. Notably, according to Salesforce, U.S. federal government agencies are increasingly looking to Salesforce to be the prime contractor on technology-centric engagements.

 
With the recent hype around the “death of SaaS” and other pressures on the business models of technology companies, Salesforce’s growing presence, success, and apparent disruption of competitors and alliance partners alike underscore Salesforce’s strengths in creating stickier client relationships and continually innovating, two qualities essential in the agentic AI age.
 
TBR’s overall takeaway from a day with Salesforce in Australia: Software is not dead. SaaS is not dead. Different wrappers, innovative use cases and deeply embedded relationships, both personal and technological, underscore Salesforce’s strength.

Federal IT Spending Trends: Why Growth Is Contracting and Where It Is Shifting

TBR estimates the federal IT market will reach nearly $140 billion in total market value by CY30, growing at a 2.2% CAGR between CY26 and CY30. After federal IT spending surpassed $126 billion in CY24, the Trump administration’s Department of Government Efficiency (DOGE) and the 43-day federal shutdown upended the federal IT market, severely disrupting federal technology procurement, particularly in the civilian space. Growth slowed significantly in CY25, and TBR projects overall federal IT spending will contract in CY26, primarily due to continued softness in civilian IT spending. IT spending in the defense and intelligence segment remained essentially stable in CY25, and growth will accelerate to midsingle-digit rates by CY27.
 
TBR anticipates the civilian IT market will remain very challenging in federal fiscal year (FFY) 2026 with continued volatility in agency IT budgets, unexpected stoppages on ongoing programs, and continued scope reductions or outright cancellations of discretionary, consulting-focused spending. Stabilization in the civilian market might not occur until FFY27, but this remains unclear. Conversely, the Trump administration has proposed a double-digit increase in defense spending, which will flow through to IT budgets in the Department of Defense (DOD) and Intelligence Community (IC), particularly in areas of national security (e.g., missile defense, enhancing cybersecurity offense as well as defense and border security), which will receive top priority. Federal IT acquisition is also slowly pivoting to embrace outcome-based contracting, while the DOD looks to accelerate IT purchasing by adopting new and innovative IT procurement approaches.

DOGE’s aggressive review of consulting contracts and the advisory aspects of IT services awards in FFY25 may have negative downstream consequences for IT transformation engagements

Scenario 1: What if DOGE-related termination and scope reduction of consulting contracts in FFY25 negatively impact broader digital transformation engagements in subsequent years?

TBR estimates that as much as 90% of DOGE-related terminations were for services (not product) contracts, affecting over $20 billion worth of engagements in FFY25. TBR believes tighter scrutiny of advisory work is now the standard in federal IT and professional services procurement, and this will remain the case for the foreseeable future. Several federal systems integrators (FSIs), particularly those hardest hit by the cancellations or scale-backs of consulting contracts in FFY25, are now apprehensive about how the new normal in federal IT procurement could impact future engagements.
 
Contractors fear that because DOGE’s definitions of “consulting services” were imprecise and ambiguous, even services contracts that are predominantly technology-based could be subject to gratuitous or needless scrutiny, especially given the heightened pressure that vendors will be under to clearly demonstrate how new IT programs will streamline operations and reduce operating costs.
 
To avoid having legitimate IT services erroneously reclassified as nonessential “consulting services,” FSIs will reframe IT transformation engagements to emphasize operational improvement, directly link fees to measurable outcomes and increase leverage of reusable modernization platforms. Vendors will also more heavily underscore the AI and cybersecurity components of an engagement while productizing more elements of their respective portfolios.
 
The traditionally advisory aspects of a digital transformation or IT services engagement will have to be deemphasized, or provided pro bono, potentially eroding margins and future margin opportunities. FSIs will need to defend pricing by directly tying billing to customer savings as efficiency requirements continue to expand across the federal IT landscape. Federal IT contractors across the board will also have to lean heavily into the embrace of outcome-based, fixed-price contracting in federal IT procurement.
 
CACI stands out to TBR as an FSI uniquely positioned to adapt to the evolving environment, as its portfolio has steadily shifted toward more platform- and product-based solutions over the last several years, while the company has been evolving its delivery model to be more software-centric, IP-heavy and outcome-focused. Despite having adopted more of a consultative mindset in recent years, CGI Federal has also been promoting longer-term, platform-based solutions (and winning strategic engagements with these offerings) to modernize and streamline federal financial, supply chain and procurement systems — an approach that may enable the company to avoid having its technology-based offerings mistakenly interpreted as nonessential consulting services. Leidos has been expanding its suite of repeatable digital solutions to enhance project governance and the predictability of program workflows and costs, while increasingly splitting up parts of larger contracts and rescoping to deliver according to outcome-based criteria.

Federal IT decision makers may slow their adoption of AI if deployments do not produce results; uncertainty in the federal market could result in greater responsibility for FSIs

Scenario 2: What if there is not a meaningful, instant ROI on AI?

Technology integration drives production scaling and is traditionally a core competency of commercial vendors. The challenge for these companies ultimately lies in demonstrating meaningful value and at scale. Although proprietary AI platforms are table stakes for them, a study by the Massachusetts Institute of Technology in July 2025 discovered that only 5% of enterprise AI deployments were able to produce a quantifiable ROI.

Scenario 3: What if hyperscalers become more risk-averse?

As FSIs’ contracts came under scrutiny from DOGE and the 43-day government shutdown throttled vendors’ operations, hyperscalers also experienced disruptions. Given the federal market’s recent instability, hyperscalers like Amazon Web Services and Microsoft may ultimately become more risk-averse.
 
Several FSIs such as ICF International have leaned into commercial energy and other areas to mitigate the material impact of these disturbances. Similarly, hyperscalers could try to reduce their risk by limiting their exposure. Hyperscalers may be more selective with bidding, pursuing fewer opportunities where the cloud service providers are the primes. Hyperscalers would also shift their rapidly evolving partnership models to make FSIs bear more accountability, potentially trimming vendors’ top and bottom lines by forcing them to manage the expanded delivery risk and take on greater workloads. Additionally, the demand for cleared talent — particularly cloud security engineers — would surge, further pressuring FSIs’ margins.

New Research: Federal IT Services Market Forecast

Technology Business Research, Inc., is pleased to announce the launch of the Federal IT Services Market Forecast, the first market forecast in our Federal IT Services research area.
 
“The extreme volatility in the federal IT market in 2025, after a multiyear run of unprecedented growth, has left federal IT vendors and their partners scrambling to make sense of how future near- and long-term technology investments by the world’s largest single buyer of IT and IT services will play out,” said TBR Senior Analyst and report co-author John Caucis.
 
“Our new Federal IT Services Market Forecast provides TBR’s unique insights, developed through the lens of the leading federal systems integrators (FSIs), regarding federal IT spending trends over the next five years and how the industry’s largest IT contractors will adapt to shifting federal technology investment patterns.”
 
Focusing on the top 11 companies serving the U.S. federal government’s IT services needs — Accenture, Booz Allen Hamilton, CACI, CGI, IBM Consulting, ICF International, Leidos, KBRWyle, General Dynamics Technologies, Maximus and SAIC — this report includes five-year CAGR analysis for each covered company and analysis of both the civilian sector and the defense and intelligence sector.
 
The first publication of this annual report is now available. If you would like to learn how to access the full research, click here.


Governance Becomes a Prerequisite for Success with AI 

Governance was a recurring theme across content sessions and executive meetings at Mobile World Congress 2026. As telecom operators move from experimentation to operational in AI, creating a corporatewide, centralized framework for data management, model oversight and regulatory compliance is becoming essential. Without clear governance, AI initiatives often remain fragmented across business units, leading to inconsistent outcomes, duplicated efforts and limited enterprise impact.
 
The challenge is that most telecom operators still lack a horizontal governance model for both AI and data. Data ownership is often siloed, policies vary by department and there is limited visibility into how models are trained, deployed and monitored. This fragmentation makes it difficult to scale AI beyond isolated pilots and increases operational, regulatory and reputational risk.


Telecom operators with strong C-suite sponsorship are best positioned to overcome these challenges. Executive backing helps enforce common standards, prioritize enterprisewide data initiatives and ensure AI programs are aligned with broader digital transformation objectives. Without this level of leadership support, governance efforts often stall as organizational silos resist change.
 
Leading telcos are beginning to formalize governance by creating centralized data offices and appointing chief data officers responsible for enterprisewide data strategy and governance. In practice, robust governance is quickly becoming a prerequisite for AI. Organizations that establish clear frameworks for data quality, access, security and accountability will be far better positioned to operationalize AI at scale and consistently generate business value.

More from Mobile World Congress 2026

MWC26 made clear that the telecom industry is entering a new phase shaped by the convergence of AI, geopolitics and digital infrastructure. While AI dominated the conversation, the broader narrative that emerged centered on control, resilience and trust in an increasingly complex digital environment.
 
Click here to read our lead telecom analyst’s full recap of Mobile World Congress 2026.

New Growth in Consulting Is Emerging from an Unexpected Place: Managed Services

Managed services teams embedded at clients are quietly evolving into the front line for strategy and advisory opportunities

This spring, TBR will mark 15 years of publishing the semiannual Management Consulting Benchmark, and the basic structure remains essentially the same. Although this consistency is remarkable, consulting seems to be the only business model left undisrupted. Sure, technology now permeates everything, the talent pyramid faces structural change, and a good large language model might be capable of replacing an entry-level consultant, but the biggest firms continue to grow and provide answers to “tell me what to do and how to do it.” Consulting went through a rough patch from 2023 to 2025, but now we’re looking at a resurgence. Even as some industry experts see the Big Four dying alongside SaaS and private equity cutting the fat from strategy consultancy, TBR sees a few reasons to be more than bullish on management consulting in 2026 and 2027. Let’s start with where those consulting opportunities increasingly come from.
 
For the last couple of years, TBR has heard more and more consultancies and IT services companies describe a gradual shift in managed services, with professionals on-site at clients uncovering new management consulting opportunities and becoming, in a sense, the tip of the spear — a role traditionally played by strategy consulting. This is a significant change. If the trend accelerates and reaches scale, business models will change. For now, managed services as an entrée to management consulting remains a tactic for some and an aspiration for others. Years of use cases, experience and results lead TBR to believe managed services will contribute significantly to the growth of management consulting going forward.

Management services will positively impact consulting engagements — just not for everyone

OK, so managed services brings new opportunities, but for which consultancies? A better question: Will managed services enable traditional IT services companies to finally break through meaningfully into management consulting? Yes, massive IT services companies that have flirted with McKinsey-like consulting capabilities over the last couple of decades will be able to uncover and deliver on consulting opportunities based on their deep understanding of clients’ IT environments and business challenges. And accelerated AI adoption at enterprise scale will increase transparency and uncover opportunities for every IT services company and consultancy.
 
A scaled managed services practice trained in spotting consulting opportunities and armed with AI-enabled solutions will unquestionably win some management consulting market share. More significantly, from TBR’s objective view, is whether the Big Four firms can manage their staffing, brand promise and technology alliances to take advantage of the managed services practices they’ve already built and use those opportunities to return to robust management consulting growth. Maybe, but probably not all four. The next two years will be telling, and TBR expects the existing differences between the Big Four will become even more pronounced.
 
All of that just to say: Managed services will increasingly lead to consulting engagements, growing the overall consulting pie — just not for everyone.
 
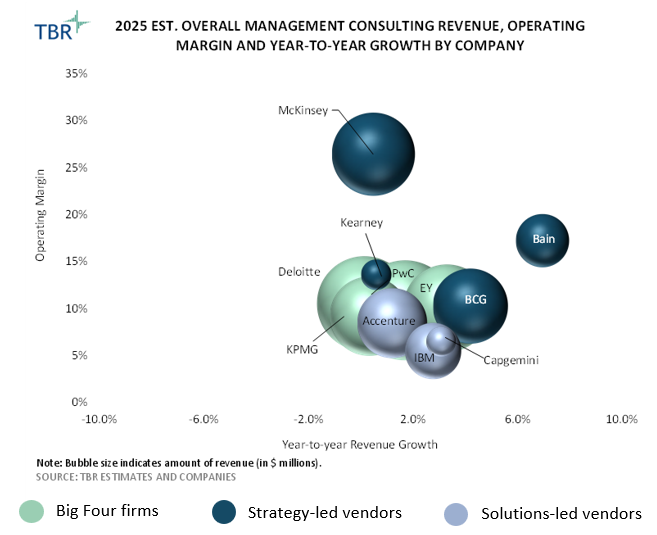
As we continue into 2026 and look ahead to 2027, we see the three main management consulting groups pursuing similar yet different strategies and three main trends influencing how they execute those strategies. The Big Four firms (Deloitte, EY, KPMG, and PwC) continue to invest in and emphasize their industry expertise as differentiators, particularly in management consulting. McKinsey & Co., Boston Consulting Group (BCG) and Bain have all increased their technology capabilities and stressed to their clients and alliance partners (yes, they now have technology alliance partners!) that they’re deeply versed in emerging technologies, including AI.
 
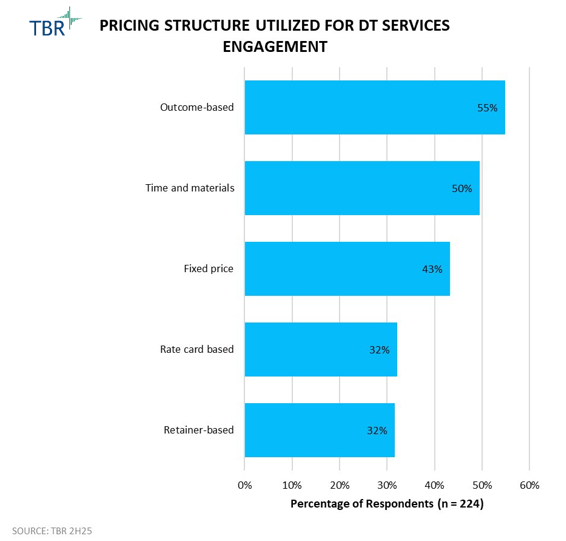
And the IT services-centric consultancies, such as Accenture, Capgemini and IBM, continue to expand and contract their consulting practices, always returning to the same “end-to-end” set of offerings. (Yes, those are generalities. For specific analysis of each company, see TBR’s semiannual Management Consulting Benchmark.) Across the entire management consulting space, TBR sees increasing client demand for outcomes-based pricing, particularly as AI enables greater transparency across every aspect of an enterprise; talent management (within consultancies) emerging as a strategic lever for consultancies’ own business model reinvention; and AI permeatingeverything.
 
Looking beyond 2026, TBR sees three reasons to bet on growing demand for management consulting. First, AI-related confusion, FOMO (fear of missing out) and adoption will create massive, seemingly relentless opportunities for consulting. If you doubt that, consider how well your own company has adopted AI and how much AI has changed just since January 2025. Second, the managed-services-to-management-consulting pivot described above, combined with AI, will enable more competitors to stand up capable and scaled management consulting practices. Does that mean more competition? Yes, but it also means more opportunities for the firms that have established permission and people and can continue investing in capabilities without balancing those dollars (and margins) against other core businesses. Third, and a continuation of the previous point, the management consulting space will fracture into more highly specialized consulting firms, better-staffed IT services companies, and technology providers adding strategy consulting to their arsenal.

Explore deeper data and analysis

Over the last 15 years, technology has permeated every aspect of management consulting. This trend has been so persistent and significant that TBR has been increasingly asked if our taxonomy, which includes Strategy Consulting, Operations Consulting, Organization and Change Consulting, and Technology Consulting, still holds up. Indeed it does. Because while every consulting engagement includes technology, business model reinvention remains rooted in business: business strategy and operations and organization. And woe to the business that thinks AI doesn’t mean change management. Answering those core questions — what do I do and how should I do it — will provide opportunities for … let’s be ambitious and say millennia to come.
 
And we have the data.

2025 Estimated Management Consulting Revenue, Operating Margin and Year-to-year Growth by Company (Source: TBR)


Pricing Structure Utilized for DT Services Engagement (Source: TBR 2H25)


With TBR Insight Center’s interactive data visualization tool, your team can quickly adapt thousands of IT services and consulting data points for tailored competitive analysis, go-to-market strategy and executive briefings. The tool enables you to curate relevant quantitative insights by company, business unit and/or market segment, creating a report specific to your needs and ensuring consistent frameworks across projects.
 
Click here to explore Insight Center’s data visualization tool, or start your free trial today to access this one-of-a-kind digital-first intelligence platform.
 

Skills Shortage Will Challenge the Scaling of Sovereign AI in 2026

AI-related skills will remain scarce across both buyers and ecosystem partners as the rapid pace of innovation and the technical complexity required to enable sovereign AI continue to hinder adoption. These challenges, combined with a lack of clearly defined and compliant use cases among sovereign customers, gaps in sovereign cloud infrastructure availability and steep AI learning curve faced by ecosystem partners, will constrain meaningful investment and implementation of sovereign AI throughout 2026.

Sovereign AI momentum will build through partnerships in 2026, but meaningful financial impact remains a longer-term prospect

Sovereign AI will undoubtedly mature more quickly than the sovereign cloud market, but it is still too early to expect a noticeable financial impact from those capabilities in 2026. While Sovereign cloud did not develop until more than a decade after the general cloud trend was underway, it remains very nascent from an adoption and market development perspective. Widespread adoption of sovereign AI depends on deliverable sovereign cloud capabilities, among other requirements. Further complicating adoption is the advent of agentic AI, which introduces new risks by leveraging data that can be sovereign and sensitive and by taking action on the intelligence produced.
 

Despite the challenges to widespread adoption of sovereign AI in 2026, we expect vendors across the spectrum of business models to aggressively partner and invest to capitalize on the opportunity in this emerging segment. Partnership activities will center on the strongest sovereign AI providers and the most well-established sovereign cloud regions, as would be expected. Amazon Web Services (AWS) and Microsoft are the clear leaders in sovereign cloud delivery capabilities, and their geographic focus will remain the U.S. and Europe, particularly Germany. The U.K. should also see concentrated investment and lead in early adoption.
 

Watch now: 2026 Predictions for Cloud & Software, featuring Senior Analyst Alex Demeule


In some ways, the development of sovereign AI will look much like the Industrial Revolution, which disproportionately benefited the developed countries that had access to resources and oil to fund the new economic model. Microsoft and AWS have already announced specialty partner programs for sovereign AI and big-name alliances with the likes of Accenture and SAP. We expect those alliances and ecosystems to become more AI-focused in 2026, providing tighter integration between cloud providers, model providers, SIs and ISVs that will form the foundation for sovereign AI growth in 2027 and beyond.
Explore more SaaS predictions for 2026 in our special report Will AI be the Death of SaaS in 2026?

PaaS Revenue Will Outpace SaaS Revenue for Cloud Software Vendors

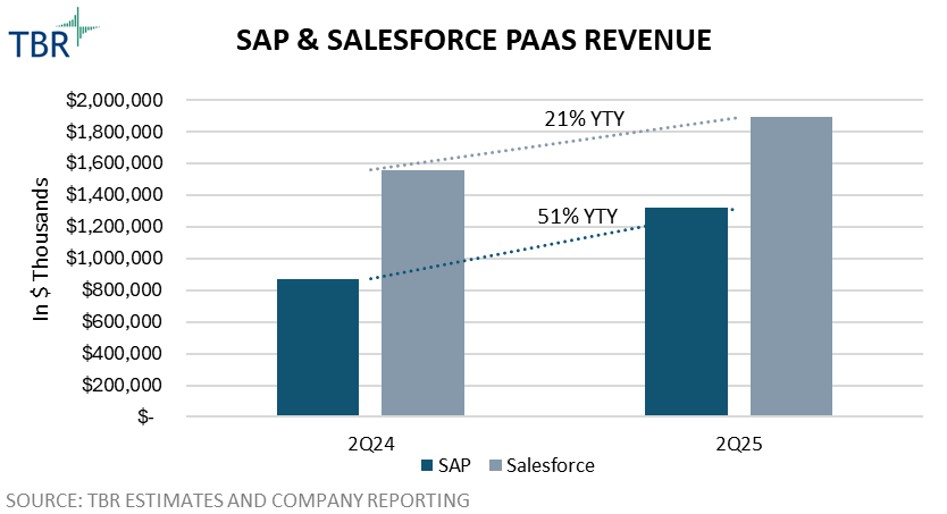
Enterprise customers are prioritizing the modernization of their existing SaaS estates rather than adding new applications, driven by market saturation, accumulated technical debt, and a growing imperative to become AI-ready. As IT buyers shift their focus toward modern platforms, traditional SaaS leaders should expect their PaaS segments to continue significantly outperforming their core SaaS businesses in revenue growth.

A clear inflection in SaaS momentum emerges

SAP’s trajectory is tied to Business Technology Platform (BTP) becoming the architectural anchor of RISE programs. BTP is no longer an optional add-on but rather the control plane for process mining, metadata management and event-driven extensions. Attach rates above 80% in RISE cycles reflect SAP’s ability to position BTP as mandatory for modernization rather than discretionary middleware. The addition of Signavio and LeanIX broadened the portfolio, giving SAP a modern platform that starts with process intelligence and ends in a coherent data and extension strategy.
 

Salesforce is following a data-first path. Data Cloud has become the centerpiece of modernization discussions as the company works to consolidate fragmented CRM data models and unify cross-cloud metadata.
 

MuleSoft remains critical in stitching legacy systems into Salesforce’s AI-ready architecture, and early Data Cloud wins indicate customers view it as the foundation for copilots, agentic workflows and future small language model integration.
 

Both vendors benefit from a status as a highly trusted incumbent and deep process ownership, enabling them to sell platform capabilities not as adjacent tools but as prerequisites for becoming AI-ready.
 

SAP & Salesforce PaaS Revenue (Source: TBR)


Explore more SaaS predictions for 2026 in our special report Will AI be the Death of SaaS in 2026?