The Midmarket Opportunity: Which GSIs Can — and Should — Pursue It?
TBR Fourcast is a quarterly blog series examining and comparing the performance, strategies and industry standing of four IT services companies. This quarter we examine which global systems integrator (GSI), Accenture, Atos Group, Capgemini or Deloitte, can expand into the midmarket and which has the strongest reason to do so. GSIs have pursued midmarket clients before, but the economics have rarely supported the same delivery model used for large enterprises. AI-enabled platforms and more repeatable solutions could change that equation by lowering delivery costs and speeding deployments.
What is old is new again — or is it?
Expanding into the midmarket has been a recurring theme for GSIs for many years, and some are dusting off that strategy yet again. This time, platform-led operating models that are less linked to FTE-based pricing may change the game. When looking at Accenture, Atos Group, Capgemini and Deloitte, which company could reasonably enter or expand into the midmarket? More importantly, which should?
GSIs all serve the midmarket in some capacity. Some have clear organizational structure while others have some solutions available (or sometimes tailored) to this segment of clients. Capgemini’s Sogeti brand, which has been in operation since the early 2000s, expands Capgemini’s reach to the midmarket and locally managed accounts while continuing to serve selected large enterprises.
Accenture’s launch of its midmarket business Accenture Edge has thrown the matter into discussions again.
Deloitte offers IT services to midmarket clients indirectly, presumably through Deloitte Private, a formalized global network serving private and family-owned businesses. In addition, Deloitte’s tax business provides an opening to midmarket clients, especially as the firm looks to lean on more platform-based sales in its broader services business. Its member firm structure lends itself to a nimbler delivery structure, which could provide an advantage, even if it presents consistency challenges at a large scale.
Atos Group is earlier in that process. We’ve included Atos Group because of its recent announcements around entering the midmarket with the release of Digital Workplace as a Service. Further, Atos Group’s smaller employee base compared to other peers and strong regional revenue in Europe make it a respectable contender for midmarket.
What is midmarket?
At TBR, we often hear the question, “What is the midmarket?” Definitions vary at each of the companies in this quarter’s Fourcast.
Interestingly, Capgemini does not have a publicly available definition but identifies midmarket companies as having $100 million to $1 billion in annual revenue in Capgemini’s Research Institute’s report, Navigating Uncertainty with Confidence: Investment Priorities for 2025. Sogeti targets “growth-oriented” clients across all industries and maintains a strong local presence in 13 of the approximately 50 countries in which Capgemini operates. Sogeti’s services portfolio encompasses advisory, implementation and managed services around AI and generative AI (GenAI), cloud, data and applications.
Accenture Edge addresses clients that achieve $300 million to $3 billion in revenue. Accenture Edge spans cloud and infrastructure, talent and HR, finance and ERP transformation as well as Amazon Web Services’ (AWS) productized portfolio. Accenture Edge has quickly established dedicated teams, including for Workday. Accenture has bought its way into the midmarket through acquisitions such as NeuraFlash, Cabel Industry, McCoy and COMWARE. Although many of these acquisitions add professional services capabilities on a new scale, Accenture Edge also includes existing services. For example, in March 2025 Accenture announced it was expanding to midmarket clients.
Atos Group is broadening its midmarket focus, which it defines as 5,000 to 15,000 employees. As discussed in TBR’s 2Q26 Atos Group report, “Atos business released Digital Workplace as a Service (DWPaaS), which is a modular, AI-enabled solution delivered through a subscription model that is built for midmarket companies. Alongside the ServiceNow-based Service Management as a Service, which provides midsize businesses with preconfigured modules, rapid implementation and predictable costs, DWPaaS reflects a broader effort to productize the Atos business’s enterprise capabilities for the midmarket.” Although Atos Group is making a more obvious shift now, the company has made solutions available to clientele with a smaller employee base, such as its Network Advisory Solutions and its Atos AMOS-AI with Red Hat OpenShift AI recently.
Deloitte has significant experience with midmarket clients through Deloitte Private and its tax business, where it is most likely to encounter clients of this size. According to the Deloitte US 2023 Mid-Market Technology Trends Report, Deloitte defines the market as between $250 million and $1 billion. Deloitte Private offers strategy, design, implementation and optimization for cloud solutions, including Microsoft ERP, Oracle NetSuite, SAP and Workday. In 2026 Deloitte announced it combined Odoo’s ERP platform with Deloitte Digital Mix services for scaleups and midmarket businesses, including family-owned and private-equity-backed companies. In conjunction with its tax business, the firm has reasonable means to expand further into the midmarket.
Although definition may vary across these four companies, delivery problems are similar. For GSIs, securing presence in the midmarket has been anything but clear. Accenture’s earlier experience shows why the economics matter. In 2015 Accenture acquired Cloud Sherpas, a Google Apps/G Suite services and reseller business that included midsize customers. By December 2017, Accenture had stopped renewing G Suite licenses for smaller customers and was referring them back to Google, saying that managing those licenses was “no longer a fit for our business model.” Agentic operating models and reusable AI assets are changing the delivery economics, making smaller engagements and midmarket clients commercially viable. Relevant capabilities include Accenture’s AI Refinery and Accenture GenWizard; Atos Group’s Atos Polaris AI Platform and Sovereign Agentic AI Studios; Capgemini’s Resonance AI Framework supported by its Reliable AI Solution Engineering (RAISE) agentic AI foundation; and Deloitte’s Deloitte Ascend and Zora AI.
Now that GSIs have more capacity, and perhaps more margin protection, from these agentic platforms, they will need to consider how go-to-market strategies are different in this segment. For starters, they should assess the approach of enterprise systems integrators (ESIs), which already cater to a smaller market. According to TBR’s Summer 2026 Enterprise Systems Integrators Market Landscape, which characterizes ESIs as fewer than 100,000 employees and/or less than $1 billion in annual revenue, “Enterprise systems integrators (ESIs) traditionally need to focus on a country or region, a select few industries or a technology niche, at least in their early stages.” With less resources, ESIs need to be wary of spreading themselves too thin, and the aforementioned report describes how localization is likely the most important element.
It is essential to remember that there are two sides to every story, and winning midmarket revenue share will mean displacing ESIs and other smaller players. The Enterprise Systems Integrator Market Landscape also discusses how, “In the last 18 months, seemingly every GSI and global management consultancy has announced strategic shifts toward the midmarket, including portfolio realignments and new, targeted go-to-market motions. ESIs cannot ignore these competitive threats and must play to their strengths, including established relationships, lower prices and more intimate, on-the-ground knowledge. Notably, in an AI age, the GSIs will likely erode any competitive advantages the ESIs have in the latter two areas, making relationships and client retention more critical.” On the GSI front, battling ESIs will mean coming up against their localization, specialization and prices.
Location matters
According to Accenture’s announcement introducing Accenture Edge, the business will launch in “priority markets around the world with partner-specific solutions.” Each of the four acquisitions Accenture made recently was used to expand midmarket capacity capabilities for a specific partner and region, although there is no one region or one partner focus across its current midmarket play. For example, Cabel Industry focuses on Italy and on Salesforce and AWS, while COMWARE serves only Japan for SAP and Salesforce services. Accenture is deploying its midmarket strategy in certain pockets of the world simultaneously. Unlike the typical GSI market, there are many competitors in the midmarket to monitor when launching this initiative worldwide. Accenture’s acquirees likely know their local competition well, but managing competitors across the globe may be more challenging.
Capgemini and Deloitte Private have been able to navigate local competition as they have supported midmarket clients for years, but Accenture and Atos Group do not have the same luxury of time to understand their competitors as many enter, or re-enter, the midmarket. On the client side, there are varying levels of opportunity depending on region. According to Capgemini’s Research Institute’s report, Navigating Uncertainty with Confidence: Investment Priorities for 2025, European midsize companies trail American midsize companies in technology investment and adoption.
Although not particularly surprising, in conjunction with Europe’s push for sovereign solutions and domestic technology, this could present a unique opportunity. Atos Group’s midmarket strategies are naturally concentrated in Europe, given its refreshed attention to its core geographies, primarily western Europe. The Group also aligns strongly with France’s technology goals. Atos Group recently renewed its participation in the “Je choisis la Franch Tech” (“I choose French Tech”) initiative, joining 22 major French companies that collectively pledged to invest more than $2.3 billion in French startups and scaleups. As France and central Europe emphasize technological independence, Atos Group’s participation in the French Tech initiative and deep reach in the market may be a value-add compared to GSIs, particularly those with stronger ties to the U.S.
A strength when addressing the midmarket is the ability to be nimble. For Deloitte Private, which operates across client teams globally in many, but not all, member firms, it is well-equipped to handle clients of this size. Deloitte’s member firm structure already operates similarly to what Accenture is likely trying to emulate with its acquisitions: a small, localized team able to meet the needs of smaller clients with the backing of the parent company’s full portfolio strength. On the flipside, Deloitte is moving toward a more global image, evidenced by the launch of Deloitte EMEA. In summary, fielding competitive threats is vital, but meeting clients’ needs quickly, onshore, and at the right price is even more important.
Budgets and branding
Localization is one challenge, and the delivery model creates another. With traditional time-and-materials delivery, the midmarket was less attainable, as smaller clients required designated sales and delivery teams. A platform-led approach makes the market accessible, but the new delivery model presents challenges around branding. A platform-led approach may be great for clients looking to save money, but for clients needing more hands-on support, it remain to be seen whether GSIs can provide the same attention to detail as ESIs or smaller players. GSIs must show that repeatable delivery can support attractive economics at smaller contract values.
If IT services companies’ new agentic-enabled operating models reduce labor intensity and improve economics, challenges around branding and pricing may arise. Specifically, consider these three questions:
- How can GSIs maintain their reputation for “premium” service quality when providing a less hand-on approach through agentic platforms?
- Will this create a divergence in pricing expectations for the large and small contracts? Do GSIs need to develop messaging for two buyer personas?
- If time-and-materials delivery is needed, will midmarket clients experience sticker shock? The answer will depend partly on what each company can offer that smaller competitors cannot.
When marketing to midsize companies, the four companies have largely similar messaging about their value proposition. For Sogeti, a popular marketing message is that “challenges feel smaller, when your partner feels bigger.” This implies that a bigger company may be able to provide better quality through better solutions. There may be some truth to this sentiment, given GSIs often have early access to partner solutions and extensive coinvestment relationships. Capgemini recently expanded its relationship with Google Cloud to provide access to AI-powered sovereign solutions, such as Gemini Enterprise Agent Platform, which incorporates capabilities previously offered through Vertex AI. Beyond new, innovative solutions, GSIs could hold an advantage in more competitive pricing if agentic platforms can effectively cater to midsize clients with less human support.
Otherwise, GSIs may struggle to sell to midmarket clients with widely available solutions, such as AI model adoption or cloud migration, that require additional support. A strength among ESIs and other smaller players is a designated niche such as region, industry or technology partner. Accenture, Atos Group, Capgemini and Deloitte each operate globally, across industry and across the technology stack. How can these four companies compete with smaller players’ specialization? Operating under another brand is one answer. If Atos Group continues down the midmarket path, will it create another sub-brand, like Accenture Edge and Sogeti? Will Accenture Edge go a step further and maintain the brand of its acquired companies to keep a more localized image?
Anyone can enter the midmarket, but who should?
For these four companies, it may be better to form networks based on the same thing: location (most likely), industry or partner..
For Atos Group, this network could center on sovereign solutions in Europe, especially enabled through Atos Sovereign Agentic Studios. Atos Group should pursue a selective midmarket strategy in Europe, in our view. Atos Group has a much smaller employee base compared to the other three companies discussed in this blog, at approximately 54,000 employees, compared to Accenture’s nearly 800,000 employees and Capgemini’s 418,000 employee base. Atos Group’s local connections in France and the rest of Western Europe better position the company to provide a personalized experience.
Deloitte’s decentralized structure organized by regions with varying expectations at the local level also lends itself to gain trust for midsize companies. The ability to provide more personalized delivery could help create a moat from other GSIs in the short term, before agentic delivery reaches maturity, or at least until consultants and clients become more comfortable. For example, a family-owned business may be less comfortable with a more hands-off delivery approach.
Accenture presents a different case. Competing on a very localized level will test the company’s ability to coordinate its portfolio of local capabilities without losing delivery speed or diluting technical expertise. Long-term, it may be better for Accenture to focus on breadth of offerings, which many ESIs cannot replicate. For example, Sogeti does not have a niche. The greater challenge may be maintaining smaller clients’ trust around its service quality and platform-led approach. We could discuss the importance of prudence, but Accenture is no stranger to reshaping its business ahead of enterprise demand. This raises the question: Why the push for midmarket clients? Outside a platform-based approach, we view the move as Accenture aiming to diversify revenue while testing a new delivery model for off-the-shelf solutions.
As part of the Fourcast, each quarter TBR examines the five-year growth trajectories of selected companies, which are depicted below. The graph represents a mix of reported company data and TBR proprietary data. The revenue outlook helps explain why the opportunity matters. Across the vendor group, midmarket growth will depend less on whether each company can serve these clients and more on whether it can do so with local relevance and repeatable delivery economics.
Accenture and Deloitte have a clear opportunity to use the midmarket as a growth engine because each company can use its partner reach and new platforms to expand client relationships. Capgemini already has a mature route through Sogeti, so the opportunity is more about extending an established model rather than opening a new market. Atos Group could benefit from targeted midmarket demand in Europe, particularly for repeatable workplace and sovereign offerings, but a selective approach would better fit its current scale.
For additional analysis on midmarket strategy, check out “Can the Big 4 Leverage AI to Capture Midmarket Opportunity?”
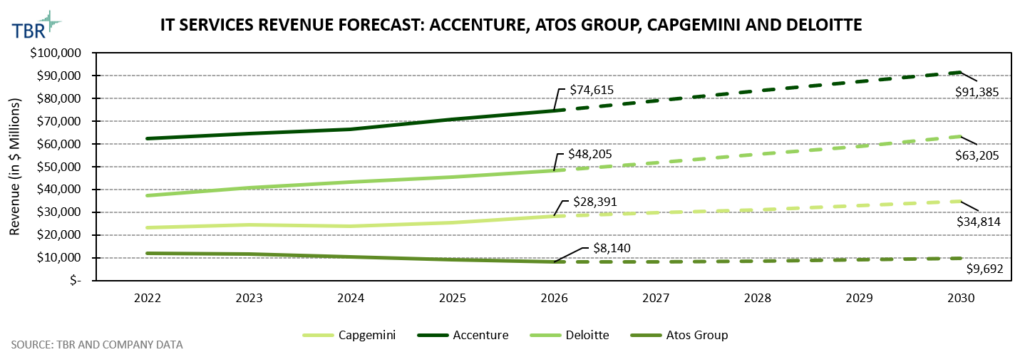
IT Services Revenue Forecast for Accenture, Atos, Capgemini and Deloitte for 2022-2030 (Source: TBR)